Author: Consultant

  • Trade Wars – Opinion/Commentary

    OPINION:

    2025 baseline already showed the hit. Goods exports −0.2% to $779B, imports +2.8% to $789B. U.S. exports −5.3% to −5.8%; U.S. surplus shrank from $101B to $82B. Non-U.S. exports +17% (UK gold, EU, China) did not fully replace lost U.S. volume. Export share to the U.S. fell to ~72%.

    What this latest round adds

    • Sept 29 bans (alcohol, motorcycles, whey, molasses) are small vs $715B+ two-way goods trade. Alcohol to the U.S. was already crushed by the 50% tariff; spirits take the production/jobs hit, craft beer less so.
    • Canada’s CA$28B countertariffs raise input costs for manufacturers that still buy U.S. parts, appliances, metals, farm equipment.
    • GSA procurement exclusion is a slow bleed for Canadian IT/office suppliers, not a 2026 GDP event.
    • The live threat is still autos/steel/aluminum/lumber and a possible 50% auto tariff from Jan 1, 2027 — not whisky.

    Macro channel

    • Growth: drag via lower export volumes, higher imported input prices, delayed capex. Not a recession trigger by itself if energy and USMCA-origin autos stay open.
    • Inflation: two-way tariffs = higher consumer and producer prices (alcohol, appliances, some food inputs). Partially offset by a weaker CAD if the Bank stays on hold.
    • CAD / BoC: more reason for a dovish bias if U.S. demand for Canadian goods keeps sliding; energy still the swing factor.
    • Labour: concentrated — spirits, some dairy ingredients, export-oriented manufacturing, logistics — not economy-wide unemployment spike.
    • Investment: the real cost. Rules changing every few weeks. Chamber point is correct: firms can price a 25–50% tariff; they cannot price a moving list.

    Who absorbs it

    • Exporters to the U.S. in targeted consumer goods: margin compression or lost sales.
    • Importers/retailers of U.S. goods: pass-through to Canadian consumers.
    • Provinces with alcohol/export manufacturing exposure (ON, QC, BC, Prairies energy less directly).
    • Winners on paper: import-competing domestic producers and any successful EU/Asia diversion. That substitution is multi-year, not Q4.

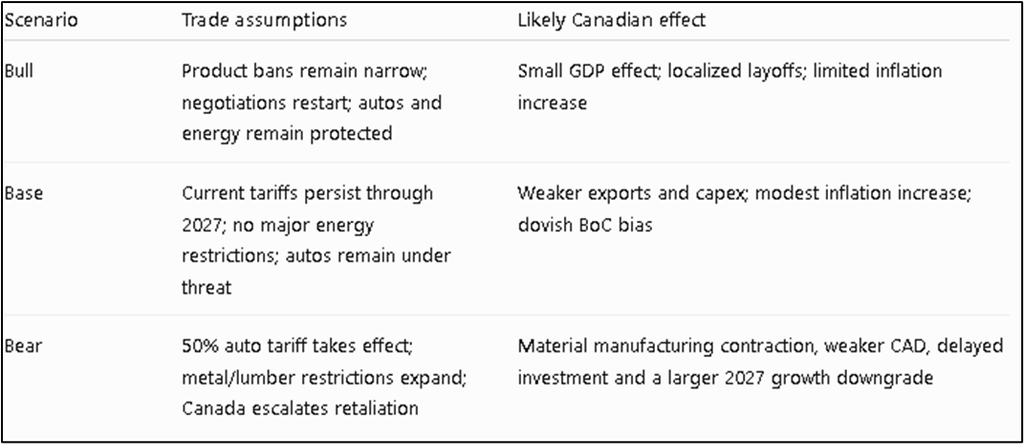
    Bottom line 2025 already priced a U.S. share loss and a wider goods deficit. This week’s bans are political escalation on a thin slice of trade. The economic damage scales with duration and whether autos/energy get pulled in. Stable high tariffs: manageable hit to GDP and a one-time price level shift. Unstable lists plus auto threat: investment freeze and a larger 2026–27 growth haircut.

    COMMENTARY

    Summary

    The analysis is directionally strong: the latest product bans affect a narrow portion of Canada–U.S. trade; autos, steel, aluminum and lumber remain the larger macroeconomic risks.

    The 2025 figures are broadly correct, but they demonstrate deterioration—not necessarily that tariffs caused the entire decline.

    Canada’s counter tariffs cover approximately C$27.6 billion of U.S. imports, commonly reported as about US$20 billion. Both figures should not be presented as though they use the same currency.

    One correction is important: a weaker Canadian dollar would generally increase imported inflation, not offset it.

    The strongest conclusion is that persistent policy uncertainty could damage capital investment more than the currently banned products themselves.

    Key Comments:

    1. The 2025 baseline is accurate, but causation needs qualification

    Canada’s 2025 merchandise exports declined 0.2% to approximately C$779 billion, while imports increased 2.8% to C$789 billion. Canada’s merchandise surplus with the United States fell from C$101.3 billion to C$81.6 billion. Global Affairs Canada, Statistics Canada

    However, “2025 already showed the hit” is slightly too definitive. The data show the outcome, but the decline also reflected commodity prices, exchange rates, inventory movements and changing U.S. demand. Better wording:

    “The 2025 trade data already showed the deterioration that tariffs and weaker U.S. demand subsequently intensified.”

    Non-U.S. export growth is encouraging, but the comparison is asymmetric: a 17% increase from a smaller base cannot quickly replace even a modest decline in the much larger U.S. market.

    2. The latest escalation is correctly characterized as narrow

    The bans announced September 8 and effective September 29 cover selected alcohol, dairy products—including whey and some molasses—and motorcycles. They are economically small relative to the US$715.5 billion in 2025 bilateral goods trade. Reuters, USTR

    Calling them “Sept. 29 bans” is understandable, but “bans effective Sept. 29” is more precise.

    The claim that craft beer is less exposed than spirits is plausible, but it should be tied to actual export volumes. Without that evidence, describe exposure as likely smaller, not established.

    3. Currency and inflation require correction

    Counter tariffs raise Canadian prices for affected U.S. imports.

    A weaker CAD makes most imported goods more expensive and therefore amplifies imported inflation.

    The weaker currency may help some Canadian exporters regain price competitiveness, but this benefit depends on foreign demand and imported-input content.

    The Bank of Canada therefore faces a trade-off: weaker growth supports easing, while tariff-related price increases and CAD depreciation limit its room to cut.

    “Dovish bias” and “stays on hold” are not necessarily contradictory, but the distinction should be clear: dovish guidance can precede rate cuts without implying an immediate move.

    4. The investment channel is the strongest part

    The central argument is persuasive:

    Stable tariffs can be incorporated into prices and supply-chain decisions; repeatedly changing product lists, rates and implementation dates raise the required return on investment and delay capital spending.

    That channel can become larger than the direct loss of exports. It particularly affects automotive plants, integrated steel and aluminum users, machinery producers and firms deciding where to place their next North American facility.

    The GSA exclusion is better described as a potentially cumulative sector-level drag. Its eventual impact depends on how many Canadian suppliers use the affected schedules, the value of their contracts and whether exclusions apply. Calling it definitively “not a 2026 GDP event” goes beyond the available evidence.
    What Would Disprove the Thesis

    Canadian manufacturing investment remains firm despite policy uncertainty.

    Export volumes to Europe and Asia replace lost U.S. sales faster than expected.

    Autos continue receiving effective tariff exemptions.

    Canadian firms rapidly substitute domestic or non-U.S. inputs without significant cost increases.

    Trade negotiations produce a durable agreement before January 1, 2027.

    Bottom Line

    The conclusion is sound after one material correction: CAD weakness increases imported inflation while potentially supporting export competitiveness. The newest bans are more politically significant than macroeconomically large. The decisive variables remain autos, energy, metals, lumber, tariff duration and whether policy uncertainty begins freezing Canadian business investment.

    Educational analysis only; figures and policy measures remain subject to revision.
  • Canada merchandise trade, calendar 2025 (CAD).

    otals from Global Affairs / StatCan year-end wrap; partner lines mixed BOP and customs sources — UK jump is largely gold.

    PartnerExportsImportsBalanceNotes
    All countries779.0789.0−10.0GAC Highlights; StatCan BOP deficit cited as −31.3 on a different compilation
    United States~558 (71.7% of exports)~464 (58.8% of imports)+81.6Exports −5.8%; imports −2.9%; surplus down from +101.3 in 2024
    United Kingdom46.6–49.5~10.8+36 to +39Gold-driven; exports +62% to +68%
    China34.4–34.965.2−30 to −31Exports +15%
    European Union~42.8~78.2−35Exports +23%
    Mexico8.9–9.435.0–53.4−25 to −44Imports +12% to +20% depending on series
    Japan14.616.0−1.3Exports −3%
    Germany9.2~19–20deficitExports +35%
    Netherlands9.5n/a in same cut—Exports +34%
    South Korea7.116.0−8.9Exports −7%
    Rest of world (ex-US)+17.2% y/y+12.4% y/y−112.9Non-US two-way trade +14.3% to $553B

    Read-through

    • U.S. still dominates, but export share fell to the lowest since the early 1980s (71.7–72.5% vs ~76% in 2024).
    • Diversification in 2025 was real on the export side (Europe/UK/China) and was not enough to offset the U.S. drop.
    • Canada ran a goods surplus with the U.S. and a large deficit with everyone else — same structure as prior years, wider gap.

    Figures differ slightly by BOP vs customs, total vs domestic exports, and whether gold is booked to the UK. Use StatCan table 12-10-0171-01 for a full country list.

  • Canada’s retaliatory tariffs worth $27.6 billion take effect as trade rift with U.S. deepens

    • Canada has introduced and raised tariffs on $27.6 billion worth of U.S. goods, including dairy, agricultural equipment, paper, household appliances and electronics.
    • U.S. steel, aluminum and iron products, furniture and clothing were hit with the highest rate of 50%.
    • Officials from Ottawa and Washington continue to publicly trade barbs, blaming one another for the failure to reach a trade deal.

    https://www.cnbc.com/2026/09/08/canada-retaliatory-tariffs.html

  • Altria Is Spending More on Capex Than Any Other Consumer Staples Name. It’s a Calculated Sign of Strength.

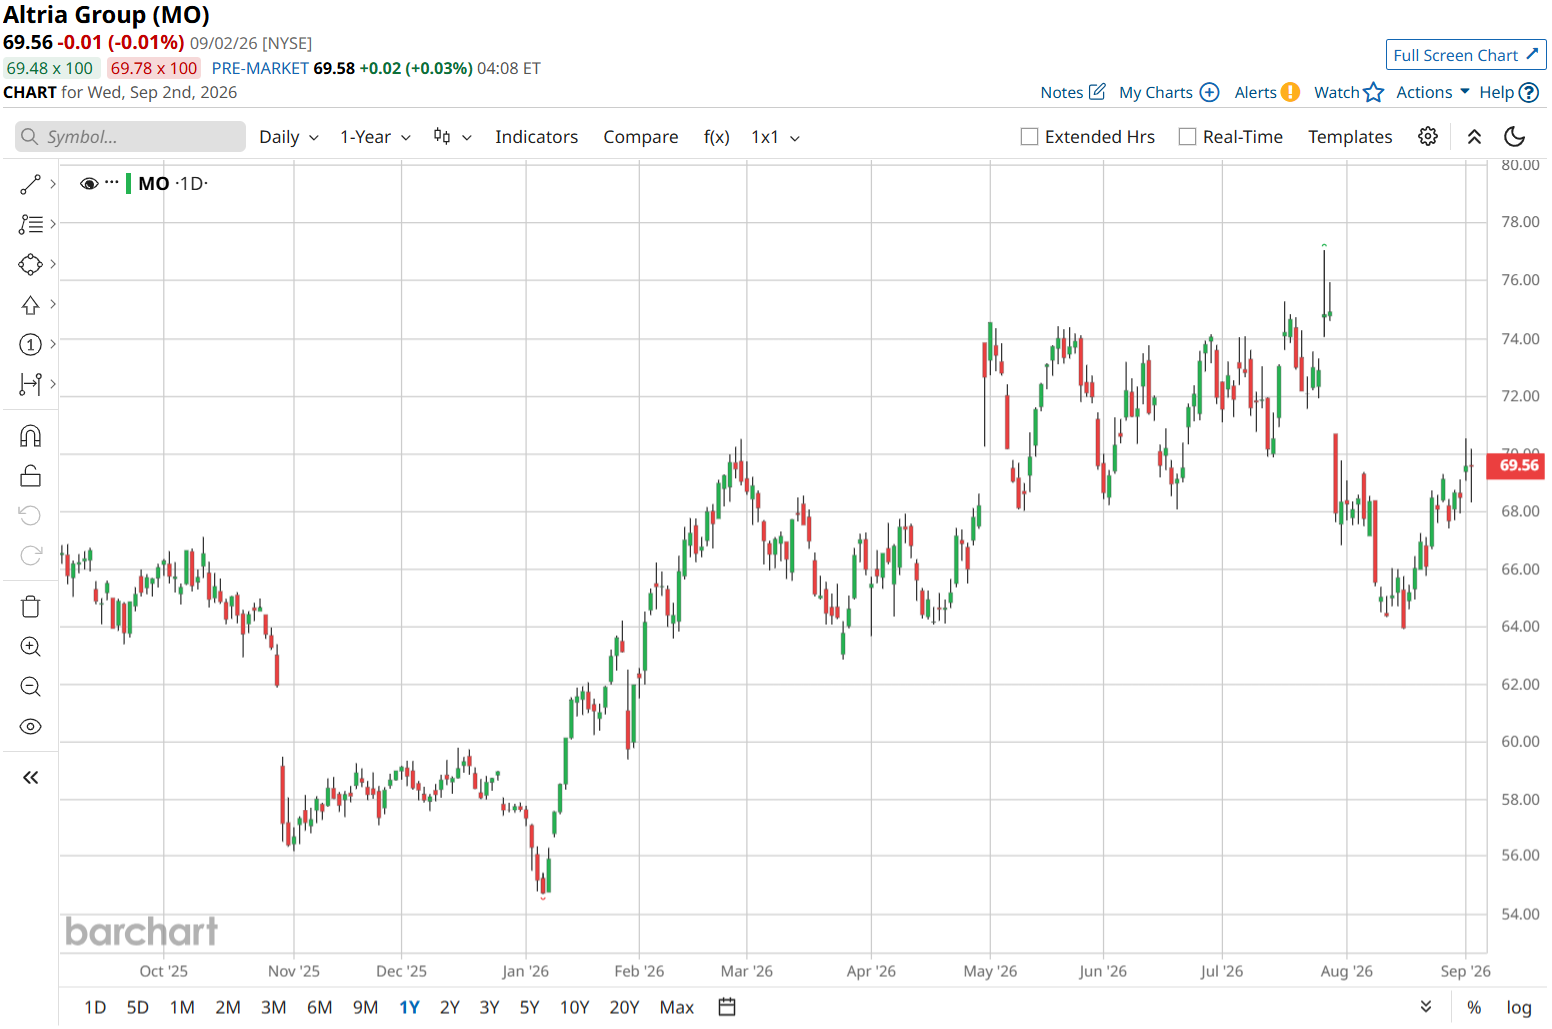
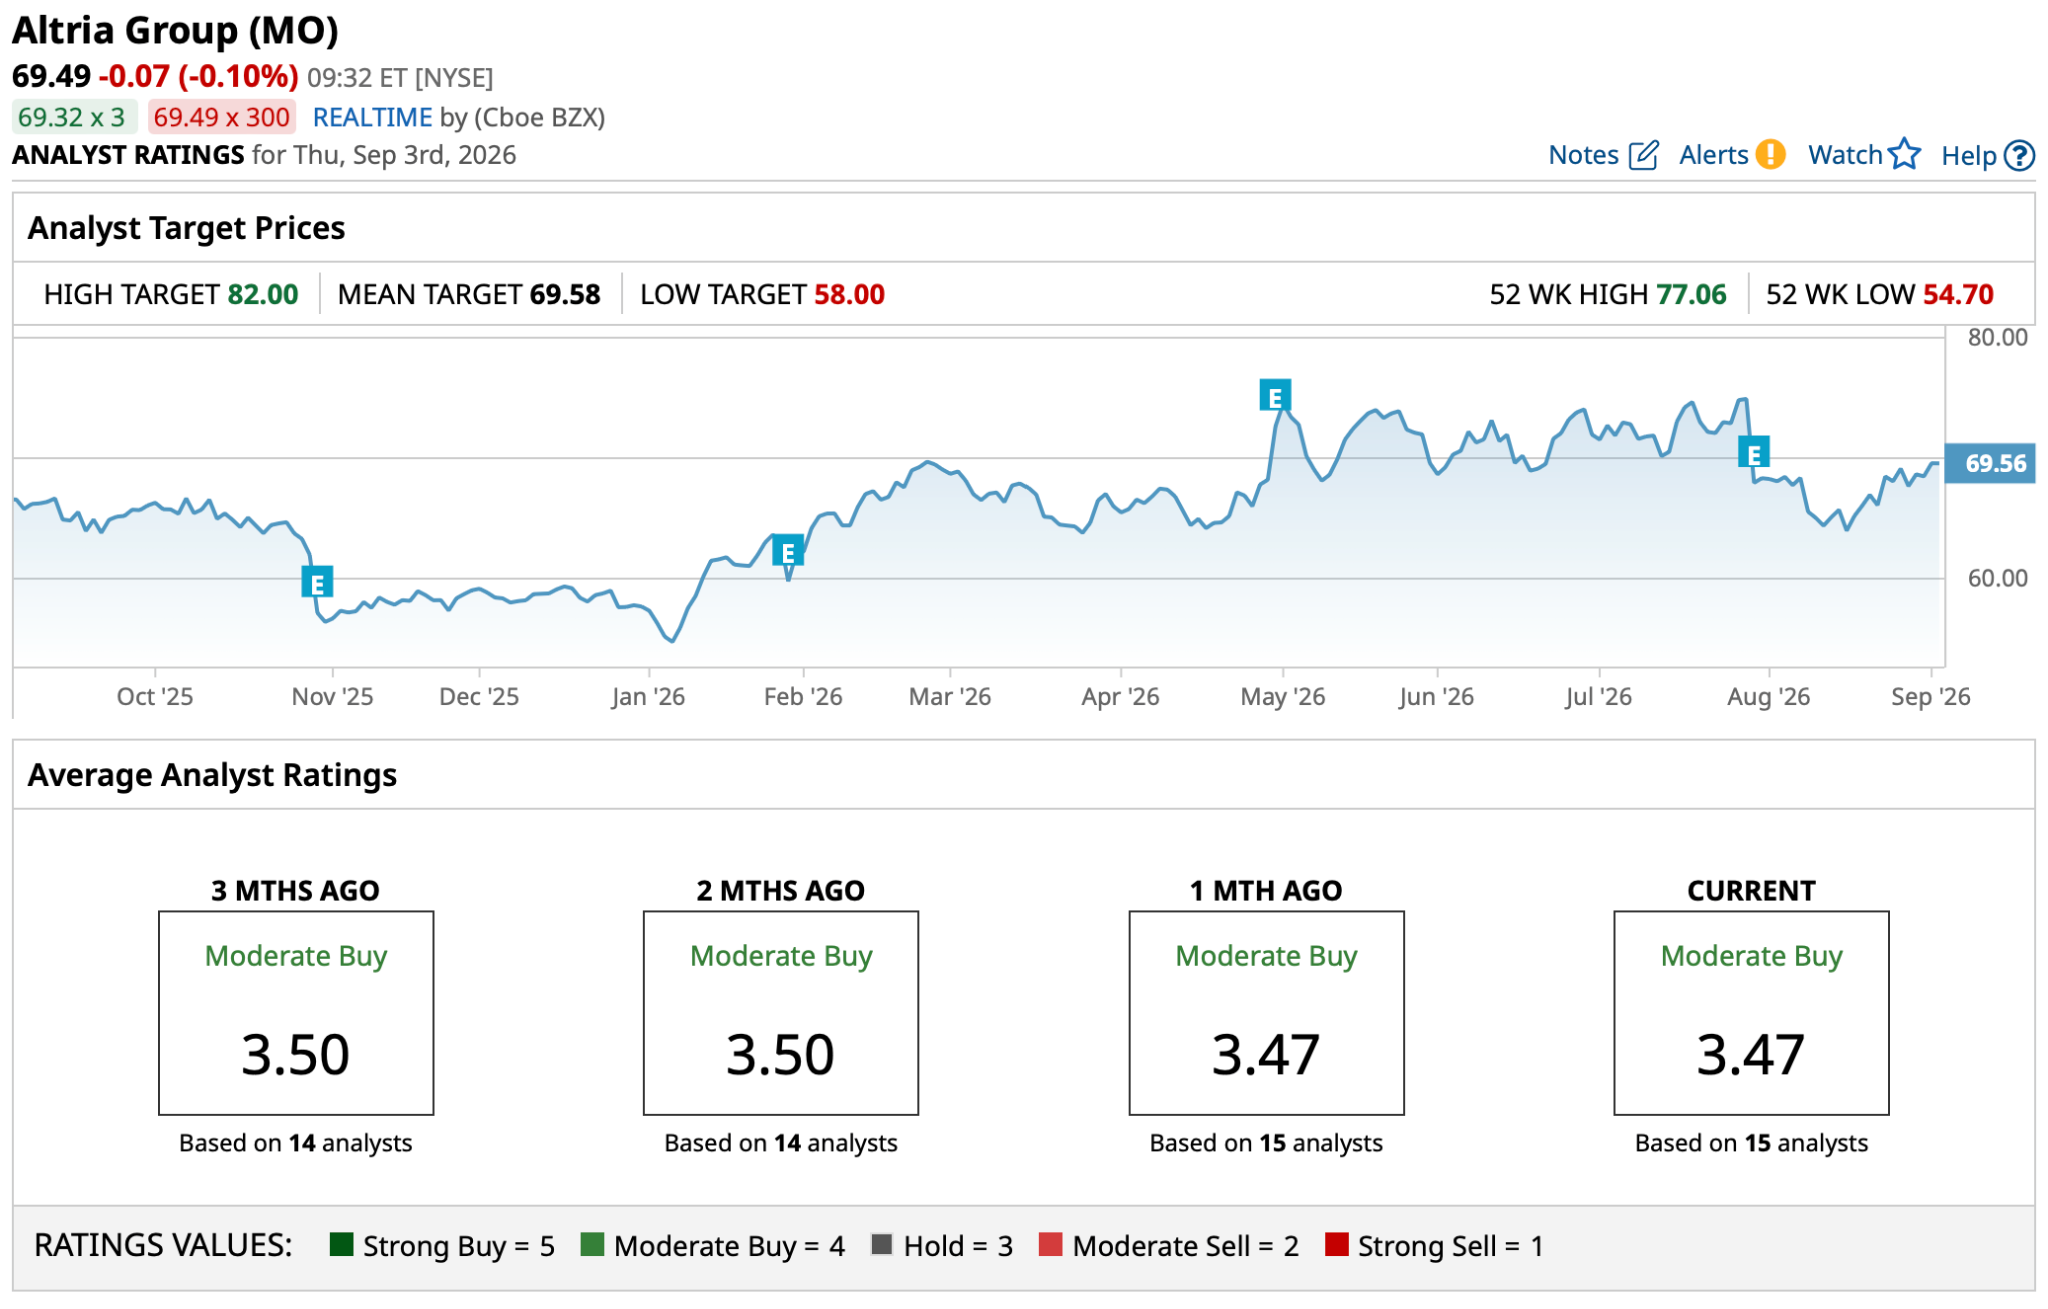
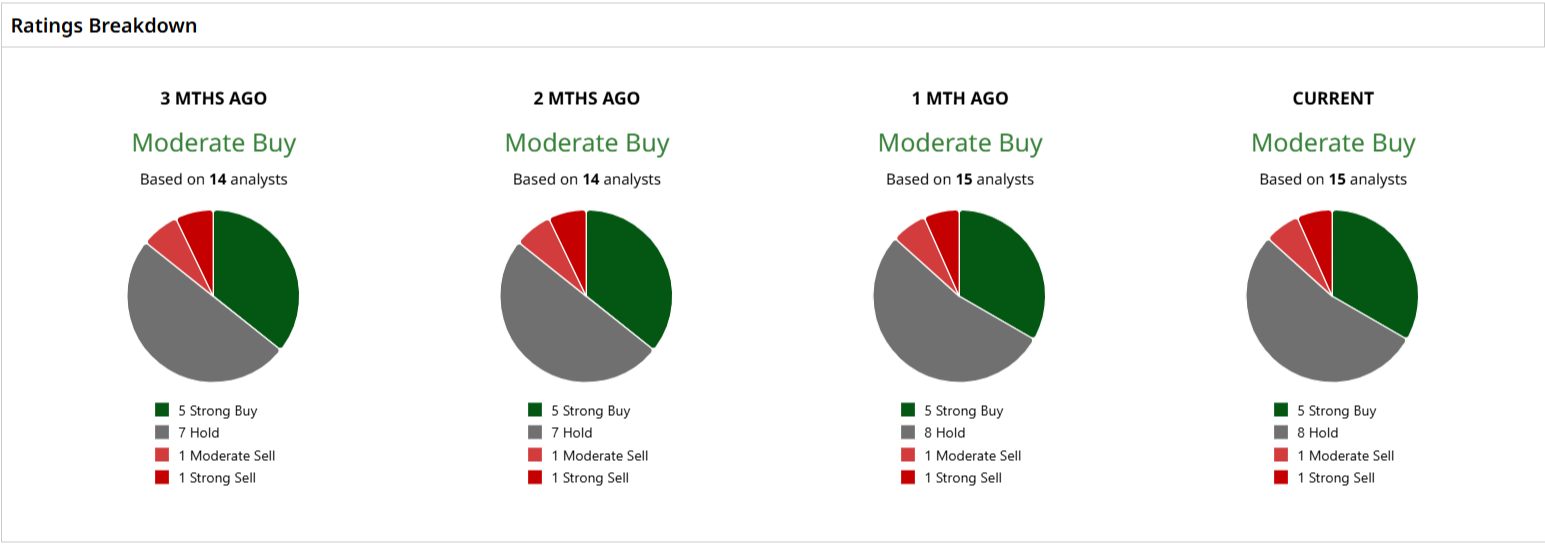
      Today’s insights and analysis to help you find the best stocks for income investing. Altria Is Spending More on Capex Than Any Other Consumer Staples Name. It’s a Calculated Sign of Strength. Dividend Investor for September 07, 2026 With the second-quarter earnings season mostly over, investors are watching how consumer staples companies are spending their cash. Capital expenditures serve as one useful clue, and Altria (MO) stands out. The tobacco company reportedly leads all consumer staples stocks with a 100% increase in capital expenditures, ahead of Kimberly-Clark (KMB) at 96.49% and Darling Ingredients (DAR) at 71.17%. In its Q2 report on July 30, Altria raised its 2026 capex forecast to between $375 million and $450 million, from a prior range of $300 million to $375 million. The company tied the increase to its manufacturing-consolidation plans. That makes the higher spending worth watching, especially after Altria’s Q2 results sent MO stock down 9.3% in one session. Adjusted EPS still rose almost 3% year-over-year (YOY) to $1.48, while the company returned nearly $3.9 billion to shareholders through dividends and buybacks in the first half of 2026.  Is Altria spending from a position of strength? Or is protecting its cash flow becoming more expensive? Let’s take a closer look. The Numbers Behind the Investment Altria makes most of its money from U.S. cigarettes, although it is also investing in smoke-free nicotine products. MO stock has gained more than 3% over the past 52 weeks and more than 19% year-to-date (YTD). www.barchart.com Even after that run, MO stock trades at 12.2 times forward earnings, which is below the consumer staples sector average of roughly 15 times. The dividend is still a major reason investors own Altria. Its annual dividend is $4.24 per share, giving the stock a 6.1% yield. The latest quarterly payment was $1.06 per share, paid on July 10. Altria has raised its dividend for 57-straight years and pays it every quarter. Still, the 76.15% forward payout ratio means a large share of earnings already goes to the dividend, leaving less room when spending needs rise. Q2 results showed why Altria can still afford to invest. Revenue rose 0.1% year-over-year (YOY) to $6.11 billion, while revenue excluding excise taxes increased 1.2% to $5.36 billion. Reported diluted EPS fell 2.8% to $1.37, but adjusted EPS rose 2.8% to $1.48. Meanwhile, first-half adjusted EPS climbed 4.9% to $2.80. Smokeable-products revenue excluding excise taxes rose 2% to $4.66 billion during Q2, while adjusted operating income increased 2.4% to about $3.02 billion. Altria’s 64.8% margin helped offset a 3.2% drop in domestic cigarette shipments, or about 4.5% after adjusting for inventory. Altria paid $1.8 billion in dividends during the quarter and $3.6 billion in the first half of the year. The company also spent $335 million on buybacks, bringing total first-half shareholder returns to nearly $3.9 billion. At the same time, the company raised its 2026 capex forecast to $375 million to $450 million from $300 million to $375 million, mainly to consolidate U.S. Smokeless Tobacco Company (USSTC) manufacturing operations. Management still expects 2026 adjusted EPS of $5.61 to $5.72, up 3.5% to 5.5% YOY. Why Altria’s Capex Surge Signals Strength Altria has seen its capex rise faster than any other consumer staples stock. Data shows capex rose about 100% YOY. Still, the actual dollar amount is not huge for a company of Altria’s size. Capital expenditures increased 52% to $216 million in 2025 from $142 million in 2024. For 2026, management first guided for $300 million to $375 million in capex, then lifted that range to $375 million to $450 million. The spending has a clear purpose. Altria is putting money into contract manufacturing with Philip Morris International (PM), as well as import and export operations. The arrangement could help Altria capture duty-drawback benefits and support future product plans. The bigger reason for the higher capital expenditures, though, is USSTC’s plan to move work from its older Nashville, Tennessee facility to a new site at its Hopkinsville, Kentucky campus. The company expects Nashville production to end in early 2028. By putting more processing, production, and packaging in one place, Altria aims to cut costs and simplify operations. For now, this looks more like planned spending than a sign of trouble. Altria still produces roughly $9 billion in annual operating cash flow and continues to return billions of dollars through dividends and buybacks. The real test is whether the spending leads to lower costs and stronger growth in oral tobacco over time. Analysts Debate Altria’s Upside Altria is set to report Q3 results before the market opens on Oct. 29. Analysts expect earnings of $1.50 per share for the September quarter, up more than 3% from $1.45 a year ago. For full-year 2026, the average estimate is $5.67 per share, which would be roughly 5% higher than the $5.42 reported in fiscal 2025. UBS analyst Faham Baig is bullish on MO stock. On July 7, Baig kept a “Buy” rating on Altria and raised his price target to $79 from $76. Barclays sees less upside, however; analyst Pallav Mittal kept an “Underweight” rating while lowered the price target to $58 from $64 on Aug. 11. Overall, Altria stock has a consensus “Moderate Buy” rating on Wall Street. The average price target of $69.58 points to potential upside of just 1% from current levels. www.barchart.comwww.barchart.com Conclusion Altria’s higher capex looks more like a calculated sign of strength than a warning, at least for now. The investment is targeted at modernizing smokeless-tobacco manufacturing rather than a broad, speculative spending push, while the core cigarette business still produces the margins and cash flow needed to fund dividends, buybacks, and growth initiatives. The caution is that cigarette volumes continue to decline and next-generation nicotine competition is intensifying, so the payoff must show up in better efficiency and smoke-free growth. With MO stock near analysts’ average target, shares will most likely trade sideways in the near term, with dividend income providing the main support. Enjoying this content? Want more? Explore all of Barchart’s FREE newsletters     Like what you are reading? Check out the full family of Barchart Newsletters, designed for every type of investor and trader. Psst.. Don’t forget to stay connected with Barchart across the social media platforms we ❤️ the most! Here’s where you can find us. Twitter Twitter YouTube LinkedIn Facebook
  • Two provinces seek a billion-dollar investment to make Canadian food easier to move, cheaper to access

    Food industry associations in British Columbia and Manitoba are seeking close-to $1-billion from government and private business to build regional food terminals as trade tensions with the U.S. continue to expose the risks of relying on north-south trade.

    BC Food & Beverage, which represents provincial food processors and manufacturers, is readying a proposal for a massive facility with an estimated cost of $700-million.

    The proposed space would be the first in the province and loosely modelled on the Ontario Food Terminal, the only one of its kind, which distributes two billion pounds of food each year across Canada. The western anchor would be part of a network of terminals that move food along interprovincial routes already running from the port to Alberta, the Prairies and Northern Canada.

    Manitoba’s industry association is looking to build its own terminal with a price tag between approximately $150-million and $200-million.

    “What Donald Trump has done is, he’s made us realize, ‘Wow, we’re vulnerable – we have a lot of eggs in one basket,’” said Michael Mikulak, executive director of Food & Beverage Manitoba.

    Here’s how Canada’s countertariffs could hit your wallet

    Food terminals, which function as independent wholesale food marketplaces, offer a more efficient way for Canadian supply to meet Canadian demand, he said.

    By concentrating multiple producers at one facility, these operations can cut the cost of shipping product orders to stores.

    Both the B.C. and Manitoba proposals are largely in response to Ottawa’s National Food Security Strategy, launched in June. It pledged $3-billion over 10 years to expand domestic processing and production, make supply chains more efficient and improve grocery competition. The strategy was developed amid rising food costs and trade tensions with the U.S. that threaten decades-old supply routes.

    “The food industry is more than just feeding Canadians – it’s an economic engine with still so much room to grow,” said James Donaldson, chief executive officer at BC Food & Beverage. “To see that level of commitment was really exciting.”

    Opinion: Canada’s new Food Security Strategy won’t end food insecurity

    The B.C. concept, which has been dubbed “the Pacific Gateway,” is even more ambitious than its Ontario counterpart. With the Port of Vancouver and Vancouver International Airport already moving mass quantities of food to and from Asian markets, the B.C. terminal has an opportunity to become a regional export hub, according to Mr. Donaldson.

    More stories below advertisement

    00:00 / 00:06

    In an e-mail, Ron Lemaire, president of the Canadian Produce Marketing Association, said what’s particularly interesting about the B.C. proposal is that “it thinks about food distribution as national infrastructure.” It positions British Columbia as a “western anchor” that serves communities across Western Canada while also leveraging international trade, he said.

    Though success will depend on industry buy-in, advocates of the projects say they’re not simply about creating more efficiencies for industry players, but about building out better food distribution to improve Canada’s food security.

    Today, they argue, countless inefficiencies make it hard for retailers, producers and processors to build up domestic supply chains.

    “We keep hearing about a truckload, container load, going out half full,” Mr. Donaldson said. “You’re bearing the whole cost of that truck on half the product.”

    Competition bureau launches study to examine how food supply chain affects grocery prices

    Currently, separate groups are responsible for securing produce, optimizing freight and repacking items that arrive damaged. “Having a centralized facility where all of those things can be consolidated is what we saw as an opportunity,” he said.

    Mr. Donaldson’s team is looking for funding through the National Food Security Strategy’s Food Link Fund, which pledged $1-billion to expand food terminals and start construction on two new ones by the end of 2028, along with provincial and private sources. They’ve already rallied commitment from provincial leaders.

    B.C. Agriculture and Food Minister Lana Popham said in a statement that her ministry is “excited” by the proposal’s potential to “unlock new, long-term food security and supply-chain resistance.”

    “This means more potential for fresher and more affordable food for British Columbians, and more jobs and economic growth for the agriculture and food sectors,” she said.

    Private investment, Mr. Donaldson said, could come from suppliers, distributors and companies that want to become anchor tenants. So far, he said, the response has been “green lights across the board.”

    Food & Beverage Manitoba, for its part, wants to offer full-blown food-processing capacity – such as washing and bagging potatoes – on top of aggregating and distributing food from an estimated 120,000-square-foot Winnipeg facility.

    “Canada is really good at shipping out commodities,” Mr. Mikulak said. “But why are we shipping out wheat when we could be shipping out pasta, bread, crackers?”

    Beyond helping to shore up domestic supply chains, food terminals help boost competition in the grocery sector by improving access for more players, said Gary Sands, senior vice-president with the Canadian Federation of Independent Grocers.

    Editorial: A missing link in the Liberals’ food chain plan

    Some of the country’s largest grocers, including Loblaw Cos. Ltd. L-T +1.39%increase
    and Empire Co. Ltd., EMP-A-T +0.25%increase
    also own distributors that their smaller competitors rely on for many of their goods. “If you’re buying goods directly, and not through a wholesaler in Ontario for produce, you’re getting more choice, and you’re containing your costs more,” Mr. Sands said, calling that an advantage for independents.

    Proponents also hope that food terminals can provide a buffer against rising grocery costs, as food-price spikes have outpaced general inflation for 18 straight months.

    “When we talk about affordability, we often focus on the consumer side. But for perishables, infrastructure performance is price policy,” Mr. Lemaire wrote. “When food moves efficiently, waste is reduced, costs are lowered, and consumers benefit.”

    Peter Chapman, founder of retail consulting firm SKUFood, said the success of food terminals will depend on real commitments from both the buying side – retailers, restaurants and others – and the producers who sell goods to commit to doing business there. They will also require sufficient volumes of products.

    “It’s not just building it,” he said. “They really need to have the conversations with the suppliers and the buyers, and are people really going to come together to support it?”

  • Calendar: Sept 7 – Sept 11, 2026

    Monday September 7

    Canadian and U.S. markets closed (Labour Day)

    China’s foreign reserves and trade surplus

    Euro zone’s real GDP

    Germany’s industrial production


    Tuesday September 8

    China’s CPI, PPI, aggregate yuan financing and new yuan loans

    Japan’s real cash earnings, banking lending and GDP

    Germany’s trade surplus

    (6 a.m. ET) U.S. NFIB Small Business Economic Trends Survey for August.

    (3 p.m. ET) U.S. consumer credit for July.

    Also: Canada and U.S. Manpower Survey for Q4

    Earnings include: Caseys General Stores Inc.


    Wednesday September 9

    Japan’s machine tool orders

    (8:15 a.m. ET) U.S. ADP Employment (four-week average) for Aug. 22.

    (10 a.m. ET) U.S. quarterly services survey for Q2.

    Earnings include: D2L Inc.; Haivision Systems Inc.; North West Co. Inc.; Transcontinental Inc.


    Thursday September 10

    ECB’s monetary policy meeting

    Germany’s CPI

    (8:30 a.m. ET) U.S. initial jobless claims for week of Sept. 5. The Street expects 208,000, up 2,000 from the previous week.

    (8:30 a.m. ET) U.S. PPI final demand for August. Consensus is a month-over-month rise of 0.4 per cent.

    (10 a.m. ET) U.S. existing home sales for August.

    (10 a.m. ET) U.S. wholesale trade for July.

    Earnings include: Adobe Systems Inc.; Descartes Systems Group Inc.; Empire Co. Ltd.; Groupe Dynamite Inc.; Macy’s Inc.; Tecsys Inc.


    Friday September 11

    (8:30 a.m. ET) Canada’s National Balance Sheet and Financial Flow Accounts (Q2).

    (8:30 a.m. ET) U.S. CPI for August. The Street expects a rise of 0.4 per cent month-over-month and 3.4 per cent year-over-year.

    (10 a.m. ET) U.S. University of Michigan’s consumer sentiment survey for September.

    (2 p.m. ET) U.S. budget balance for August.

    Earnings include: Kroger Co.

  • U.S. nonfarm payrolls surge in August; unemployment rate holds at 4.1%

    U.S. job growth accelerated sharply in August while the unemployment rate held steady at 4.1 per cent, pointing to a still stable labour market and keeping ​an interest rate hike from the ‌Federal Reserve this month on the table.

    Nonfarm payrolls surged by 162,000 jobs last month after an upwardly revised rise of 21,000 in July, the Labor Department’s Bureau of Labor Statistics said in its closely watched employment ‌report on ​Friday. Economists polled ‌by Reuters had forecast payrolls would increase by 56,000 after a ​previously reported drop of 23,000 in July.

    Estimates ⁠ranged from as low as a loss of 25,000 ⁠jobs to as high as a gain of 121,000. Labour market momentum ​had decelerated after surging in the spring, partly blamed on the oil price shock and supply chain strains from the U.S.-led war with Iran.

    Ahead of the employment report, financial markets had dialed back rate hike expectations after Fed ⁠Governor Christopher Waller said on Thursday that he was inclined to argue in favour of keeping rates steady this month if upcoming data confirmed inflation pressures were cooling off. Financial markets saw a roughly 52 per cent chance ⁠of a rate hike at the Fed’s ​September 15-16 meeting, down from 63.2 per cent on Wednesday, according to CME’s FedWatch ⁠tool.

    Concerns about inflation and lack of forward guidance from the Fed have helped to ‌boost U.S. Treasury yields, which economists see as a problem for the ​central bank.

    Rising yields drove the 30-year fixed mortgage rate to more than a one-year high of 6.71 per cent this week, data from mortgage finance agency Freddie Mac showed on Thursday, ​which could further undermine a struggling housing market.

  • Canada’s economy loses 41,700 jobs in August, unemployment steady at 6.4%

    The previously hot labour market stalled out to end the summer with a loss of 42,000 jobs in August, Statistics Canada said Friday.

    The unemployment rate held steady at 6.4 per cent last month, the agency said.

    August’s losses fell short of economists’ expectations for a gain of 15,000 positions.

    It puts an end to a hot streak for the labour market that saw 181,000 jobs added from April through July. The unemployment rate had dropped by half a percentage point over the previous three months.

    StatCan said there was little change in the private sector and self-employment in August, but the public sector shed 20,000 positions in its third straight month of losses.

    The business, building and other support services sector led declines, followed by public administration, natural resources and utilities.

    Andrew Hencic, senior economist at TD Bank, suggested in a note to clients Friday that one month of soft data should not define the labour market. Steadiness in the unemployment rate is more important than the headline job losses, he argued.

    “Although disappointing, given the noisy nature of the data a step backwards is not a major surprise after a string of hot reports,” Hencic said.

    The manufacturing industry has been hit hard by U.S. tariffs but the sector proved to be a surprise pocket of strength in August with a gain of 22,000 jobs.

    August’s job figures only partially capture impacts from a new wave of 50 per cent tariffs on about $28 billion worth of Canadian goods applied by the United States mid-month.

    StatCan said the layoff rate – the proportion of people who were unemployed as the result of a layoff between July and August – was 0.8 per cent in August. That rate stood at one per cent a year ago and averaged 0.9 per cent for the same months in the three years before the COVID-19 pandemic.

    For industries reliant on export demand from the United States, StatCan said the layoff rate was marginally higher over the past 12 months when compared with other sectors.

    The annual increase in average hourly wages cooled to two per cent in August, the agency said, down from 2.8 per cent in July and 3.3 per cent in June. The last time the annual wage increase was that low was November 2017.

    Young workers aged 15 to 24 faced 19,000 job losses in August. Despite a tough end to the season, StatCan said this past summer jobs market was statistically better for youth than last year.

    On average, the jobless rate for students returning to school in the fall stood at 15.9 per cent from May to August this year – two percentage points lower than the same period in 2025.

    The Bank of Canada held its benchmark interest rate steady at 2.25 per cent earlier this week.

    The central bank signalled at the time that new U.S. tariffs were clouding the outlook for the economy. Governor Tiff Macklem said the economy was showing signs of a rebound heading into the re-escalating trade war, which puts Canada on more solid footing to handle the new duties.

    At the same time, he said the central bank was concerned about lingering risks to inflation tied to the ongoing war in Iran.

    CIBC senior economist Andrew Grantham said in a note to clients that the weak August jobs figures reinforce the case that growth is set to slow in the third quarter, adding to similarly soft data prints for exports and gross domestic product.

    “With heightened uncertainty regarding U.S. trade, we continue to think that the Bank of Canada will remain on hold even after policymakers expressed greater concern over the inflation outlook earlier this week,” Grantham said.

  • Bank of Canada holds benchmark rate steady amid escalating trade war with U.S

    The Bank of Canada held its benchmark interest rate steady for the seventh consecutive time as the escalating trade war with the United States risks slowing economic growth while pushing up consumer prices.
     
    As widely expected, the central bank’s governing council kept the policy rate at 2.25 per cent.
     
    Governor Tiff Macklem and his team have kept monetary policy in cruise control since last October, as the bank navigated a tricky combination of rising global energy prices – the result of the war in the Middle East – and weak domestic growth tied in large part to the trade war with the United States.
     
    The breakdown in trade negotiations with Washington last month, another wave of American tariffs, and Ottawa’s threat to retaliate has only added to the uncertainty about the trajectory of the Canadian economy.
     
    New U.S. tariffs on around $28-billion worth of Canadian goods will weigh on exports, jobs and investment in Canada – all of which should put downward pressure on inflation over time. At the same time, Canada’s “dollar-for-dollar” retaliatory tariffs on American imports – scheduled to come into force on Sept. 8 – will push up prices in Canada.