Author: Consultant

  • RBC beats profit expectations, raises dividend and plans to buy back shares

    Royal Bank of Canada RY-T +0.02%increase posted higher second-quarter profit that beat analysts’ estimates, boosted by a surge in capital markets earnings and lower provisions for sour loans.

    RBC’s profit climbed 25 per cent to $5.5-billion, or $3.85 per share, in the three months that ended April 30.

    Adjusted to exclude certain items, the bank said it earned $3.90 per share. That topped the $3.77 per share analysts expected, according to Bloomberg data.

    “In a world that’s constantly changing and becoming more complex, our commitment to delivering trusted advice and helping clients navigate risk continues to produce exceptional outcomes,” RBC chief executive officer Dave McKay said in a statement.

    The bank raised its quarterly dividend by 12 cents to $1.76 per share. The lender also said it plans to repurchase 45 million of its shares, representing about 3 per cent of its common stock.

    RBC has been focused on bolstering its profitability. During fourth-quarter earnings in December, the bank raised its return on equity (ROE) target to 17 per cent or more after surpassing the 16-per-cent goal the bank set at its investor day last year.

    In the quarter, the bank posted higher ROE at 17.2 per cent.

    RBC is the fifth major Canadian bank to report earnings for the fiscal second quarter. Bank of Montreal BMO-T -0.88%decrease, Bank of Nova Scotia BNS-T -1.45%decrease and National Bank of Canada NA-T +0.32%increase reported earnings on Wednesday. Toronto-Dominion Bank TD-T +0.02%increase and Canadian Imperial Bank of Commerce CM-T -1.70%decrease also posted earnings on Thursday.

    RBC set aside $912-million in provisions for credit losses – the funds banks set aside to cover loans that may default. That was lower than analysts anticipated, and included $899-million against loans the bank believes may not be repaid, based on models that use economic forecasting to predict future losses.

    In the same quarter last year, RBC set aside $1.4-billion in provisions as it built up reserves ahead of a potential economic downturn.

    Profit from personal banking was $1.87-billion, up 17 per cent from a year earlier, on higher net interest income and lower provisions. Loan balances were up 4 per cent year over year while deposits decreased 1 per cent.

    The commercial banking unit posted profit of $854-million, up 43 per cent from a year earlier, largely driven by lower provisions.

    Capital markets posted earnings of $1.48-billion, an increase of 23 per cent from a year earlier, driven by higher revenue in global markets and corporate and investment banking.

    The wealth management division generated $1.19-billion of profit, up 28 per cent on higher fee-based client assets and net interest income.

    Profit from insurance was up 3 per cent at $218-million. RBC is restructuring the unit’s leadership as insurance head Jennifer Publicover is leaving the bank effective June 1.
  • Carney picks Swedish early-warning aircraft tech over U.S. bidders

    Prime Minister Mark Carney said Canada has entered into negotiations to buy Swedish-made Saab early-warning aircraft technology, picking a non-U.S. supplier as he makes good on a promise to reduce spending on American military gear.
     
    Mr. Carney announced the selection at the annual CANSEC defence trade show in Ottawa Wednesday.
     
    He said Canada will proceed with the Swedish GlobalEye system, made by Saab. Other contenders were the Aeris X by L3Harris and the E-7 Wedgetail by Boeing.
     
    The GlobalEye early warning system will be installed on Global 6500 jets made by Bombardier in Canada.
  • Bullish potential on Alimentation Couche-Tard

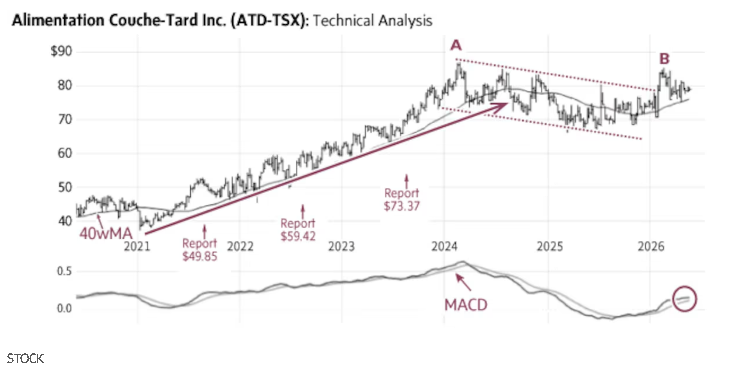
    Alimentation Couche-Tard (ATD-T, Monday’s close $79.05) was in a major uptrend for more than four years, trading above a rising trendline (solid line) and its rising 40-week moving average (40wMA). We recommended the stock on numerous occasions during this period.

    Following the February, 2024, high of $87.27 (A), the stock began trading within a slightly declining parallel channel (dotted lines), while the 40wMA also trended lower. More recently, the 40wMA started to curl upward, and the stock advanced above the upper boundary of the channel (B). Together, these developments signaled the end of the downtrend and the start of a new uptrend toward higher targets. A decisive rise above $86-$87 would confirm the breakout.

    There is good support near $76; however, only a sustained decline below the 40wMA (currently near $74) would be negative.

    Point & Figure measurements provide targets of $89 and $99. Higher targets are visible.

    Monica Rizk is the Senior Technical Analyst

  • National Bank reports Q2 profit up from year ago, raises dividend

    National Bank of Canada reported a second-quarter profit of $1.23 billion, up from $896 million a year ago, and raised its dividend.

    The Montreal-based bank says it will now pay a quarterly dividend of $1.32 per share, an increase of eight cents per share.

    National Bank says its second-quarter profit amounted to $3.06 per diluted share for the quarter ended April 30 compared with $2.17 per diluted share a year ago.

    Revenue for the quarter totalled $3.91 billion, up from $3.65 billion in the same quarter last year, while the bank’s provision for credit losses amounted to $233 million, down from $545 million a year ago.

    On an adjusted basis, National Bank says it earned $3.23 per diluted share in its latest quarter, up from an adjusted profit of $2.85 per diluted share a year ago.

    Analysts on average had expected an adjusted profit of $3.13 per share, according to LSEG Data & Analytics.

    This report by The Canadian Press was first published May 27, 2026.

    Companies in this story: (TSX:NA)

  • Scotiabank tops second-quarter profit estimates, raises dividend

    Bank of Nova Scotia BNS-T reported higher second-quarter profit that beat analysts’ estimates on a boost from its Canadian banking unit as the lender seeks to bolster its profitability. 

    Scotiabank earned $2.6-billion, or $2.00 per share, in the three months that ended April 30. That compared with $2-billion, or $1.48 per share, in the same quarter last year.

    Adjusted to exclude certain items, the bank said it earned $2.02 per share. That edged out the $1.93 per share analysts expected, according to data from Bloomberg.

    “The Bank delivered another strong quarter as we continue to execute on our strategy, with strong revenue growth coupled with expanding margins and another quarter of positive operating leverage,” Scotiabank chief executive officer Scott Thomson said in a statement.

    Mr. Thomson has said he expects double-digit earnings per share growth in its domestic banking business this year. The unit is key to Scotiabank’s plan to boost its profitability.

    Last quarter, Scotiabank said it expects to hit its target of 14-per-cent return on equity in 2027, a year earlier than expected.

    In the second quarter, Scotiabank posted an adjusted return on equity of 13.2 per cent.

    While the bank’s turnaround strategy is focused on building its Canadian business, it also hinges on improving its international unit and growing its capital markets division in the United States.

    The bank raised its quarterly dividend by 4 cents to $1.14 per share.

    Scotiabank is the first major Canadian bank to report earnings for the fiscal second quarter. Bank of Montreal and National Bank of Canada also report earnings on Wednesday. Royal Bank of Canada, Toronto-Dominion Bank and Canadian Imperial Bank of Commerce will post earnings on Thursday.

    losses – the funds banks set aside to cover loans that may default. That was higher than analysts anticipated, and included $1.1-billion against loans that the bank believes may not be repaid, based on models that use economic forecasting to predict future losses.

    In the same quarter last year, Scotiabank set aside $1.4-billion in provisions.

    Total revenue rose 8 per cent in the quarter to $9.8-billion. But expenses increased 2 per cent to $5.2-billion, which the bank said was driven by higher staffing, technology, advertising and business development costs.

    Profit from Canadian banking was $935-million, up 53 per cent from a year earlier on higher revenues and lower provision for credit losses on performing loans. Loan balances rose slightly by 3 per cent year over year.

    Profit from the bank’s international division rose 1 per cent to $701-million, driven by lower non-interest expenses and income taxes, partially offset by lower net interest income, lower non-interest income and higher provision for credit losses.

    The global wealth management division generated $474-million of profit, up 19 per cent, driven by higher mutual fund fees, brokerage revenues and net interest income from the Canadian wealth business.

    Capital markets profit rose 11 per cent to $457-million, driven by higher non-interest income and net interest income, which was partially offset by higher non-interest expenses.

  • Bank of Montreal posts higher quarterly profit, hikes dividend

    Bank of Montreal BMO-T Financial reported a jump in second-quarter profit on Wednesday, lifted by robust performance in its capital markets business.

    Profit was $2.63-billion or $3.53 per share in the three months ended April 30, compared with $1.96-billion or $2.50 per share a year earlier.

    In a press release, BMO announced a quarterly dividend of $1.71 a share, a 4 cent increase.

    Worries about the impact of AI on software companies and the U.S.-Israel war against Iran rattled global financial markets in the reported quarter, triggering bouts of selloffs. Market volatility tends to be a boon for trading desks at large banks, as investors increasingly rejig portfolios to hedge against risks.

    Second-quarter profit at BMO’s capital markets unit rose 47 per cent from a year earlier to $638-million.

    Meanwhile, provisions for credit losses stood at $739-million in the reported quarter, compared with $1.05-billion a year earlier.

    Bank of Nova Scotia also reported a jump in second-quarter profit driven by strong performance in its capital markets business, as well as a 4-cent increase to its quarterly dividend.

    – with a report by Globe staff

  • Micron hits $1 trillion market cap for the first time as stock surges 18%

    Micron topped a $1 trillion market value for the first time on Tuesday as shares popped 18% on strong artificial intelligence demand for its memory chips.

    https://www.cnbc.com/2026/05/26/micron-stock-trillion-market-cap.html

  • Big banks poised to report strong profits as they buck economic uncertainty

    Canada’s biggest banks are set to post a round of resilient profits, bucking economic uncertainty and looming trade pressure ahead of talks to renew the USMCA.

    Analysts expect capital markets and wealth management activity to continue to bolster profits while loan growth slows and credit losses remain at elevated but manageable levels. Canadian bank stocks have surged 16 per cent this year on the optimism surrounding the sector’s ability to withstand economic uncertainty, outperforming the S&P/TSX Composite Index’s 8-per-cent climb.

    While banks are expected to post strong earnings results next week, investor reaction will depend on management’s expectations for the latter half of the year, Jefferies analyst John Aiken said in a note to clients.

    “Despite some serious potential headwinds, the Canadian banks continue to boast almost historically high valuations,” Mr. Aiken said. “We do not anticipate that the Q2 earnings will put this at risk, but with almost all the upside priced in, any questions surrounding promised robustness of the second half of 2026 could potentially upset the apple cart.”

    Canada’s six largest lenders report over the course of two days. “It’s going to be a banger,” Canadian Imperial Bank of Commerce analyst Paul Holden said in a note.

    On Wednesday, Bank of Nova Scotia BNS-T +0.68%increase, Bank of Montreal BMO-T +1.09%increase and National Bank of Canada NA-T +0.12%increase will report earnings for the three months ended April 30. Royal Bank of Canada RY-T +0.53%increase, Toronto-Dominion Bank TD-T +1.01%increase and Canadian Imperial Bank of Commerce CM-T +0.82%increase will post earnings on Thursday.

    Analysis: How Canada’s big banks turned mortgages into a nearly risk-free cash machine

    The lenders have benefited from “a positive halo effect” from a “resource-rich economy, pro-business Carney government,” Bank of America analyst Ebrahim H. Poonawala said in a note. Those factors encouraged investors to look past Canada’s challenged job and housing markets, as well as uncertainty over the coming renegotiation of the United States-Mexico-Canada Agreement, he added.

    In recent years, capital markets activity has propped up bank profits. Volatile equity markets have boosted trading activity, softening the impact of dampened loan demand from consumers and businesses.

    To beat analysts’ expectations, the banks will again have to rely on stronger profits from their capital markets units, National Bank of Canada analyst Gabriel Dechaine said in a note.

    “Barring a margin or credit surprise, the onus falls on the capital markets to deliver this outcome, which isn’t impossible considering several favourable market conditions,” Mr. Dechaine said.

    Scotiabank analyst Mike Rizvanovic said recent discussions with senior bankers suggest that the pipeline for mergers and acquisitions and equity and debt capital markets has been constructive, and elevated market volatility should continue to propel trading revenue.

    He expects capital markets earnings to grow by 13 per cent compared with the same quarter last year.

    Mr. Rizvanovic said loan volumes are likely to be “anemic,” weighed down by weakness in mortgages and real estate secured lending.

    Canada’s big banks could cut costs by closing more branches, analyst report says

    Analysts anticipate provisions for credit losses – the money banks set aside to cover loan defaults – to edge higher. The provisions are a closely watched measure of financial stress among consumers and businesses.

    Last quarter, delinquencies of more than 90 days rose across credit cards, unsecured lines of credit, mortgages and auto loans as more customers struggled to pay off their loans.

    Provisions for impaired loans – debt that is unlikely to be repaid – are expected to rise in the second quarter, offsetting lower provisions for loans that are still being repaid.

    “We are getting more cautious on credit losses given the weakness in Canadian unemployment, a soft housing market in the GTA, and industry credit metrics,” Mr. Holden said.

  • May 22/26 : Top 10 Price Decreases (Approx. Past 10 Trading Days)

    Based on recent TSX 60 performance trends, sector moves, and major market declines during the May 15 yield/inflation selloff, the following large-cap TSX names were among the weakest performers over roughly the past 10 trading days.

    RankStockApprox. 10-Day TrendPrimary Reason
    1Shopify Inc. (SHOP.TO)Sharp decline / volatileWeak guidance + rising bond yields + AI valuation concerns
    2Aritzia Inc. (ATZ.TO)Significant declineConsumer discretionary weakness + rate fears
    3Canadian Natural Resources Limited (CNQ.TO)WeaknessOil-price volatility + profit taking
    4Suncor Energy Inc. (SU.TO)Moderate declineOil volatility + inflation concerns
    5Magna International Inc. (MG.TO)High volatilityAuto-cycle fears + tariff concerns
    6Kinaxis Inc. (KXS.TO)WeaknessSaaS valuation compression + yield sensitivity
    7Canadian Tire Corporation Limited (CTC.A.TO)Sharp drop then reboundConsumer-spending fears
    8Barrick Mining Corporation (ABX.TO)DeclineGold-price weakness + falling metals
    9First Quantum Minerals Ltd. (FM.TO)Significant weaknessCopper-price decline
    10Open Text Corporation (OTEX.TO)Moderate declineTechnology-sector pressure

    Main Themes Behind the Declines

    1. Rising Bond Yields

    The May 15 bond-market selloff was one of the largest drivers of TSX weakness. Higher yields pressured:

    • technology,
    • consumer discretionary,
    • SaaS/software valuations.

    Most affected:

    • SHOP,
    • KXS,
    • OTEX.

    2. Consumer Weakness Fears

    Higher:

    • mortgage rates,
    • debt-servicing costs,
    • inflation expectations,
      hurt discretionary retail names.

    Most affected:

    • Aritzia,
    • Canadian Tire,
    • other TTCD-related stocks.

    3. Gold & Copper Price Declines

    Materials stocks weakened sharply as:

    • gold fell ~2.4%,
    • copper fell nearly 5%
      during the May 15 macro selloff.

    Most affected:

    • Barrick,
    • First Quantum,
    • mining shares broadly.

    4. Technology Valuation Compression

    TSX technology stocks sold off aggressively after:

    • rising yields,
    • AI valuation concerns,
    • risk-off sentiment.

    Shopify was particularly impacted after disappointing forward guidance earlier in May.


    Important Context

    Several of these stocks:

    • initially declined sharply,
      then
    • partially recovered after May 16 as:
      • yields stabilized,
      • oil fears eased,
      • markets rotated back into risk assets.

    So:
    some names remain down materially,
    while others recovered part of the decline.


    Sector Breakdown of Weakest Areas

    SectorMain Pressure
    TechnologyBond yields + AI valuation
    Consumer DiscretionaryConsumer-spending fears
    MaterialsGold/copper decline
    EnergyOil volatility
    IndustrialsTariff/recession concerns

    Key Takeaway

    The largest TSX 60 declines over the past ~10 trading days were mainly concentrated in:

    1. technology,
    2. consumer discretionary,
    3. mining/materials,
    4. cyclical industrials.

    The primary macro drivers were:

    • rising bond yields,
    • inflation fears,
    • commodity volatility,
    • valuation compression in growth stocks.