Author: Consultant

  • Linamar reports $221.4M in first quarter net earnings, up from $177.7M last year

    Linamar Corp. says its net earnings reached $221.4 million during the first quarter, up from $177.7 million the previous year.

    That amounted to diluted net earnings per share of $3.71, rising from $2.94 during the prior year quarter. 

    The Guelph, Ont.-based auto parts manufacturer says its sales totalled $2.94 billion during the three months ended March 31, rising year-over-year from $2.53 billion. 

    The company says its products continue to be compliant with the Canada-U.S.-Mexico Agreement on trade, meaning most of them are tariff-free into the U.S.

    However, Linamar says new tariffs that took effect in April will have more of an effect on its industrial segment but are not affecting its overall business outlook.   

    Last month, Linamar announced it was maintaining its full-year guidance for 2026 following recent changes to the U.S. tariff regime that imposed a 25 per cent levy on the full value of products made substantially of steel, aluminum or copper.  

    This report by The Canadian Press was first published May 6, 2026.    

  • MG.TO share price increase over past 10 days (May 8)

    Executive Summary

    • Magna International Inc. rose over the past ~10 trading days primarily due to:
      • stronger-than-expected Q1 earnings
      • margin improvement
      • cash-flow strength
      • optimism around restructuring/divestitures
    • The move was fundamentally earnings-driven, not speculative
    • Auto supplier sentiment improved broadly as tariff fears stabilized somewhat
    • Investors focused more on Magna’s adjusted profitability than the headline GAAP loss
    • The stock also benefited from rotation into cyclical/value industrial names

    Main Reasons for MG.TO Share Price Increase

    1) Q1 2026 Earnings Beat (largest driver)

    Magna reported:

    • Revenue: US$10.4B (+3% YoY)
    • Adjusted EPS: US$1.38 vs US$1.01 expected
    • Adjusted EBIT margin improved to 5.4% from 3.5%

    This was materially better than market expectations.

    Key takeaway:

    • Investors focused on operational improvement and margin recovery.

    2) Strong Margin Expansion

    The market liked:

    • operational efficiencies
    • cost controls
    • improved profitability despite lower global auto production

    Adjusted EBIT rose about 58% YoY.

    That matters because Magna had previously been criticized for:

    • weak margins
    • EV transition costs
    • slower vehicle production

    3) Positive Cash Flow Surprise

    Free cash flow improved sharply:

    • from approximately negative US$313M
    • to positive US$372M

    That reduced concerns around:

    • balance-sheet pressure
    • cyclical auto slowdown risk

    4) Asset Sales / Restructuring Optimism

    Magna announced divestitures of:

    • Lighting business
    • Rooftop Systems business

    Combined sales ≈ US$1.1B businesses.

    Investors interpreted this as:

    • simplification of business mix
    • focus on higher-margin operations
    • improved capital allocation

    5) Auto Sector Sentiment Improved

    Broader auto-parts sentiment stabilized due to:

    • resilient North American production
    • ongoing ADAS demand
    • improving Chinese EV contract outlook

    Magna specifically highlighted:

    • advanced driver-assistance systems (ADAS)
    • continued parts demand resilience

    Important Caveat (Why the rally was limited)

    The rally was restrained because Magna also:

    • lowered full-year sales guidance slightly
    • reported a GAAP net loss tied to divestiture charges
    • still faces tariff and EV-market uncertainty

    So the market reaction was:

    “better-than-feared,” not “everything is fixed.”


    Data & Evidence

    MetricResultMarket Interpretation
    RevenueUS$10.4BAbove estimates
    Adjusted EPSUS$1.38Significant beat
    EBIT Margin5.4%Strong improvement
    Free Cash Flow+US$372MMajor positive
    Sales GuidanceSlightly loweredMild negative
    Asset SalesUS$1.1B businessesStrategic positive

    Valuation Logic

    The stock increase was driven mainly by:

    • earnings revisions upward
    • reduced bankruptcy/cash-flow concerns
    • operational confidence recovery

    Not driven by:

    • EV hype
    • broad auto-sector euphoria
    • speculative momentum

    Risks Going Forward

    RiskImpact
    Global auto slowdownRevenue pressure
    EV demand uncertaintyProgram delays
    TariffsMargin compression
    North American production cutsLower volumes
    China competitionPricing pressure

    Bull / Base /Bear Scenarios

    Bull

    • Margins continue improving
    • ADAS demand accelerates
    • Stock rerates toward prior highs

    Base

    • Sideways recovery
    • Investors wait for consistent execution

    Bear

    • Auto production weakens
    • Tariffs increase costs
    • Recent gains reverse

    What Would Disprove Current Bullish Thesis

    • Margin expansion reverses
    • Free cash flow weakens materially
    • Auto OEM production cuts accelerate
    • Divestitures fail to improve returns

    Actionable Takeaways

    • The recent move in Magna International Inc. was primarily an earnings-quality rally
    • Investors rewarded:
      • higher margins
      • stronger cash flow
      • operational discipline
    • The stock remains cyclical and highly tied to:
      • North American auto production
      • EV adoption trends
      • tariff policy
  • TSX Consumer Discretionary Capped Index ($TTCD) performance for week ending may 8

    Executive Summary

    • S&P/TSX Capped Consumer Discretionary Index gained approximately +2.9% for the week ending May 8, 2026
    • Sector materially outperformed the broader S&P/TSX Composite Index (+0.6%)
    • Performance was driven mainly by:
      • Retail earnings strength
      • Consumer resilience
      • Select apparel and discount retail names
    • Major contributors included:
      • Aritzia Inc.
      • Dollarama Inc.
      • Restaurant Brands International Inc.
    • Volatility remained elevated due to oil-price pressure on consumers and concerns around economic slowing

    TTCD Performance — Week Ending May 8, 2026

    MetricResult
    Weekly Performance~+2.9%
    May 1 Close~395.96
    May 8 Close~399.05
    Weekly Range387.83 – 401.34
    Weekly TrendPositive / volatile

    S&P/TSX Capped Consumer Discretionary Index

    Based on historical data:

    • May 1 close: ~395.96
    • May 8 close: ~399.05
    • Intraworkweek rebound from May 4 weakness drove positive weekly performance

    Daily Performance Snapshot

    DateCloseDaily Move
    May 8399.05+1.10%
    May 7394.70-0.19%
    May 6395.46+0.39%
    May 5393.92+1.57%
    May 4387.83-2.05%

    Key Drivers

    1) Strong Retail Earnings

    The biggest catalyst was earnings:

    • Aritzia Inc. rose ~4.5% after beating estimates
    • Discount and branded retail continued outperforming

    This helped offset broader market volatility.


    2) Consumer Spending Resilience

    Despite:

    • higher oil prices
    • elevated borrowing costs
    • weaker employment data

    Canadian discretionary spending held up better than expected.

    Strong areas:

    • discount retail
    • apparel
    • restaurants

    3) Rate Expectations Stabilized

    Canadian employment weakness reduced concerns about additional rate hikes:

    • Lower yields supported consumer-sensitive equities
    • Improved sentiment toward retail and discretionary spending names

    4) Shopify Volatility Limited Gains

    The sector could have performed even better, but:

    • Shopify Inc. fell sharply (~15.6% on May 5) after soft guidance

    That weighed heavily on:

    • TSX technology
    • broader growth sentiment

    Importantly:

    • SHOP is not a core TTCD constituent, but sentiment spillover impacted consumer-growth names.

    Major TTCD Constituents (Representative)

    CompanyTheme
    Dollarama Inc.Defensive consumer
    Restaurant Brands International Inc.QSR resilience
    Magna International Inc.Auto cyclicals
    Aritzia Inc.Apparel momentum
    Gildan Activewear Inc.Consumer apparel

    Valuation Logic

    The weekly move was driven mainly by:

    • Earnings revisions
    • Lower-rate expectations
    • Rotation into selective consumer names

    Not driven by:

    • Broad economic optimism
    • Strong wage growth
    • Broad consumer acceleration

    Risks

    RiskImpact on TTCD
    Higher oil pricesReduces consumer spending power
    Weak employment trendRetail slowdown risk
    Sticky inflationMargin compression
    Consumer credit deteriorationDiscretionary demand risk
    Weak housing marketConsumer confidence pressure

    Bull / Base / Bear Outlook (Next 1–3 Months)

    Bull

    • Rates stabilize
    • Consumers remain resilient
    • TTCD retests highs near 405–410

    Base

    • Sideways volatile trading
    • Defensive retail outperforms cyclical retail

    Bear

    • Consumer spending weakens materially
    • TTCD retraces toward 380–385

    What Would Disprove Current Strength

    • Discount retailers begin missing earnings
    • Consumer credit losses rise materially
    • Oil prices remain elevated while retail margins weaken
    • Wage growth slows further

    Actionable Takeaways

    • TTCD outperformed the TSX this week largely due to:
      • apparel earnings
      • defensive retail
      • falling rate fears
    • Leadership remains selective, not broad
    • Watch:
      • Canadian employment data
      • oil prices
      • consumer spending trends
      • retail earnings revisions
  • Aritzia’s Q4 profit spikes 35% from last year

    Aritzia Inc.’s ATZ-T +2.89%increase
    latest quarter brought a 35 per cent jump in profit and a revenue increase that was almost just as high.

    The Vancouver-based retailer says its fourth quarter net income reached $134.3-million, up from $99.6-million a year earlier.

    That result for the period ended March 1 translated to $1.12 per diluted share, up from 84 cents per diluted share a year earlier.

    On an adjusted basis, Aritzia’s net income amounted to $138.2-million, rising from $98-million during the fourth quarter of last year.

    The company’s net revenue increased by about 33 per cent to $1.19-billion over the same period.

    The result comes as Aritzia continues to open more boutiques and push an app it recently launched.

  • Enbridge beats first-quarter profit estimates on gas transmission strength

    Enbridge Inc. ENB-T +0.22%increase reported first-quarter adjusted profit on Friday that surpassed analysts’ expectations as robust performance in its gas transmission and utility businesses offset softer results in its liquids pipelines segment.

    The pipeline operator is benefiting from rising demand for natural gas, utility infrastructure and power supply for data centers, allowing it to generate steady growth despite geopolitical tensions and commodity price volatility.

    The company said it added projects worth about $2-billion to its secured growth backlog during the quarter, including the Cone onshore wind project in Texas and expansions at the Tres Palacios and Dawn Hub storage facilities, as well as its Vector Pipeline system.

    Its secured growth backlog now stands at about $40-billion and is expected to be funded through its annual growth capital investment capacity of $10-billion to $11-billion.

    Enbridge acquired three utilities from U.S.-based Dominion Energy last year, expanding its gas distribution business.

    Adjusted core profit from gas distribution and storage business rose 6.8 per cent to $1.71-billion in the reported quarter, while gas transmission earnings increased 6.6 per cent to $1.57-billion.

    In its gas transmission segment, earnings benefited from stronger contracting across U.S. pipeline assets and higher revenues from the Aitken Creek and BC Pipeline systems.

    The gas distribution business was supported by higher regulated rates in Ontario, Utah and North Carolina, which partly helped cushion weaker liquids pipeline results, reflecting lower Mainline contributions.

    Enbridge’s Mainline system, which moves nearly half of the crude in the United States, saw quarterly adjusted core profit fall 13.2 per cent to $1.45-billion.

    The Calgary, Alberta-based company posted adjusted profit of 98 cents per share for the three months ended March 31, compared with analysts’ average estimate of 94 Canadian cents, according to data compiled by LSEG.

  • U.S. job growth beats expectations in April; unemployment rate steady at 4.3%

    U.S. employment increased more than expected in ⁠April while ​the unemployment rate held steady at 4.3 per cent, pointing to labor market resilience and reinforcing expectations that the Federal Reserve would leave interest rates unchanged for some time.

    Nonfarm payrolls increased by 115,000 jobs last month after an upwardly revised 185,000 ​advance in March, the Labor Department’s Bureau of Labor ‌Statistics said in its closely watched employment report on Friday. Economists polled by Reuters had forecast payrolls rising by 62,000 jobs after a previously reported 178,000 rebound in March.

    Estimates ranged from a loss of 15,000 jobs to a gain of 150,000 positions. Economists said it was ‌too early ​for the effects of the ‌U.S.-Israeli war with Iran to show. The conflict has raised gasoline and diesel ​prices as well as the cost of other commodities ⁠that are shipped through the Strait of Hormuz.

    Payrolls have been ⁠choppy since mid-2025, alternating between gains and losses. Economists have attributed the swings to an adjustment to ​the birth-and-death model, which the government uses to estimate how many jobs were gained or lost because of companies opening or closing in a given month. Some said a large turnover in firms created was making it hard for the BLS to estimate job creation associated with new ⁠companies.

    Weather, strikes and government job cuts as well as big changes to the labor force as President Donald Trump’s administration cracks down on illegal immigration have also added to volatility, they said. Economists recommended looking at the three-month moving average of payrolls.

    The labour market has been stuck in what economists and policymakers have called ⁠a “slow hire, slow fire” zone, a paralysis blamed on ​trade and immigration policies. Lower immigration and an aging population meant the economy needed ⁠to create between zero and 50,000 jobs per month to keep up with growth in the working-age population, economists ‌estimated.

    With the so-called breakeven level of job growth much lower than in prior years, ​they did not expect a surge in the unemployment rate, even if employment gains slowed considerably.

    The report bolstered financial market views that the Fed would leave interest rates unchanged into 2027. The U.S. central bank last week ​left its benchmark overnight interest rate in the 3.50-per-cent-3.75-per-cent range, citing inflation worries.

  • Canada’s unemployment rate rises to six-month high as full-time jobs drop

    Canada’s unemployment rate rose to a six-month high in April to 6.9 per cent as the economy lost a net of 17,700 jobs in March, Statistics Canada data showed on Friday, indicating a continued weakness in the labour market which has struggled in the face of U.S tariffs and trade uncertainty.

    Analysts polled by Reuters had predicted net job gains of 15,0000 and the unemployment rate of 6.7 per cent, almost mirroring the month of March when employment rose by 14,100 and jobless rate was the same.

    The Bank of Canada said in its Monetary Policy Report last month that indicators such as the employment rate, hours worked and job vacancies suggest slack, or underutilized capacity, in the labour market, although layoffs remain modest.

    The looming uncertainty around the future of the North American free trade deal and the knock-on impacts of the higher prices from the Iran war has continued to layer over the impact of U.S. tariff on the economy for over a year.

    The job losses were completely concentrated in full-time jobs which lost a net of 46,700 people, offset only by a gain of 29,000 jobs in the part-time sector.

    The net overall decline in employment over the first four months of 2026 was concentrated in full-time work, which fell by 111,000 between January and April, Statscan said.

    The goods-producing sector, which is the most exposed to U.S. tariffs, saw employment drop by 26,800 jobs in April, while the services sector, where four out of every five people are employed in Canada, reported a 9,100 job gain.

    Data indicate more people looking for work

    Average hourly wages of permanent employees, a metric closely tracked by the BoC to gauge rise in inflation expectations, grew 4.8 per cent from a year earlier, versus 5.1 per cent in March.

    The participation rate – the portion of the population over the age of 15 that is economically active – edged up to 65 per cent in April from 64.9 per cent in the prior month, Statscan said.

    A higher participation rate along with a higher unemployment rate indicates more people were searching for work in the economy.

    The unemployment rate among the core-aged work force of 25-54 year-olds as well as among the youth increased to 6 per cent and 14.3 per cent respectively.

    “For the Bank of Canada, evidence that slack within the labour market is, if anything, increasing rather than reducing, should limit the ability for the oil price shock to spread into wider inflationary pressure,” Andrew Grantham, a senior economist at CIBC Capital Markets, wrote in a note.

    CIBC expects Canada’s central bank to leave interest rates unchanged throughout 2026, he said. Money markets are pricing in one 25-basis-point rate hike in October, which would bring the Bank of Canada’s policy interest rate to 2.5 per cent.

    The Canadian dollar was trading down at 73.14 U.S. cents. Yields on the two-year government bonds were down 8.4 basis points to 2.501 per cent.
  • Thomson Reuters: Q1 Earnings Snapshot

     Thomson Reuters Corp. (TRI) on Tuesday reported first-quarter earnings of $459 million.

    On a per-share basis, the Toronto-based company said it had net income of $1.03. Earnings, adjusted for non-recurring costs and to account for discontinued operations, came to $1.23 per share.

    The results surpassed Wall Street expectations. The average estimate of three analysts surveyed by Zacks Investment Research was for earnings of $1.21 per share.

    The news and financial information company posted revenue of $2.09 billion in the period, also surpassing Street forecasts. Three analysts surveyed by Zacks expected $2.06 billion.

    _____

    This story was generated by Automated Insights (http://automatedinsights.com/ap) using data from Zacks Investment Research.

    Access a Zacks stock report on TRI at https://www.zacks.com/ap/TRI

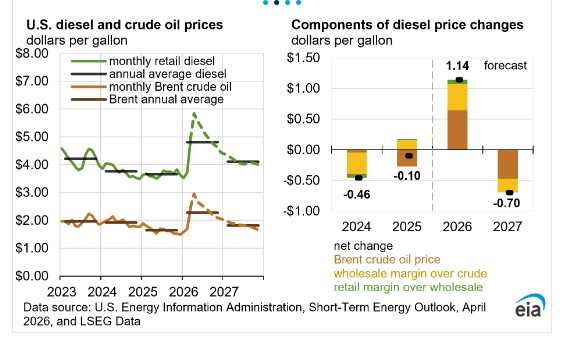
  • Crude Oil: Short-Term Energy Outlook

    https://www.eia.gov/outlooks/steo

    Crude Oil Prices Forecast next month

    Base case for next month: crude oil likely trades sideways to moderately higher, with WTI roughly US$58–65/bbl and Brent roughly US$62–70/bbl, assuming no major supply shock. EIA STEO and OPEC MOMR are the most useful baseline sources for near-term supply/demand balance [1] [4].

    Bull case: geopolitical disruption, OPEC+ restraint, or stronger demand could push prices above the range [4].

    Bear case: weaker global growth, higher inventories, or extra supply could pull prices lower [1].

    Takeaway: next month’s oil price risk is more event-driven than trend-driven; watch inventories, OPEC+ messaging, USD strength, and Middle East supply headlines.