The U.S. is imposing additional 50% tariffs on a range of Canadian goods, senior Trump administration officials said.
President Donald Trump signed three proclamations Monday targeting different sets of Canadian imports with the steep tariffs in response to alleged trade discrimination.
The tariffs, which fall under the rarely used Section 338 of the Tariff Act of 1930, are set to take effect 30 days after the signings, according to the officials.
Canada’s June CPI on Monday is the principal scheduled TSX event. It will influence Bank of Canada rate expectations, bond yields, the Canadian dollar and rate-sensitive sectors.
Canada’s May retail-sales report on Thursday will provide the clearest reading on household spending and consumer-sector demand.
The U.S.–Iran conflict and Strait of Hormuz disruption are the largest unscheduled risks, particularly for oil, inflation, gold and overall market volatility.
The European Central Bank decision Thursday and global PMI data Friday could alter global bond yields and expectations for economic growth.
Canadian manufacturing, wholesale and producer-price indicators Friday will provide secondary evidence on tariffs, industrial activity and input-cost inflation.
Canada manufacturing and wholesale advance indicators
Medium–high
Industrials, autos, railways, banks
Canada new-home and construction price indexes
Medium
REITs, banks, building-material companies
1. Monday, July 20
Canada Consumer Price Index—June 2026
Statistics Canada is scheduled to release June CPI at 8:30 a.m. Eastern. It will also publish building investment, mineral-production, credit and energy-transportation data.
Potential TSX impact
CPI outcome
Likely market response
Potential sector effect
Below expectations
Bond yields and CAD may decline; rate-cut expectations increase
Positive for REITs, utilities, technology and discretionary stocks
Near expectations
Limited market reaction
Stock-specific factors dominate
Above expectations
Bond yields and CAD may rise; rate cuts pushed back
Negative for REITs, utilities, technology and leveraged consumers
High CPI caused mainly by oil
Energy benefits, but broader valuations pressured
Mixed TSX result
The important distinction will be between headline CPI and underlying inflation. An oil-driven headline increase may support TSX energy shares but still reduce the probability of future Bank of Canada easing.
China loan prime rates
Markets will assess whether China changes its benchmark lending rates. A rate reduction or stronger stimulus signal would generally support expectations for Chinese industrial demand.
TSX sensitivity:
Positive: copper, base metals, fertilizers, forestry and industrial exporters
Negative surprise: materials and China-sensitive cyclicals
U.S.–Iran conflict and Strait of Hormuz
The conflict intensified over the weekend after further U.S. strikes and Iranian attacks on Gulf-region targets. Shipping through the Strait of Hormuz has been disrupted, while oil prices have risen as the risk to regional energy infrastructure increases.
TSX transmission
Conflict escalation→higher oil→higher energy earnings
but also:higher oil→higher inflation→higher bond yields→lower equity multiples
Potential beneficiaries
Potential pressure
CNQ, SU, IMO and other producers
Airlines and transportation
Pipelines, depending on volume expectations
Consumer discretionary
Gold shares during safe-haven buying
Utilities and REITs if yields rise
Canadian dollar
Manufacturing companies with energy-intensive costs
This is likely to be the dominant geopolitical variable for the entire week.
2. Tuesday, July 21
U.S. regional employment and wage data
The U.S. Bureau of Labor Statistics is scheduled to release state employment and unemployment figures, along with second-quarter usual weekly earnings, at 10:00 a.m. Eastern.
These are not normally major TSX-moving releases, but an unexpected wage acceleration could reinforce inflation concerns and push U.S. Treasury yields higher.
TSX impact
Higher yields: negative for technology, REITs, utilities and gold
Strong employment: positive for economically sensitive companies, but potentially negative for rate-cut expectations
Weak employment: initially negative for growth expectations but potentially supportive for bonds and rate-sensitive stocks
Canada transportation data
Statistics Canada is scheduled to release public-transit and airport-activity information.
The direct market impact should be limited, but the figures may provide background evidence for passenger demand, urban activity and transportation trends.
3. Wednesday, July 22
U.S. Treasury bond auction
The U.S. Treasury is expected to auction US$13 billion of 20-year bonds Wednesday. Weak demand could lift long-term yields; strong demand could lower them.
Why it matters to the TSX
Long-duration equities are particularly sensitive to Treasury yields:
Shopify and other technology shares
Utilities
REITs
High-valuation consumer companies
Gold and precious-metal equities
A poorly received auction could pressure these sectors even without any change in company fundamentals.
U.S. petroleum inventories
Weekly EIA petroleum data will be watched closely because the normal inventory signal is currently interacting with Middle East supply disruption.
Inventory result
Likely implication
Large crude draw
Additional support for WTI and TSX energy
Large build
Could offset part of the geopolitical premium
Falling gasoline demand
Negative for refiners and demand expectations
Product shortages
Supportive for refining margins
The geopolitical situation may dominate ordinary inventory data if shipping conditions deteriorate materially.
4. Thursday, July 23
Canada retail sales—May 2026
Statistics Canada will release May retail trade at 8:30 a.m. Eastern, along with refined-petroleum and natural-gas statistics.
This is the week’s second-most important Canadian release after CPI.
Sector implications
Retail-sales result
Likely beneficiaries
Likely pressure
Strong headline and volume growth
CTC.A, LNR indirectly, banks and consumer discretionary
Defensive retailers may lag
Weak core retail sales
Dollarama and discount retailers may outperform relatively
Canadian Tire, apparel and discretionary retailers
Strong auto sales
Magna, Linamar and auto-related lenders
—
Weak gasoline volumes
Convenience retailers and refiners
Energy demand sentiment
The volume measure matters more than nominal sales. Higher sales caused only by price increases do not necessarily indicate stronger consumer demand.
European Central Bank decision
The ECB’s monetary-policy meeting and press conference are scheduled for July 23. Economists broadly expect no immediate change, but higher energy prices have increased the possibility of a later rate increase.
TSX impact
Hawkish ECB: global yields could rise; negative for technology, gold, utilities and REITs
Dovish ECB: supportive for global equities and precious metals
Strong euro reaction: may weaken DXY, potentially supporting gold and commodities
Energy-inflation emphasis: reinforces the Middle East–inflation risk
U.S. weekly jobless claims
Claims will provide a timely reading on the U.S. labour market ahead of the July 29 Federal Reserve decision.
A sharp rise in claims could support rate-cut expectations but also increase recession concerns. The TSX reaction would therefore depend on whether investors focus on lower yields or weaker growth.
5. Friday, July 24
Global flash PMIs
Preliminary July purchasing-managers’ indexes for the United States, eurozone and United Kingdom are expected Friday. These reports will provide an early reading on manufacturing, services, orders, employment and input-price pressures.
TSX sensitivity
PMI signal
Likely effect
Strong manufacturing and new orders
Positive for industrials, materials, energy and railways
Weak manufacturing
Negative for copper, steel, forestry and transportation
Strong services plus rising prices
Inflation concern; yields may rise
Weak services and manufacturing
Recession concern; defensive sectors may outperform
The input-price components will be particularly important because markets are already assessing higher oil costs.
U.S. new-home sales
June new-home sales are scheduled for 10:00 a.m. Eastern.
The TSX exposure is mainly indirect:
Forestry and lumber companies
Building-material suppliers
Railways
Canadian banks with U.S. exposure
Interest-rate-sensitive equities
Strong sales could support cyclical companies but also keep U.S. bond yields elevated.
Infrastructure margins and real-estate development
Rising raw-material prices are positive for commodity producers but negative for companies unable to pass costs through to customers.
Geopolitical Risks to Monitor All Week
1. Strait of Hormuz and broader Gulf conflict — highest risk
Watch for:
Further reductions in tanker traffic
Damage to oil, LNG, power or desalination infrastructure
Expansion into the Red Sea
U.S. or Iranian indications of negotiations
Strategic petroleum reserve releases
Insurance and freight-rate increases
TSX direction: positive for energy initially; negative for the broad index if oil inflation pushes yields sharply higher.
2. Canada–U.S. trade and USMCA uncertainty
The United States declined to extend the North American trade agreement during its formal review, while existing tariffs on Canadian autos, metals and lumber remain major points of dispute.
Exposed TSX groups
Magna and Linamar
Steel and aluminum producers
Forestry companies
Railways
Industrials
Canadian dollar
Banks through business-credit exposure
Any announcement of sector exemptions or negotiations would be positive. Additional tariffs or retaliatory measures would be negative.
3. OPEC+ supply response
OPEC+ approved an additional August production increase, while OPEC also reduced its 2026 oil-demand-growth forecast.
This creates opposing forces:More OPEC+ supply→lower oil pressure
versus:Hormuz disruption→higher oil pressure
The ability to transport oil may be more important than stated production targets while the strait remains disrupted.
Priority Ranking
Rank
Event or risk
Expected TSX relevance
1
U.S.–Iran conflict and Strait of Hormuz
Energy, inflation, gold and broad risk sentiment
2
Canada CPI—Monday
BoC expectations, yields, CAD and rate-sensitive sectors
3
Canada retail sales—Thursday
Consumer companies and banks
4
ECB decision—Thursday
Global yields, currencies and gold
5
Global PMIs—Friday
Materials, energy and industrial growth expectations
6
Canada producer/manufacturing data—Friday
Industrial margins and domestic activity
7
Canada–U.S. trade developments
Autos, metals, forestry and industrials
8
U.S. housing and labour indicators
Secondary yield and growth effects
Actionable Takeaways
The week’s TSX direction will likely depend on the interaction of three forces:Canadian inflation+Middle East oil risk+global bond yields
Energy could rise while the broader TSX falls if escalating conflict pushes both oil and bond yields higher.
A soft Canadian CPI report could support REITs, utilities, technology and consumer discretionary shares.
Weak retail sales would favour defensive staples relative to discretionary companies.
Friday’s PMI and Canadian producer-price data will show whether higher energy costs are beginning to weaken growth while raising inflation.
830 am ET: Canadian consumer price index for June. Consensus is for a decline of 0.2% from May and a rise of 3% from a year earlier
830 am ET: Canadian construction investment for May
830 am ET: Canadian household credit
10 am ET: U.S. leading indicator for June
Earnings include: Domino’s Pizza Inc.; Steel Dynamics Inc.
Tuesday July 21
UK employment data and Germany business conditions survey
815 am ET: U.S. ADP employment report
Earnings include: Capital One Financial Corp.; Charles Schwab Corp.; General Motors Co.; Halliburton Co.; Hasbro Inc.; Interactive Brokers Group Inc.; Novartis AG; 3M Co.
Wednesday July 22
UK inflation data for June
Earnings include: Alphabet Inc.; AT&T Inc.; Choice Properties REIT; CSX Corp.; Kinder Morgan Inc.; Phillip Morris International Inc.; Rogers Communications Inc.; Tesla Inc.; Texas Instruments Inc.; Waste Connections Inc.
Thursday July 23
7 am ET: CFIB Business Barometer
815 am ET: ECB monetary policy announcement
830 am ET: Canadian retail sales for May. Consensus is for a rise of 1%. An advance estimate for June will also be released
830 am ET: U.S. weekly initial jobless claims
Euro area consumer confidence survey
Earnings include: American Airlines Group Inc.; Blackstone Inc.; Cenovus Energy Inc.; FirstService Corp.; Freeport-McMoran Copper & Gold Inc.; Honeywell International Inc.; Intel Corp.; Lockheed Martin Corp.; Newmont Corp.; Norfolk Southern Corp.; Ovintiv Inc.; RTX Corp.; Teck Resources Ltd.; T-Mobile US Inc.; Union Pacific Corp.; Winpak Ltd.
Friday July 24
Japan inflation data and PMIs
Euro area PMIs and consumer confidence reports
830 am ET: Canada industrial product price index and raw materials price index for June.
830 am ET: Canadian manufacturing sales for June
830 am ET: Canadian wholesale trade for June
830 am ET: Canadian new housing price index for June. It’s expected to be down 0.3% on a monthly basis, or a decline of 2.5% on an annual basis.
945 am ET: S&P global PMIs
10 am ET: U.S. new home sales
Earnings include: American Express Co.; Canadian National Railway Co.; Exxon Mobil Corp.; NextEra Energy Inc.; Verizon Communications Inc.
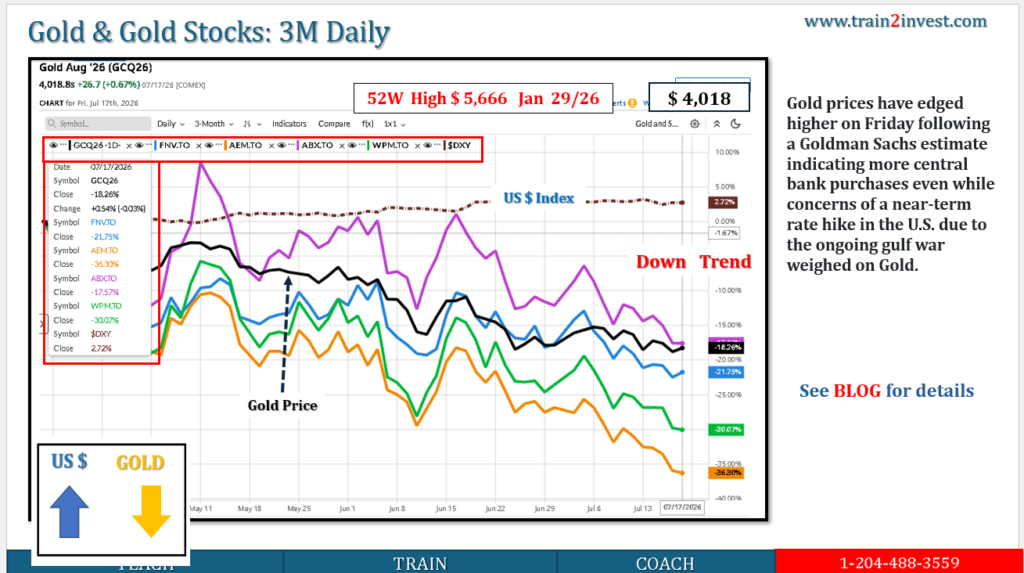
Gold fell 2.23% over the five trading days ended July 17, 2026, closing at approximately US$4,012.70 per ounce.
The U.S. Dollar Index was slightly lower, falling from roughly 100.95 to 100.76. Gold therefore declined despite a softer dollar.
Gold equities fell more than bullion: approximately FNV –3.3%, ABX –5.7%, WPM –6.3% and AEM –7.7%.
The main pressure came from higher-for-longer interest-rate expectations, rising oil-related inflation concerns, analyst target reductions and profit-taking.
A stronger Canadian dollar also reduced the CAD value of U.S.-dollar gold revenue, creating an additional headwind for TSX-listed producers.
Five-Day Performance: July 13–17, 2026
Asset
July 10
July 17
Approx. change
Gold futures
US$4,104/oz
US$4,012.70/oz
–2.23%
U.S. Dollar Index—DXY
100.95
100.76
–0.2%
Franco-Nevada—FNV.TO
C$290.92
About C$281.30
–3.3%
Barrick Mining—ABX.TO
C$51.90
C$48.92
–5.7%
Wheaton Precious Metals—WPM.TO
C$155.83
C$145.96
–6.3%
Agnico Eagle—AEM.TO
C$207.94
C$191.93
–7.7%
Gold’s weekly result and Friday close are confirmed by commodity-market data. The individual equity figures are based on available historical closing-price records; FNV’s July 17 figure should be treated as approximate because public sources displayed inconsistent intraday and closing data.
1. Gold Price
Why gold declined
Gold started the week near US$4,100 per ounce, weakened materially Wednesday and Thursday, then recovered modestly Friday.
The key decline occurred Thursday, when gold fell about 2%. Escalating U.S.–Iran tensions pushed oil prices higher, which increased concern that energy inflation could keep U.S. interest rates elevated.
Ordinarily, geopolitical conflict supports gold through safe-haven demand. During this week, however, the market focused more heavily on the inflation and interest-rate consequences:Higher oil→higher inflation risk→higher expected interest rates→pressure on gold
Gold pays no interest. When government-bond yields remain high, the opportunity cost of holding gold increases.
U.S. gold futures settled at US$4,051.80 on Wednesday, before falling further Thursday. Gold then gained approximately 0.7% Friday, but the rebound was insufficient to reverse the weekly loss.
Why geopolitical tension did not lift gold
The geopolitical effect was contradictory:
Effect
Gold implication
Safe-haven demand
Positive
Higher oil and inflation expectations
Negative
Higher expected interest rates
Negative
Market risk reduction
Potentially positive
Profit-taking after the previous gold rally
Negative
During this five-day period, the negative interest-rate and positioning effects outweighed safe-haven buying.
2. U.S. Dollar Index—DXY
DXY was broadly stable to slightly lower. It began the period near 100.95, rose to approximately 101.24 Monday, and ended close to 100.76 Friday.
Why the dollar weakened
Softer-than-expected U.S. inflation data reduced expectations for another Federal Reserve rate increase. This lowered the relative interest-rate support available to the dollar.
At the same time, geopolitical tensions created some safe-haven demand for U.S. dollars. The two forces largely offset each other:Lower Fed expectations→weaker dollar
butGeopolitical risk→safe-haven dollar demand
The result was a relatively small weekly DXY movement.
Why gold fell even though DXY weakened
Gold and the U.S. dollar frequently move inversely, but this is not a fixed mathematical relationship.
This week:
DXY declined only modestly.
Real and nominal interest-rate concerns remained elevated.
Oil-related inflation fears increased.
Investors continued reducing precious-metals exposure.
Therefore, the interest-rate and positioning effects were stronger than the small positive effect of a softer dollar.
3. Franco-Nevada—FNV.TO
FNV declined approximately 3%–4%, less than the major gold producers.
Why FNV held up better
Franco-Nevada is a royalty and streaming company, not a conventional mine operator. It provides capital to mining companies in exchange for a percentage of future production or revenue.
It has limited direct exposure to:
Mine operating costs
Labour inflation
Fuel costs
Equipment costs
Mine construction overruns
Daily mine-management problems
That generally gives FNV lower operating leverage than Barrick or Agnico Eagle.
The stock still fell because lower gold prices reduce the expected value of future royalty revenue. But the royalty model helped limit the decline relative to the producers.
FNV closed around C$290.92 on July 10 and traded near the low-C$280s by the end of the week.
4. Barrick Mining—ABX.TO
ABX declined from C$51.90 to C$48.92, a loss of approximately:51.9048.92−51.90×100=−5.74%
Why Barrick underperformed gold
Barrick has operating leverage to gold:Operating profit per ounce=gold price−production cost
Illustrative example:
Assumption
Before decline
After decline
Gold price
US$4,100
US$4,010
Production cost
US$1,700
US$1,700
Margin per ounce
US$2,400
US$2,310
Margin change
—
–3.8%
A roughly 2.2% gold decline can therefore produce a larger percentage reduction in expected operating profit.
Barrick is also exposed to:
Political and permitting risk
Mine-development risk
Copper-price exposure
Capital expenditures
Production guidance
Cost inflation
Those factors explain why ABX fell substantially more than bullion.
5. Wheaton Precious Metals—WPM.TO
WPM fell from C$155.83 to C$145.96, a decline of approximately:155.83145.96−155.83×100=−6.33%
Why WPM fell more than FNV
Wheaton is also a streaming company, but its revenue has meaningful exposure to silver as well as gold.
Silver declined approximately 6.3% during the week, substantially more than gold.
Therefore, WPM faced two commodity pressures:
Lower gold prices
A much sharper silver-price decline
WPM’s higher sensitivity to silver helps explain why it underperformed Franco-Nevada despite both having royalty-and-streaming models.
6. Agnico Eagle—AEM.TO
AEM declined from roughly C$207.94 to C$191.93, a loss of approximately:207.94191.93−207.94×100=−7.70%
Why AEM experienced the largest decline
AEM faced both sector-wide and company-specific pressure.
Gold-price leverage
As a major operating producer, AEM’s earnings and cash-flow expectations are sensitive to changes in gold prices.
Barnat mine concern
Agnico previously reported a rock-mass movement at the Barnat open pit. Although this was not necessarily a new development during the five-day period, it remained an operational uncertainty affecting market sentiment.
Analyst target reductions
Several analysts reduced their AEM price targets during the period or immediately around it, largely reflecting lower commodity-price forecasts and mine-specific assumptions. The ratings were often maintained, but lower targets reinforced short-term selling pressure.
A target reduction does not directly reduce the company’s cash flow. It can, however, influence investor positioning when it confirms that analysts are using lower gold-price assumptions.
Canadian-Dollar Effect
The Canadian dollar gained approximately 1% against the U.S. dollar during the week, reaching about US$0.7135, or C$1.4015 per U.S. dollar.
Gold is priced internationally in U.S. dollars. For a TSX-listed gold company:CAD gold price=USD gold price×USD/CAD exchange rate
If gold falls in U.S. dollars and the Canadian dollar strengthens, the decline in Canadian-dollar gold revenue is amplified.
Illustrative example:
Variable
Start
End
Gold
US$4,104
US$4,013
USD/CAD
1.4125
1.4015
Implied CAD gold
C$5,798
C$5,624
Approximate decline
–3.0%
Thus, although U.S.-dollar gold fell about 2.2%, its implied Canadian-dollar value declined closer to 3%.
That created an additional headwind for FNV, ABX, WPM and AEM on the TSX.
Gold producer plus operational and analyst concerns
–7.7%
The ordering is economically consistent:bullion→royalty company→operating miners
Operating mining shares normally move more than the underlying commodity because their earnings contain operational and financial leverage.
Scenarios
Scenario
Gold and equities implication
Bull
Lower bond yields, weaker DXY and easing oil inflation allow gold to recover above US$4,100; miners likely outperform bullion
Base
Gold consolidates around US$3,950–US$4,100; royalty companies remain more stable than producers
Bear
Higher oil, persistent inflation and renewed rate-hike expectations push gold below US$3,950; producers remain the most vulnerable
What Would Disprove This Interpretation?
The interest-rate thesis would weaken if:
Bond yields decline materially but gold continues falling.
DXY weakens significantly without a gold recovery.
Gold stabilizes while AEM, ABX and WPM continue declining sharply.
Mining companies report new production, cost or balance-sheet problems.
In those circumstances, company-specific operational and valuation concerns would be more important than the gold price itself.
Actionable Takeaways
Gold declined despite a modestly weaker DXY because interest-rate and inflation concerns dominated the currency effect.
Gold equities amplified bullion’s decline because of operating leverage and the stronger Canadian dollar.
FNV was relatively defensive because it does not operate mines.
WPM was additionally affected by silver’s sharp decline.
AEM experienced the greatest pressure, reflecting gold weakness, analyst target cuts and continuing mine-specific uncertainty.
A sustainable recovery would likely require some combination of lower bond yields, softer oil-driven inflation, a weaker dollar and stabilization above US$4,000 gold.
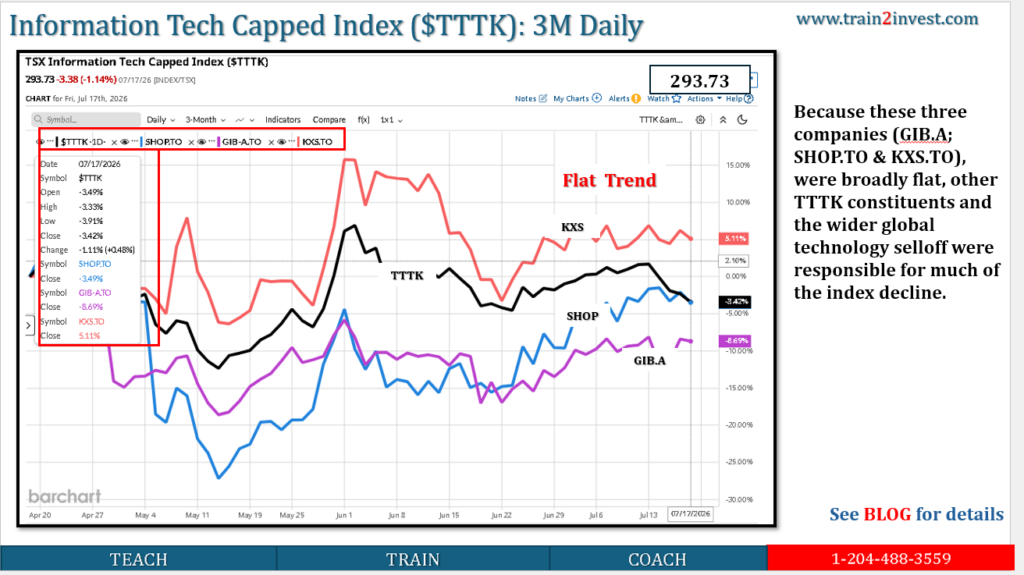
TTTK—the S&P/TSX Capped Information Technology Index—fell 4.96% over July 13–17, declining from 309.05 to 293.73. Most of the damage occurred Tuesday through Friday.
Shopify was almost unchanged overall, down approximately 0.16%, despite substantial daily volatility.
Kinaxis gained approximately 0.10%, effectively finishing flat after alternating gains and declines.
CGI’s correct TSX ticker is GIB.A.TO, not GIB.TO. CGI gained approximately 0.57% over the period despite a sharp 4% decline Tuesday.
Because these three companies were broadly flat, other TTTK constituents and the wider global technology selloff were responsible for much of the index decline.
Five-Day Performance
Security
July 10 close
July 17 close
Five-day change
TTTK
309.05
293.73
–4.96%
SHOP.TO
C$173.51
C$173.23
–0.16%
KXS.TO
C$154.81
C$154.97
+0.10%
GIB.A.TO
C$94.85
C$95.39
+0.57%
Price data:
1. TTTK Technology Index
Daily movement
Date
TTTK close
Daily change
July 13
309.29
+0.08%
July 14
303.78
–1.78%
July 15
298.39
–1.77%
July 16
297.11
–0.43%
July 17
293.73
–1.14%
TTTK declined during four consecutive sessions after Monday.
Main explanation
The sector was affected by a broader reduction in technology and high-growth exposure. On Friday, global semiconductor and growth stocks sold off, weakening sentiment toward Canadian technology shares as well. The TSX Composite declined only about 0.2% Friday, showing that the technology weakness was substantially worse than the overall Canadian market.
Higher bond yields and renewed inflation concerns also mattered. Early in the week, the U.S. 10-year Treasury yield was around 4.58%–4.62%, while escalating U.S.–Iran tensions lifted oil prices. High yields normally place more pressure on technology valuations because a larger portion of their expected earnings lies further in the future.
However, TTTK’s almost 5% decline cannot be explained solely by Shopify, Kinaxis and CGI because those three stocks finished the period approximately flat. Other major technology constituents therefore contributed materially to the index weakness.
2. Shopify — SHOP.TO
Price pattern
Date
Close
Daily change
July 13
C$176.57
+1.76%
July 14
C$176.84
+0.15%
July 15
C$173.61
–1.83%
July 16
C$175.76
+1.24%
July 17
C$173.23
–1.44%
Shopify finished only C$0.28 below its July 10 close, but the stock traded through a broad range during the week.
What drove Shopify
Shopify initially resisted the sector decline on Monday and Tuesday. Investors remained supported by its existing growth narrative, first-quarter operating momentum and share-repurchase authorization.
However, Wednesday and Friday brought renewed selling as investors reduced exposure to higher-valuation growth shares. Shopify is particularly sensitive to:
Nasdaq and growth-stock sentiment
Bond yields
E-commerce growth expectations
Expectations for merchant spending
Valuation ahead of earnings
Shopify had announced that its second-quarter 2026 results would be released shortly, but it issued no new financial results during the five-day period.
Interpretation
Shopify’s weekly movement was:early strength→growth-stock selling→temporary rebound→Friday risk reduction
The stock’s flat weekly result concealed significant day-to-day volatility.
3. Kinaxis — KXS.TO
Price pattern
Date
Close
Daily change
July 13
C$157.16
+1.52%
July 14
C$154.36
–1.78%
July 15
C$153.58
–0.51%
July 16
C$156.17
+1.69%
July 17
C$154.97
–0.77%
Kinaxis finished approximately 0.1% higher than its July 10 close.
What drove Kinaxis
No major Kinaxis-specific financial announcement was identified during the week. The stock therefore largely followed changing technology-sector sentiment.
Supporting factors included Kinaxis’s previously reported record first-quarter performance and maintained 2026 guidance:
Revenue guidance of US$620 million–US$635 million
SaaS revenue-growth guidance of 17%–19%
Adjusted EBITDA-margin guidance of 25%–26%
The Tuesday–Wednesday decline was consistent with broader software-sector valuation pressure. Thursday’s rebound suggested that investors were still willing to buy KXS after pullbacks, but Friday’s technology selloff prevented the stock from maintaining those gains.
Interpretation
KXS was range-bound, not in a clear five-day downtrend. The market was balancing strong recurring-revenue fundamentals against high software valuations and broader risk aversion.
4. CGI — GIB.A.TO
Price pattern
Date
Close
Daily change
July 13
C$96.00
+1.21%
July 14
C$92.16
–4.00%
July 15
C$92.58
+0.46%
July 16
C$95.70
+3.37%
July 17
C$95.39
–0.32%
CGI ended the period approximately 0.57% higher, despite unusually large Tuesday and Thursday moves.
What drove CGI
Monday’s gain may have received some support from CGI’s recent launch of the Massachusetts statewide financial-management system, but there was no new earnings announcement during the five sessions.
Tuesday’s 4% decline appears primarily related to:
Technology-sector risk reduction
Valuation uncertainty
Continuing concern about slower discretionary IT-consulting spending
Residual caution following a recent analyst target reduction
The stock had previously received a Scotiabank price-target reduction from C$110 to C$95, which likely remained an overhang.
Thursday’s 3.37% rebound recovered most of Tuesday’s loss, indicating that the decline did not reflect a confirmed deterioration in CGI’s reported operations.
Facts Versus Inference
Finding
Assessment
TTTK declined approximately 5%
Verified
SHOP, KXS and CGI were approximately flat overall
Verified
Friday’s global technology selloff hurt TTTK
Strongly supported
Higher yields pressured technology valuations
Standard valuation mechanism
A single event caused TTTK’s entire decline
Not supported
Shopify, Kinaxis and CGI explain the full index loss
Mathematically inconsistent with their weekly returns
Bottom Line
The five-day technology pattern was unusual:
The overall TTTK index fell sharply.
Shopify finished virtually unchanged.
Kinaxis finished virtually unchanged.
CGI finished modestly higher.
Therefore, the index’s decline was broader than these three stocks and was likely concentrated in other major TTTK constituents, combined with a global reduction in semiconductor, AI and high-growth technology exposure.
The strongest evidence of continued weakness would be TTTK remaining below approximately 294 while Shopify, Kinaxis and CGI also begin breaking below their recent trading ranges. A recovery above approximately 304–309 would weaken the short-term bearish interpretation.
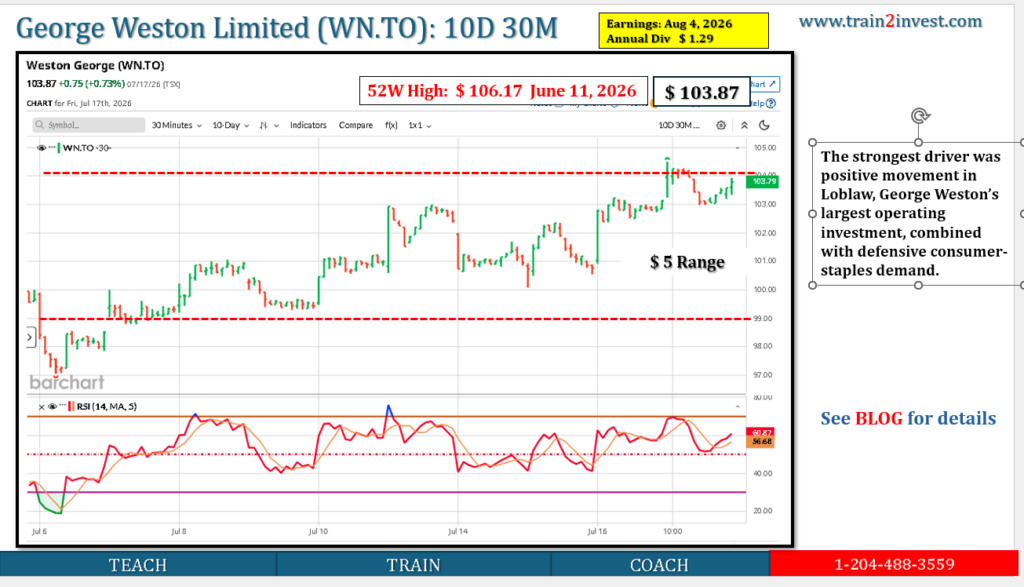
George Weston (WN.TO) gained 2.86% over July 13–17, 2026, rising from C$100.98 to C$103.87.
The stock advanced Monday, declined Tuesday and was nearly flat Wednesday, before rebounding strongly Thursday and Friday.
No major George Weston-specific announcement was identified during the five sessions.
The strongest driver was positive movement in Loblaw, George Weston’s largest operating investment, combined with defensive consumer-staples demand.
Share repurchases and solid underlying results provided background support, but did not create a specific daily catalyst.
Five-Day Price Movement
Date
Close
Daily change
Main interpretation
July 10
C$100.98
—
Starting reference
July 13
C$102.44
+1.45%
Defensive-sector buying
July 14
C$100.95
–1.45%
Profit-taking
July 15
C$100.88
–0.07%
Consolidation
July 16
C$103.12
+2.22%
Strong Loblaw/staples rebound
July 17
C$103.87
+0.73%
Positive momentum continued
Overall return
100.98103.87−100.98×100=2.86%
WN.TO therefore gained C$2.89 per share, or approximately 2.9%, over the period.
Key Drivers
1. Loblaw was the principal operating driver
George Weston is primarily a holding company whose value is heavily influenced by its ownership of:
Loblaw Companies
Choice Properties REIT
Corporate cash, debt and other investments
Loblaw gained approximately 2.0% over the same five-day period, supported by defensive demand for grocery, pharmacy and discount-retail exposure.
Because Loblaw is George Weston’s largest underlying asset, strength in L.TO generally increases the market value attributed to WN.TO.
This relationship is not necessarily one-for-one because George Weston also has:
Holding-company debt
Corporate expenses
Choice Properties exposure
Tax considerations
A holding-company discount
2. Defensive consumer-staples rotation
The broader consumer-staples sector strengthened during the latter part of the week.
Investors generally view George Weston’s underlying businesses as defensive because they are concentrated in:
Food retail
Pharmacy and healthcare products
Discount grocery
Essential consumer goods
Grocery-anchored real estate
These businesses are less dependent on discretionary household spending than automotive, apparel or durable-goods companies.
This likely contributed to Monday’s increase and the strong Thursday–Friday recovery.
3. Tuesday–Wednesday decline was likely consolidation
WN.TO fell from C$102.44 Monday to C$100.88 Wednesday, a decline of approximately:102.44100.88−102.44×100=−1.52%
No material negative George Weston announcement was identified during those sessions.
The pullback was most consistent with:
Profit-taking after recent gains
Movement in Loblaw and other staples shares
Normal short-term consolidation
Valuation caution as WN approached recent highs
This is an inference, not a directly confirmed cause.
4. Strong Thursday rebound followed Loblaw’s pattern
WN.TO gained 2.22% Thursday, its strongest session of the week.
Loblaw also rose strongly that day. This supports the conclusion that the movement was linked mainly to the value of George Weston’s underlying holdings rather than a separate Weston-specific event.
The share-price pattern was therefore:Loblaw/staples movement→change in WN holding value→WN share-price response
5. Share repurchases supported per-share value
George Weston purchased and cancelled 2.9 million shares for C$275 million during the first quarter of 2026. The lower share count contributed approximately C$0.03 per share to adjusted EPS growth.
Buybacks can support the stock by:
Reducing shares outstanding
Increasing earnings per share
Increasing each remaining shareholder’s proportional interest
Narrowing the holding-company valuation discount
However, there was no new repurchase announcement during the five-day period itself.
Fundamental Background
George Weston’s first-quarter results showed:
Metric
Q1 2026
Adjusted net earnings available to common shareholders
C$333 million
Year-over-year growth
+1.8%
Adjusted diluted EPS
C$0.87
Adjusted EPS growth
+4.8%
Shares repurchased and cancelled
2.9 million
Repurchase value
C$275 million
Loblaw generated positive sales momentum, while Choice Properties reported stable occupancy and strong leasing spreads.
Facts Versus Inference
Finding
Assessment
WN.TO gained 2.86%
Verified
Thursday was the strongest session
Verified
Loblaw rose over the same period
Verified
George Weston released major news during the week
No major release identified
Loblaw strength drove much of WN’s gain
Strong evidence-based inference
Tuesday–Wednesday weakness was profit-taking
Reasonable inference
George Weston’s intrinsic value rose exactly 2.86%
Not established
Scenarios
Scenario
Near-term implication
Bull
Continued Loblaw strength, stable Choice Properties performance and buybacks could move WN toward its 52-week high near C$106
Base
WN consolidates between approximately C$100 and C$106 while awaiting earnings
Bear
Weak Loblaw results, REIT pressure or a wider holding-company discount could push WN below C$100
What Would Disprove This Explanation?
The Loblaw-driven interpretation would weaken if:
WN declines while Loblaw continues rising
Choice Properties weakens materially
George Weston increases corporate debt substantially
The holding-company discount widens
George Weston reports weaker standalone cash flow or higher corporate expenses
The stock finished approximately 2.9% higher. The most credible explanation is strength in Loblaw and defensive consumer-staples positioning, rather than a new George Weston-specific event.
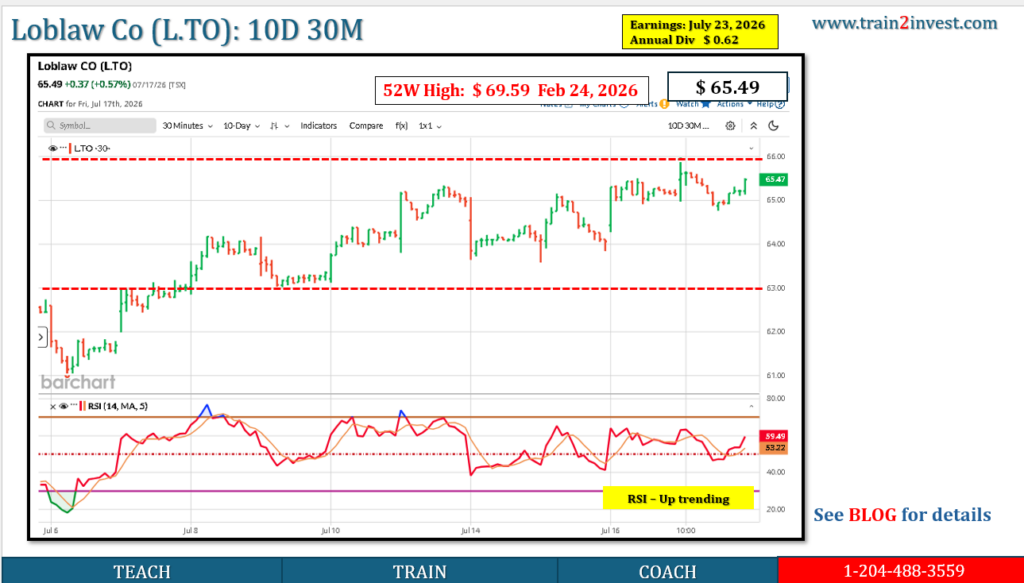
Loblaw (L.TO) gained approximately 2.0% over July 13–17, 2026, rising from C$64.18 on July 10 to C$65.49 on July 17.
The stock rose Monday, pulled back Tuesday and Wednesday, then recovered strongly Thursday and Friday.
No major Loblaw-specific operating announcement was identified during the week.
The overall gain was most consistent with defensive-sector rotation, resilient grocery and pharmacy demand, and continued interest in Loblaw’s discount banners.
The Tuesday–Wednesday decline appears to have been short-term profit-taking rather than evidence of a new deterioration in the business.
Five-Day Price Movement
Date
Close
Daily change
Interpretation
July 10
C$64.18
—
Starting reference
July 13
C$64.96
+1.22%
Defensive buying
July 14
C$64.18
–1.20%
Profit-taking
July 15
C$64.08
–0.16%
Consolidation
July 16
C$65.12
+1.62%
Strong rebound
July 17
C$65.49
+0.57%
Defensive strength continued
The five-day return was:64.1865.49−64.18×100≈2.04%
Loblaw therefore gained C$1.31 per share, or approximately 2.0%, over the period.
Key Drivers
1. Defensive rotation supported Loblaw
Loblaw operates grocery, pharmacy and discount retail banners, including No Frills, Maxi and Shoppers Drug Mart. Demand for food, medication and household necessities is generally less economically sensitive than demand for vehicles, apparel or durable goods.
During periods of broader market uncertainty, investors often shift toward companies with:
Recurring consumer demand
Stable cash flow
Pricing power
Discount-retail exposure
Lower sensitivity to interest rates
This defensive positioning likely contributed to Monday’s rise and the Thursday–Friday recovery.
2. Discount banners remain an important strength
Canadian households continue to emphasize value because of elevated food, housing and borrowing costs. Loblaw’s discount formats—particularly No Frills and Maxi—are positioned to benefit when shoppers trade down from conventional supermarkets.
Loblaw’s first-quarter results showed food retail same-store sales growth of 2.4% and drug retail same-store sales growth of 4.1%. The company maintained its expectation for high-single-digit growth in adjusted net earnings for 2026.
These fundamentals provided an underlying reason for investors to buy the midweek dip.
3. Tuesday–Wednesday weakness was likely profit-taking
Loblaw fell from C$64.96 Monday to C$64.08 Wednesday, a combined decline of approximately:64.9664.08−64.96×100≈−1.35%
No material negative Loblaw announcement was identified during those sessions. The pullback therefore appears to have reflected:
Profit-taking after recent gains
Rotation between consumer-staples constituents
Caution over Loblaw’s valuation
Normal short-term price consolidation
This is a market inference, not a mathematically proven cause.
Loblaw gained approximately 2.2% over Thursday and Friday combined.
The rebound was consistent with the broader strength of the consumer-staples sector during the latter part of the week. Investors appeared to favour companies whose sales are less dependent on discretionary household spending.
The company’s grocery and pharmacy exposure also makes Loblaw less vulnerable than consumer-discretionary retailers to higher fuel prices and financing costs.
5. Share repurchases provided longer-term support
Loblaw’s renewed normal-course issuer bid permits it to repurchase up to approximately 58.1 million common shares during the 12 months beginning May 8, 2026.
Buybacks can support per-share value by:
Reducing shares outstanding
Increasing EPS, assuming earnings are unchanged
Providing incremental demand during market weakness
Returning excess capital to shareholders
There was no new buyback announcement during the five sessions, so this was background support rather than a specific daily catalyst.
Fundamental Balance
Positive factors
Stable grocery and pharmacy demand
Growth at discount banners
Private-label exposure through President’s Choice and No Name
Share repurchases
Store and distribution-network investment
Defensive earnings profile
Loblaw plans to invest C$2.4 billion in 2026, including 70 new stores and 191 renovations, as part of its longer-term expansion and supply-chain program.
Negative factors
First-quarter revenue of C$14.48 billion was below analysts’ expectations of approximately C$14.55 billion.
Consumers remain cautious in non-essential categories.
Large capital expenditures may pressure near-term free cash flow.
Grocery-sector competition and political scrutiny remain elevated.
A relatively defensive company can still decline when valuation expectations become excessive.
Facts Versus Inference
Finding
Assessment
L.TO gained approximately 2.0%
Verified
Monday, Thursday and Friday were positive
Verified
Tuesday and Wednesday were negative
Verified
Loblaw issued major operating news during the week
No major release identified
Defensive rotation supported the stock
Strong economic inference
Midweek weakness reflected profit-taking
Reasonable inference
Loblaw’s earnings outlook improved during the week
Not established
Scenarios
Scenario
Near-term implication
Bull
Resilient same-store sales, discount-banner growth and buybacks support a move above C$66
Base
L.TO consolidates around C$63–C$66 while investors await the next earnings report
Bear
Weaker grocery volumes, margin pressure or disappointing pharmacy sales push the stock below C$63
What Would Disprove the Positive Interpretation?
The view that Loblaw’s five-day gain reflected defensive strength would weaken if:
Food and drug same-store sales slow materially
Customer traffic falls at No Frills and Maxi
Gross margins contract despite higher prices
Loblaw cuts its earnings-growth outlook
L.TO declines while the broader consumer-staples sector continues rising
The stock finished the week approximately 2.0% higher, without a major company-specific catalyst. The most credible explanation is defensive investor positioning supported by Loblaw’s grocery, pharmacy and discount-retail fundamentals.