Author: Consultant

  • Aprl. 13/26: Liberal Govt. Policies Under Mark Carney

    Executive Summary

    • Mark Carney’s energy framework centers on net-zero alignment + capital mobilization, not production growth alone.
    • Core mechanism: carbon pricing + financial system incentives to redirect capital toward low-carbon energy.
    • Implies reallocation within energy sector: oil sands face higher cost of capital; renewables, nuclear, and CCUS gain.
    • Short-term: investment uncertainty + transition costs. Long-term: lower cost of capital for compliant assets.
    • Key constraint: global demand for hydrocarbons vs domestic decarbonization policy mismatch.

    Key Drivers

    1) Carbon Pricing as Capital Signal

    • Carney has consistently supported economy-wide carbon pricing (via roles at Bank of England and United Nations climate initiatives).
    • Mechanism:
      • Raises marginal cost of high-emission production (oil sands, heavy crude)
      • Forces internalization of externalities into project IRR  (Internal Rate of Return)

    Impact (Canada context):

    • Oil sands breakeven ↑ by ~$5–$15/bbl (assumption range depending on carbon price trajectory)
    • Renewable project IRRs ↑ due to relative competitiveness

    2) Financial System Rewiring (Core Carney Thesis)

    • Founder of GFANZ (Glasgow Financial Alliance for Net Zero)
    • Strategy: use banks, pensions, insurers to enforce transition

    Transmission channels:

    • Lending standards (scope emissions)
    • Cost of capital differentiation
    • Mandatory climate disclosures (TCFD-aligned)

    Implication:

    SegmentCost of Capital DirectionInvestment Flow
    Oil sands↑Outflows / selective
    Conventional oilSlight ↑Neutral to modest decline
    Natural gas (LNG)MixedTransitional inflow
    Renewables↓Strong inflow
    Nuclear / SMR↓Emerging inflow
    CCUS↓ (policy-dependent)Targeted inflow

    SMR (Small Modular Reactor): next-gen nuclear technology designed for scalable, low-carbon electricity.

    CCUS (Carbon Capture, Utilization, and Storage): technology to capture CO₂ emissions and store or reuse them.

    3) Transition Technologies (Not Anti-Energy, but Rebalanced)

    Carney’s stance is “anti-oil”

    Priority areas:

    • Carbon Capture (CCUS)
    • Hydrogen (blue/green)
    • Nuclear (SMRs in Canada)
    • Electrification infrastructure

    Canadian advantage:

    • Existing energy expertise + geology for CCUS
    • Pension capital (CPP, large funds) aligned with long-duration assets

    4) Regulatory + Disclosure Framework

    • Push for mandatory climate disclosure standards
    • Alignment with IFRS sustainability standards

    Effect:

    • Forces repricing of assets based on:
      • Scope 1, 2, 3 emissions
      • Transition risk
      • Stranded asset probability

    Data & Evidence (Directional, Policy-Based)

    VariablePre-Policy BaselineCarney-Aligned Direction
    Carbon price (CAD/tonne)~$80 (Canada current range)↑ toward $170+ by 2030
    Oil sands capex growthLow-single digitFlat / declining real terms
    Renewable capex growth~10–15% YoY15–25% YoY
    Energy sector capital allocation~70% fossilShift toward ~50% or lower

    Note: Ranges are scenario-based; not point forecasts.

    Valuation Logic

    Oil & Gas

    • Higher discount rates + ESG constraints → multiple compression
    • Cash flow remains strong if oil prices stay elevated
    • Valuation bifurcation:
      • Low-emission producers → premium
      • High-intensity assets → discount

    Renewables / Transition Assets

    • Lower WACC → higher NPV
    • Sensitive to:
      • Interest rates
      • Policy stability
      • Power pricing contracts

    Risks

    Policy Risks

    • Federal vs provincial misalignment (Alberta vs Ottawa)
    • Regulatory delays (pipelines, CCUS approvals)

    Market Risks

    • Global oil demand remains resilient → Canada loses market share
    • Capital flight to U.S. (IRA incentives more aggressive)

    Execution Risks

    • CCUS economics not scaling
    • Grid constraints limiting renewable deployment

    Scenarios

    Bull Case (Energy Transition Works Smoothly)

    • Oil stabilizes ~$85–$100
    • Canada leads in CCUS + LNG exports
    • Energy sector capex grows +5–7% CAGR (rebalanced mix)

    Base Case

    • Oil ~$70–$90
    • Gradual capital rotation
    • Energy sector growth flat to +2% CAGR

    Bear Case (Policy Overreach / Capital Flight)

    • Oil demand strong globally but Canada underinvests
    • Production declines
    • Energy GDP contribution ↓ by 1–2% annually

    What Would Disprove This Framework

    • Sustained global oil demand growth + no penalty in cost of capital for hydrocarbons
    • Failure of financial institutions to enforce climate-linked lending
    • Political rollback of carbon pricing in Canada

    Actionable Takeaways (Decision-Focused)

    • Monitor cost of capital spreads between fossil vs transition assets (leading indicator)
    • Track Canadian vs U.S. policy divergence (IRA vs federal policy)
    • Focus on companies with:
      • Low emissions intensity
      • Exposure to CCUS / LNG / nuclear
    • Watch carbon price trajectory as primary valuation driver, not just oil price

    Impact on the Canadian Economy

    Summary

    • Directionally accurate: the macro has shifted from energy transition → economic security + trade diversification.
    • Near-term impact is negative (tariffs + policy uncertainty); medium/long-term upside is execution-dependent.
    • The core constraint remains: Canada’s high energy sector concentration vs decarbonization policy trajectory.
    • Policy pragmatism (softening constraints) but underestimates ongoing structural frictions.
    • Net: higher volatility, wider outcome dispersion, lower near-term growth visibility.

    Key Drivers (Refined View)Mark Carney’s involment in Brrokfield

    1) Trade Shock (Primary Near-Term Driver)

    • U.S. tariffs → direct GDP drag (~$50B cited).
    • Transmission channels:
      • Export volumes ↓
      • Business confidence ↓
      • Capex deferrals ↑
    • This dominates all other variables in 2026–2027.

    2) Energy Sector Policy Recalibration

    • Shift from strict transition → hybrid growth + transition model.
    • Rollbacks (carbon tax, emissions cap, regulations) reduce immediate downside risk.
    • However:
      • Industrial carbon pricing path still escalates → cost pressure remains embedded.

    3) Capital Allocation Uncertainty

    • Minority government + regional concessions → policy inconsistency risk.
    • Result:
      • Energy + infrastructure capex delayed.
      • Required hurdle rates ↑ (risk premium).

    4) Export Diversification (Structural Lever)

    • Heavy reliance on U.S. (~90% oil exports) = concentration risk.
    • Pipeline/LNG strategy = macro hedge, but:
      • Long lead times
      • Private capital not yet committed → execution risk high.

    5) Long-Duration Energy Transition (SMRs, CCUS)

    • Projects like Darlington New Nuclear Project:
      • Positive for industrial base
      • Minimal near-term GDP contribution
      • Material impact only post-2030

    Data & Economic Exposure

    ComponentApprox ImpactComment
    Oil & Gas GDP~$70B (~3–4% GDP direct)High regional concentration
    Employment~900,000 jobs (direct + indirect)Western Canada sensitive
    U.S. Export Exposure~75% total exportsStructural vulnerability
    Oil Export Dependence~90% to U.S.Key strategic weakness
    Carbon Price Path→ $170/tonne by 2030Broad industrial cost impact

    Data gaps: confirmed tariff structure, actual capex pipeline commitments, inventory of approved vs financed projects.

    Valuation Logic (Macro Lens)

    Short-term (0–12 months):

    • GDP growth ↓ (tariffs + capex delays)
    • Investment multiple compression (policy risk)
    • CAD sensitivity ↑ to oil + trade balance

    Medium-term (2–5 years):

    • Upside contingent on:
      • Pipeline/LNG execution
      • Stable federal-provincial alignment
    • Without execution → growth stagnates near potential (~1–2%)

    Long-term (5–10 years):

    • Transition investments (SMR, CCUS) can:
      • Improve productivity
      • Diversify energy mix
    • But require sustained policy consistency

    Risks (Critical)

    Downside risks (underestimated in your write-up):

    • Carbon pricing still eroding manufacturing competitiveness, not just oil.
    • Persistent U.S. protectionism → structural, not cyclical.
    • Capital flight if policy volatility continues.

    Upside risks:

    • Faster-than-expected pipeline/LNG approvals.
    • Stronger global energy demand sustaining high oil prices.
    • Coordinated federal-provincial industrial policy.

    Scenarios

    ScenarioProbabilityGDP ImpactDescription
    Bear30%0–1% growthTariffs persist, projects stall, capex weak
    Base50%1–2% growthPartial policy clarity, slow diversification
    Bull20%2–3%+ growthMajor energy projects proceed; exports diversify

    What Would Disprove This View

    • Immediate large-scale private investment in pipelines/LNG (removes execution doubt)
    • Clear, stable federal policy framework sustained over 12–18 months
    • Rapid tariff rollback or negotiated resolution with the U.S.

    Actionable Takeaways (Non-advisory)

    • Canada is transitioning into a policy-constrained, externally exposed economy.
    • Near-term macro is demand- and policy-limited, not supply-driven.
    • The investment case hinges less on ideology and more on execution of infrastructure and export diversification.
    • Expect higher macro volatility and regional divergence (West vs Central Canada).

    Bottom line:
    The key refinement is that Canada is not just facing a messy transition—it is operating under a binding trade shock plus unresolved policy contradiction, which caps near-term growth while pushing potential upside further into the future and making it highly conditional.

    Mark Carney &  Brookfield Asset Management

    Executive Summary

    • Mark Carney joined Brookfield Asset Management in 2020.
    • Served as Vice Chair and Head of ESG & Impact Investing.
    • Led Brookfield’s transition/energy investment strategy (including large climate funds).
    • Instrumental in positioning Brookfield as a global decarbonization capital allocator.
    • Role blends policy expertise + capital deployment, not operational management.

    ESG = Environmental, Social, Governance — a framework to evaluate non-financial risks and impacts of a company or investment. Used by investors to assess long-term sustainability, risk, and capital allocation quality. Increasingly linked to regulation, cost of capital, and access to funding.

    Role & Timeline

    PeriodPositionScope
    2020–presentVice Chair, Head of ESG & ImpactClimate strategy, capital allocation, global partnerships
    • Joined after roles as:
      • Governor, Bank of England
      • Governor, Bank of Canada

    Mandate at Brookfield

    1) Climate & Transition Investing

    • Led development of Brookfield Global Transition Fund (multi-billion USD scale).
    • Focus areas:
      • Renewable power (wind, solar)
      • Nuclear (including SMR-related ecosystem)
      • Carbon capture (CCUS)
      • Industrial decarbonization

    2) ESG Integration

    • Embedded ESG into:
      • Investment screening
      • Risk assessment
      • Portfolio management

    3) Capital Formation

    • Leveraged global credibility to:
      • Attract sovereign wealth funds
      • Partner with governments and institutions
    • Positioned Brookfield as a bridge between public policy and private capital

    Strategic Impact on Brookfield

    AreaImpact
    FundraisingIncreased scale of climate-focused funds
    PositioningLeader in “transition investing” vs pure ESG
    Deal flowAccess to government-aligned projects
    Risk frameworkStronger integration of carbon pricing / policy risk

    Economic Lens (Why Brookfield hired him)

    • Carney brings:
      • Policy foresight (carbon pricing, regulation trajectory)
      • Central bank credibility (macro + financial stability)
      • Global network (governments, multilaterals)
    • This allows Brookfield to:
      • Deploy capital ahead of regulatory shifts
      • Structure deals aligned with public policy incentives
      • Reduce policy/regulatory risk premium

    Relevance to Canada / Energy Policy

    • His Brookfield role aligns with:
      • SMR development
      • CCUS scaling
      • Energy transition financing
    • Creates overlap between:
      • Private capital flows (Brookfield)
      • Public policy direction (Canada, G7 climate agenda)

    Risks / Criticism

    • Conflict perception: movement between public policy and private capital
    • Execution risk: large-scale transition investing depends on policy stability
    • Return uncertainty: long-duration assets with regulatory dependency

    Bottom Line

    • At Brookfield, Carney is not an operator—he is a strategic capital allocator and policy translator.
    • His role is to convert climate policy into investable opportunities at scale.
    • This directly influences how global capital flows into energy transition assets, including in Canada.

    Carney’s Book: https://www.penguinrandomhouse.ca/books/669023/values-by-mark-carney/9780771051555?utm_source=chatgpt.com

    Carney’s book is an attempt to redefine capitalism so that financial value reflects societal values, with finance acting as the transmission mechanism.

    END
  • Apr. 13/26: U.S. blockade of Strait of Hormuz set to begin

    • The U.S. says it is set to start blocking ships from entering or exiting the Strait of Hormuz.
    • President Donald Trump slammed Iran for refusing to give up its nuclear ambitions.
    • Stock futures sank, and crude oil prices surged ahead of the blockade.

    The U.S. on Monday morning is set to start blocking ships from entering or exiting the Strait of Hormuz, attempting to ratchet up pressure on Iran to reopen the key oil route after peace negotiations collapsed.

    President Donald Trump, announcing the plan Sunday on Truth Social, slammed Iran for refusing to give up its nuclear ambitions and accused Tehran of “WORLD EXTORTION” by continuing to throttle traffic through the strait.

    The U.S. blockade, set to begin at 10 a.m. ET, will apply to “any and all Ships trying to enter, or leave, the Strait of Hormuz,” Trump said.

    The U.S. Central Command later added the caveat that American forces “will not impede freedom of navigation for vessels transiting the Strait of Hormuz to and from non-Iranian ports.”

    Stock futures sank, and crude oil prices surged ahead of the blockade.

  • TSX Weekly Briefing (April 14–17)

    Macro driver in one line: Everything trades off whether the Iran ceasefire holds or breaks.

    1. Primary Market Drivers

    Oil (WTI/Brent) — Dominant TSX Catalyst

    • Volatility tied to Strait of Hormuz and ceasefire compliance.
    • Brent–WTI spread = logistics stress indicator.
    • TSX impact: Energy is ~18–20% of index; ±5–10% oil swings can move TSX ±3–5%.
    • Trigger levels:
      • Bullish: WTI > $105
      • Risk-off: WTI < $90
    • Key names: Suncor, CNQ, Cenovus

    2. Rates, CPI & Bank of Canada Path

    • Canada CPI (April 20) is the single most important event for Financials, Real Estate, Tech.
    • Watch 5Y GoC yield (mortgage proxy).
    • Market logic:
      • Hot CPI → yields ↑ → banks ↑, REITs ↓
      • Cool CPI → yields ↓ → tech/REITs ↑
    • Key level: 5Y GoC > 3.25% = tightening bias
    • Key names: Royal Bank, TD

    3. U.S. Demand Spillover (Exports Channel)

    • Data to watch: Retail sales, jobless claims.
    • Strong U.S. demand → earnings upgrades for TSX cyclicals.
    • Key names: Magna, Linamar

    4. Metals & Safe-Haven Flows

    • Gold driven by real yields (inverse) and geopolitical risk.
    • Copper = global growth proxy.
    • Trigger: Gold > $2,300 → strong bid for Materials (10–12% of TSX).
    • Key names: Barrick, Agnico Eagle

    5. Earnings & Guidance

    • U.S. banks (GS, JPM, WFC, C, MS, BAC) set tone for Canadian financials.
    • Consumer names (Netflix, J&J, PepsiCo) give demand + cost signals.
    • High-beta TSX names to watch: Shopify, Kinaxis

    6. Daily Monitoring Dashboard

    DriverMetricSignalTSX Impact
    OilWTI>$105 / <$90High
    Rates5Y GoC>3.25% / <2.75%High
    InflationCPI YoY>3% / <2%High
    U.S. GrowthRetail sales>0.5% / <0%Medium
    MetalsGold>$2,300 / <$2,100Medium
    RiskVIX>20Negative

    7. Valuation Context

    • TSX trading 12–14x forward earnings.
    • Upside case: Oil ↑ + stable earnings → 14–15x.
    • Downside case: Rates ↑ + growth ↓ → 11–12x.

    8. Key Risks

    • Ceasefire breakdown → oil spike → inflation shock.
    • Sticky inflation → BoC delays cuts.
    • U.S. demand slowdown → cyclical earnings downgrades.
    • CAD volatility impacting exporters.

    9. Scenario Map (1‑Week Horizon)

    Bull Case

    • Oil stable at $100–105
    • CPI benign (<2.5%)
    • TSX: +1.5% to +3%

    Base Case

    • Oil volatile but contained
    • Mixed macro data
    • TSX: –1% to +1%

    Bear Case

    • Oil shock >$110 or CPI >3%
    • Yields spike
    • TSX: –2% to –4%

    10. Actionable Takeaways

    • Oil + yields explain most TSX movement this week.
    • Canada CPI (Apr 20) is the biggest single-event risk.
    • U.S. data → Industrials/Autos second-order effects.
    • Focus on sector rotation (Energy ↔ Financials ↔ Materials).
    • Validate moves with volume + macro confirmation, not headlines.
  • Economic Calendar: Apr 13 – Apr 17

    Monday April 13

    China’s aggregate yuan financing, new yuan loans and trade surplus

    (8:30 a.m. ET) Canadian building permits for February.

    (10 a.m. ET) U.S. existing home sales for March. The Street is projecting an annualized rate decline of 0.7 per cent.

    Earnings include: Fastenal Co. and Goldman Sachs Group Inc.


    Tuesday April 14

    Japan’s industrial production

    (6 a.m. ET) U.S. NFIB Small Business Economic Trends Survey for March.

    (8:30 a.m. ET) U.S. PPI for March. Consensus is a gain of 1.1 per cent from February and up 4.6 per cent year-over-year.

    Earnings include: AGF Management Ltd., BlackRock Inc., Citigroup Inc., Johnson & Johnson, JP Morgan Chase & Co. and Wells Fargo & Co.


    Wednesday April 15

    Japan’s core machine orders

    Euro zone’s industrial production

    (8:30 a.m. ET) Canadian manufacturing sales and new orders for February. The Street is projecting month-over-month increases of 3.8 per cent and 5.0 per cent, respectively.

    (8:30 a.m. ET) Canada’s wholesale trade for February.

    (8:30 a.m. ET) U.S. import prices for March. Consensus is a rise of 1.7 per cent from February and 3.4 per cent year-over-year.

    (10 a.m. ET) U.S. NAHB Housing Market Index for April.

    (2 p.m. ET) U.S. Beige Book is released.

    Earnings include: Bank of America Corp., JB Hunt Transport Services Inc., Morgan Stanley, PNC Financial Services Group Inc. and Progressive Corp.


    Thursday April 16

    China’s GDP, retail sales, industrial production and fixed asset investment

    Euro zone’s CPI

    (8:30 a.m. ET) Canada’s existing home sales and average prices for March. Estimates are year-over-year declines of 1.5 per cent for each.

    (8:30 a.m. ET) Canada’s MLS Home Price Index for March. Estimate is a drop of 5.0 per cent year-over-year.

    (8:30 a.m. ET) Canadian new motor vehicle sales for February. Estimate is a gain of 1.0 per cent from the same period a year ago.

    (8:30 a.m. ET) U.S. initial jobless claims for week of April 11. Estimate is 214,000 down 5,000 from the previous week.

    (9:15 a.m. ET) U.S. industrial production and capacity utilization for March.

    Also: G20 finance ministers and central bank governors meet in Washington

    Earnings include: Abbott Laboratories, Bank of New York Mellon Corp., Charles Schwab Corp., Kraken Robotics Inc. Netflix Inc., PepsiCo Inc., Prologis Inc., Taiwan Semiconductor Manufacturing and U.S. Bancorp


    Friday April 17

    Euro zone’s trade surplus

    (8:15 a.m. ET) Canadian housing starts for March. Estimate is an annualized rate rise of 1.6 per cent.

    (8:30 a.m. ET) Canada’s international securities transactions for February.

    (8:30 a.m. ET) Canada’s household and mortgage credit for February.

    Earnings include: Fifth Third Bancorp, State Street Corp. and Truist Financial Corp.

  • April 10: Alimentation Couche-Tard Inc. (ATD.TO):

    ATD.TO’s 10‑day rise appears driven by a mix of factors:

    • Continued positive analyst coverage and price‑target increases in March–April.
    • Strong retail fundamentals and earnings momentum for Alimentation Couche‑Tard that lifted sentiment.
    • Technical/momentum buying after the stock traded near its 52‑week highs (buyers piling into a breakout).
    • Above‑average volume on key up days (shows broad buying rather than a single trade).
    • No single material April‑8 corporate filing found — move looks like combination of analyst/earnings sentiment, sector flows and technical demand.
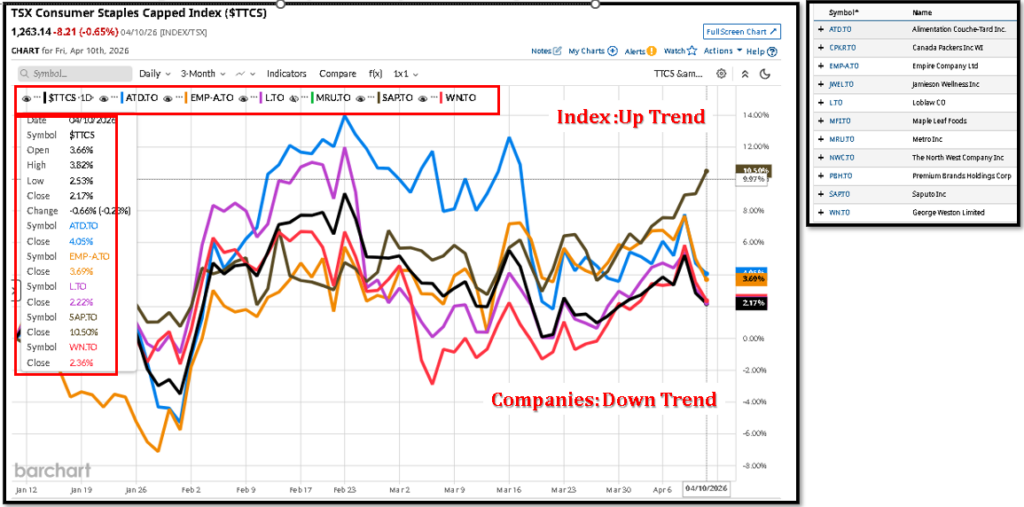
  • Consumer Staples Index ($TTCS) 3M daily

    S&P/TSX Consumer Staples Index moving opposite companies in 3 month daily chart

    Consumer Staples is a small sector on the TSX (only ~3.3% of the composite), so a handful of large-cap movers like Couche-Tard (ATD) and Loblaw (L) dominate the index weight. If those two move in one direction and mid-caps like Saputo or Jamieson move in another, the index can appear to diverge from most of its members — a weighted average masking dispersion underneath.

  • Canadian Tire Corp (CTC-A.TO): New Share Price Record

    Summary of likely drivers for CTC-A.TO’s 10-day rise (April 1–11, 2026):

    • Earnings beat and strong Q4 results announced Feb 19 (investor momentum and analyst upgrades continuing into April).
    • Multiple analyst price-target raises in Feb–Apr improving sentiment.
    • Stock hit new 52-week highs on April 9–10, which can attract momentum buyers and ETFs that track top performers.
    • Steady, above-average volume on key up days (shows genuine buying interest rather than a single trade).
    • No single April 8 material corporate filing was found; movement appears sentiment/technical-driven rather than a discrete news catalyst.
  • U.S. and Iran begin talks amid war’s fragile ceasefire

    The United States and Iran began negotiations Saturday in Pakistan, days after a fragile, two-week ceasefire was announced, as the war that has killed thousands of people and shaken global markets entered its seventh week.

    Iran’s state-run news agency said three-party talks had begun after Iranian preconditions, including a reduction in Israeli strikes on southern Lebanon, were met, and after U.S. and Iranian officials met separately with Pakistani Prime Minister Shehbaz Sharif. There were no immediate further details, nor U.S. comment.

    The U.S. delegation led by Vice President JD Vance and the Iranian delegation led by Parliament Speaker Mohammad Bagher Qalibaf were discussing how to advance the ceasefire already threatened by deep disagreements and Israel’s continued attacks against the Iranian-backed Hezbollah in Lebanon.

    “I cannot say whether they are sitting in the same room or in separate rooms, but talks have started and are progressing well,” said one Pakistani official with knowledge of the peace efforts, speaking on condition of anonymity because they were not authorized to talk to the media.

    Iran sets ‘red lines’ including compensation for strikes

    Iran doubled down on parts of its earlier proposal, with its delegation telling Iranian state television it had presented some of the plan’s ideas as “red lines” in meetings with Sharif. Those included compensation for damage caused by the U.S.-Israeli strikes that launched the war on Feb. 28 and releasing Iran’s frozen assets.

    A man visits the grave of a friend who was killed in an Israeli airstrike in Tyre, Lebanon. So far the war has killed at least 1,953 in Lebanon alone.Chris McGrath/Getty Images

    The war has killed at least 3,000 people in Iran, 1,953 in Lebanon, 23 in Israel and more than a dozen in Gulf Arab states. Iran’s chokehold on the vital Strait of Hormuz has largely cut off the Persian Gulf and its oil and gas exports from the global economy, sending energy prices soaring. Attacks have caused lasting damage on infrastructure in half a dozen countries in the Middle East.

    In Tehran, residents told The Associated Press they were skeptical yet hopeful about the talks after weeks of airstrikes left destruction across their country of some 93 million people. Some said the path to recovery would be long.

    “Peace alone is not enough for our country, because we’ve been hit very hard, there have been huge costs,” 62-year-old Amir Razzai Far said.

    Meanwhile, Israel pressed ahead with strikes in Lebanon after saying there is no ceasefire there. Iran and Pakistan have disagreed. The Lebanese state-run news agency reported at least three people killed. There were no reported strikes in the afternoon.

    Officials posture over key issues ahead of talks

    U.S. and Iranian officials claimed leverage and issued new demands and preconditions as talks approached. U.S. President Donald Trump posted repeatedly on social media leading up to Saturday, saying Iranian officials “have no cards” to negotiate with.

    “The only reason they are alive today is to negotiate!” he wrote.

    He accused Iran of using the Strait of Hormuz, a key artery for global energy supplies, for extortion, and told reporters Friday it would be opened “with or without them.”

    On Saturday, Trump said on social media that the U.S. had begun “clearing out” the strait, but it was unclear whether he was referring to the reported use of mines there or Iran’s broader ability to control the area.

    The Iran war is taking the U.S.-Israel relationship to new heights – and revealing its limits

    Major roads in Islamabad are closed on Saturday as U.S. and Iranian officials arrive to hold separate talks with Pakistan’s prime minister.Akhtar Soomro/Reuters

    Islamabad was deserted as security forces sealed roads and authorities urged residents to stay inside.

    Vance said Friday that the U.S. was optimistic about the talks, but warned: “If they’re going to try and play us, then they’re going to find that the negotiating team is not that receptive.”

    Iranian Foreign Minister Abbas Araghchi had said Tehran was entering negotiations with “deep distrust” after strikes on Iran during previous rounds of talks. Araghchi, who is part of Iran’s delegation in Pakistan, said Saturday that his country was prepared to retaliate if attacked again.

    Iran and the United States outlined competing proposals ahead of the talks reflecting the wide gulf on key issues.

    Iran’s 10-point proposal called for a guaranteed end to the war and sought control over the Strait of Hormuz. It included ending fighting against Iran’s “regional allies,” explicitly calling for a halt to Israeli strikes on Hezbollah.

    The United States’ 15-point proposal includes restricting Iran’s nuclear program and reopening the strait.

    Israel and Lebanon will have direct negotiations

    Smoke rises following an airstrike in Lebanon, as seen from Israeli side of the border on Saturday.Amir Cohen/Reuters

    Negotiations between Israel and Lebanon are expected to begin Tuesday in Washington, Lebanese President Joseph Aoun’s office said Friday, after Israel’s surprise announcement authorizing talks despite the countries lack of official relations.

    Israel wants the Lebanese government to assume responsibility for disarming Hezbollah, much like was envisaged in a November 2024 ceasefire. But it is unclear whether Lebanon’s army can confiscate weapons from the militant group, which has survived efforts to curb its strength for decades.

    Israel’s insistence that the ceasefire in Iran does not include a pause in its fighting with Hezbollah has threatened to sink the deal. The militant group joined the war in support of Iran in the opening days. Israel followed up with airstrikes and a ground invasion.

    The day the Iran ceasefire deal was announced, Israel pounded Beirut with airstrikes, killing more than 300 people in the deadliest day in Lebanon since the war began, according to the country’s Health Ministry.

    Does the war in Iran signal a structural shift for energy markets?

    Mourners pray at the funeral of a family that was killed Wednesday in Israeli strikes on Beirut, before they are buried in the village of al-Sour, northeastern Syria, on Saturday.Ghaith Alsayed/The Associated Press

    Strait of Hormuz remains a sticking point

    Iran’s closure of the Strait of Hormuz has proved its biggest strategic advantage in the war. Commercial vessels have avoided the strait, effectively blocking the passage of oil, natural gas and fertilizer.

    The spot price of Brent crude, the international standard for oil prices, was above $94 on Saturday, up more than 30% since the war started.

    Before the conflict, around a fifth of the world’s traded oil typically passed through the strait on more than 100 ships a day. With the ceasefire in place, only 12 have been recorded transiting.

    Iran has floated the idea of charging ships passing through as part of a peace deal, though the idea has been widely rejected by countries including the United States and Iran’s neighbor Oman.

    Trump posts about ‘clearing’ Strait of Hormuz

    Trump on Saturday posted on social media that the United States military has started to clear the Strait of Hormuz, and that all of Iran’s minelaying ships have been sunk. “We’re now starting the process of clearing out the Strait of Hormuz,” Trump wrote in a Truth Social post, adding that “all 28” of Iran’s “mine dropper boats are also lying at the bottom of the sea”.

    Minutes before Trump’s post, reports started to emerge about the presence of U.S. naval ships in the strait.

    An Axios journalist, citing an unnamed U.S. official, posted that “several” U.S. ships had crossed the strait on Saturday, though Iranian state TV soon after reported a denial from an official with Iran’s military.

    Trump has repeatedly said that American forces have destroyed Iran’s navy and air force while crippling its ballistic missile and nuclear programs.

    But fear of Iranian attacks on shipping over the past several weeks has effectively closed the Strait of Hormuz, a critical conduit for global oil supplies. Throttling the strait has disrupted global energy markets.

    U.S. gasoline prices have spiked even though most of the oil that flows through the waterway does not go to the United States.

  • Canada’s economy adds 14,000 jobs in March after February’s whopping losses

    Canada’s economy added a modest 14,000 jobs in March, Statistics Canada said on Friday, clawing back a fraction of the sharp job losses seen during the first two months of the year.

    The data agency’s previous Labour Force Survey from February showed a loss of 84,000 jobs, a result that was largely a surprise to economists and analysts.

    Given the earlier losses, “no one is going to mistake this small back-up as a sign of strength,” wrote Douglas Porter, chief economist at Bank of Montreal, in a note to clients.

    “Still, even a small plus sign is a positive, as is the stable jobless rate,” wrote Porter. The unemployment rate was unchanged at 6.7 per cent, and there was little variation in the number of full- and part-time employees in March.

    Employment was up in the natural resources industry and the “other services” industry, which includes sectors like personal and repair services. Jobs declined in finance, insurance, real estate, rental and leasing.

    The number of private and public sector workers was little changed, though the number of workers in the public sector has been growing at a faster rate on a yearly basis.

    Average hourly wages were up 4.7 per cent, or $1.68, for a total average hourly wage of $37.73, which Statistics Canada noted is the highest growth rate for wages since October 2024.

    “The only really new news here is that wages seemingly popped, which the Bank of Canada will keep on eye on, particularly as it is already on high alert for signs of any spillover from higher energy prices to broader inflation,” wrote Porter.

    The Bank of Canada’s next interest rate announcement is on April 29.