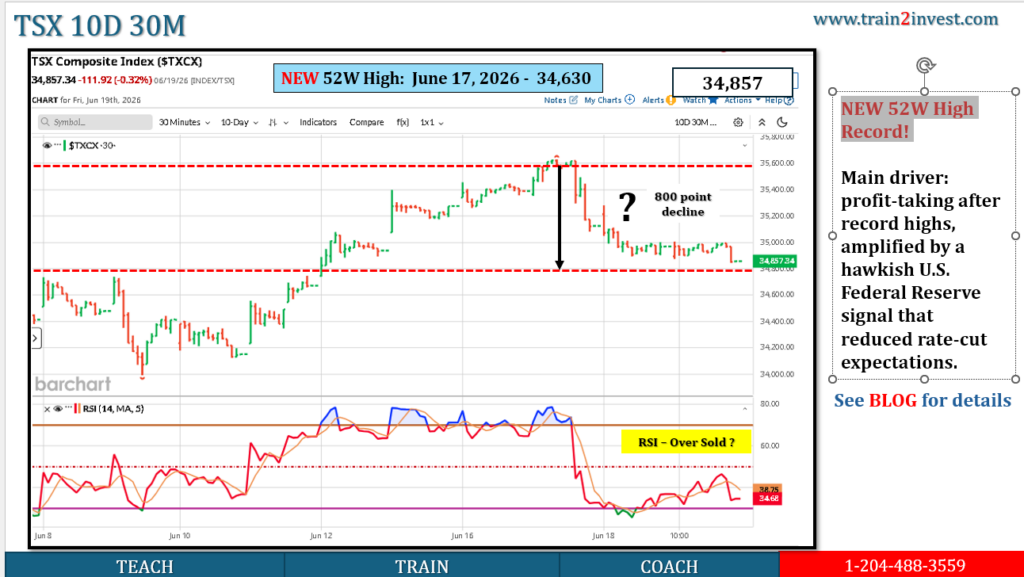
TSX fell for three straight sessions after a record close on June 16, 2026, dropping from 35,389.58 to 34,857.34 by June 19: -532.24 points / -1.5%.
Main driver: profit-taking after record highs, amplified by a hawkish U.S. Federal Reserve signal that reduced rate-cut expectations.
TSX-specific pressure came from commodity-linked sectors: lower oil and gold hit energy and materials/mining shares.
June 19 weakness was concentrated in basic materials, with gold miners such as Alamos Gold and Agnico Eagle weighing on the index.
The decline looks like a valuation/rate/commodity reset, not evidence of a broad Canadian recession shock by itself.
TSX Move: June 17–19, 2026
Date
TSX Close
Daily Change
Main Reported Driver
June 16
35,389.58
+113.94 / +0.3%
Record high, helped by financials and metal miners
June 17
35,125.11
-264.47 / -0.8%
Fed hawkishness; resource and industrial weakness
June 18
34,969.26
-155.85 / -0.4%
Lower oil and gold; higher-rate concerns
June 19
34,857.34
-111.92 / -0.3%
Basic materials/gold miners weighed on TSX
Total from June 16 close to June 19 close: -532.24 points = -1.50%
Key Drivers
1. Fed rate shock hit equity valuations
The immediate trigger was the U.S. Federal Reserve’s more hawkish tone. Markets interpreted the Fed message as reducing the odds of rate cuts and increasing the possibility of higher rates later in 2026. That matters for the TSX because higher U.S. rates usually pressure valuation multiples, especially after a strong rally.
This was not just a Canada issue. U.S. equities also sold off on June 17 after traders increased bets on a potential Fed hike.
2. TSX was vulnerable because it had just hit a record high
The TSX had reached a record close on June 16 at 35,389.58. After a record run, even a modest macro surprise can trigger profit-taking. The June 17 decline was described as a pullback from that record high.
3. Commodity weakness hit Canada harder than the U.S.
The TSX has heavy exposure to energy, materials, financials, and industrials. On June 18, the decline was linked directly to lower oil and gold prices, plus the Fed’s hawkish stance. That combination is negative for a commodity-linked index because it hits earnings expectations for miners and energy producers while also pressuring valuation multiples.
4. Gold miners dragged the index on June 19
On June 19, the pressure was mainly in basic materials, with gold miners weighing on the index. Reports cited Alamos Gold down about 18% and Agnico Eagle down about 2% as notable drags.
5. Weaker Canadian macro signals added pressure
The Canadian dollar fell to a 14-month low on June 19, pressured by weaker core retail sales, falling oil prices, and a stronger U.S. dollar after the Fed’s hawkish stance. That reinforced the message of softer domestic demand and tighter financial conditions.
What It Means
This was mainly a three-factor pullback:
Factor
Impact on TSX
Hawkish Fed
Higher discount rates; lower equity multiples
Lower oil/gold
Direct pressure on TSX energy and materials
Record-high starting point
Profit-taking after strong run
The TSX decline was not large in percentage terms: about -1.5% over three sessions. The pattern suggests a controlled pullback rather than a market breakdown.
Scenarios
Scenario
What Happens Next
TSX Implication
Bull
Oil/gold stabilize; Fed hike fears fade
TSX retests 35,000–35,400
Base
Rates stay uncertain; commodities mixed
TSX trades sideways around 34,700–35,200
Bear
Fed hike odds rise; gold/oil fall further
TSX tests lower support near 34,400–34,600
What Would Disprove the “Normal Pullback” View
The decline would become more concerning if:
TSX breaks below the early-June low area near 34,100–34,400.
Financials join materials and energy in sustained weakness.
Oil and gold continue falling together.
U.S. yields keep rising and Fed hike odds increase further.
Canadian consumer/economic data deteriorates beyond retail sales weakness.
Actionable Takeaways
Treat June 17–19 as a rate-and-commodity-driven pullback, not a standalone recession signal.
Watch gold miners, energy stocks, and financials for confirmation.
The key macro variable is now U.S. rate expectations; the key TSX-specific variable is commodity price direction.
A recovery likely requires either lower bond yields, stabilizing oil/gold, or renewed strength in financials.
The Canadian dollar has been underperforming the US dollar since the onset of the Iran war.
The loonie softness is largely due to US dollar strength rather than domestic fundamentals, according to analysts.
Expectations of US Federal Reserve interest rate increases are amplifying the greenback’s strength.
With the Canadian dollar slumping against the US dollar, 2026 isn’t turning out the way many analysts expected. Coming into this year, forecasters had a strong outlook for the Canadian dollar, amid expectations of a healthy economy and Federal Reserve interest rate cuts in the United States. But the Iran war upended this. The Canadian economy is struggling, and investors now think the Fed could raise rates before 2026 is over. Not only that, but analysts say the US dollar has benefited from investors using it as a haven to mitigate war-related volatility.
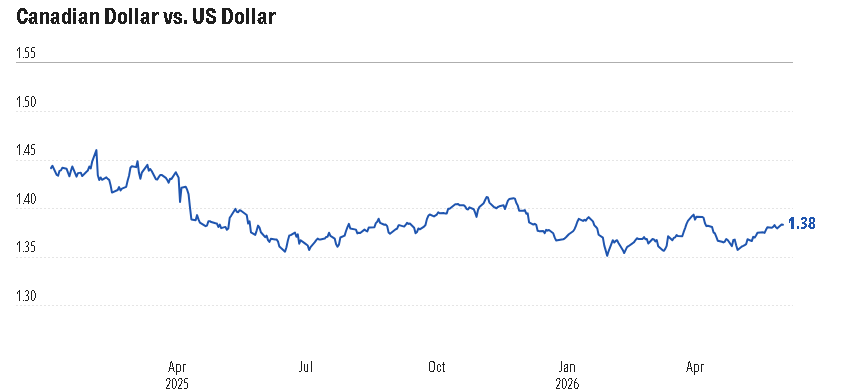
The Canadian dollar was trading at C$1.39 against the US dollar on June 4, having fallen from C$1.35 just a week after the Iran war broke out on Feb. 28. A once-bullish outlook has turned dour. Analysts expect the loonie to continue to lag in the near term as economic resilience and expectations of higher-for-longer interest rates in the US continue to provide tailwinds for its currency.
The big picture is that the Canadian dollar’s fortunes are being driven more by US than Canadian dynamics, according to analysts. “We estimate around 85% of the move in [the Canadian dollar] has been driven by broader US dollar strength—due both to the rise in geopolitical risk and better-than-expected data [in the US],” says Sarah Ying, head of FX strategy at CIBC.
Currency analysts attribute only a limited share of the loonie’s recent weakness to domestic factors, such as a faltering labor market, slower GDP growth, and fading expectations for interest rate hikes at the Bank of Canada. Canada’s economy unexpectedly shrank in the first quarter, following a larger contraction in the fourth quarter of 2025, marking two consecutive quarters of negative economic growth. This is the technical definition of a recession.
The Loonie Lags as Iran War Jitters Fuel US Dollar’s Surge
The Canadian dollar started the year at C$1.37 against the US dollar, and it drifted higher to C$1.35 in February, boosted by growing expectations for a Bank of Canada rate hike and strong momentum in commodities, particularly gold. However, the script flipped when the Iran war erupted. War-driven oil price volatility prompted investors to seek refuge in the US dollar.
Nick Rees, head of macro research at Monex Canada, says that while the currencies of all the Group of 10 countries have slid against the US dollar, “the loonie is the worst-performing.”
Weaker Domestic Economic Data
Analysts say that some of the loonie’s weakness comes from concerns that domestic economic growth is being held back by a softening labor market and an uptick in inflation. “Relatively soft economic data early in May contributed to underperformance,”says Tom Nakamura, currency strategist and co-head of fixed income at AGF Investments.
In contrast, the US economy has shown signs of resilience, according to CIBC’s Ying. “Recent data suggests the American job market has stabilized, and inflation is running a bit higher than expected, partly because of rising energy costs,” she says.
Divergent Central Bank Rate Paths
With the Canadian economy softening and the US economy remaining healthy (though with high inflation), the outlook for monetary policy in both countries is heading in opposite directions.
The oil shock from the Iran war “has created some material concern that persistent inflation could not only prevent the Fed from cutting rates, but also compel it to hike rates to moderate inflation expectations,” says AGF’s Nakamura, who adds that this has helped drive up the US dollar.
Meanwhile, inflation in Canada has been showing signs of cooling, evidenced by core CPI (which excludes food and energy) hovering around 2%. “While higher energy prices could push core inflation up slightly, we don’t see an urgent need for the Bank of Canada to raise interest rates this year,” says CIBC’s Ying.
The resulting higher rates in the US and steady rates in Canada “tend to strengthen the US dollar against other currencies, including the Canadian dollar,” Ying says.
What Needs to Change to Lift the Loonie?
For the Canadian dollar to reverse its course and close the gap with the US dollar, analysts say that certain catalysts must materialize. The Canadian dollar could appreciate if “the Strait of Hormuz opens, with the expectations that it will remain open and [the West Texas Intermediate crude oil price] normalizes to USD 80-USD 85,” says CIBC’s Ying. Other potential key drivers include deteriorating US employment data, which would require the Fed to ”remain patient for longer,” or certainty about the Canada-United States-Mexico Agreement.
Monex’s Rees says the Canadian dollar could see a reprieve in the third quarter, when he expects domestic economic indicators to improve, following a resolution to the war in the Middle East and greater clarity around the trade deal with the US. “At that point, we see a solid case for loonie gains, with the economy starting from a weaker base, meaning greater scope for improving data to fuel the Canadian dollar upside,” he says.
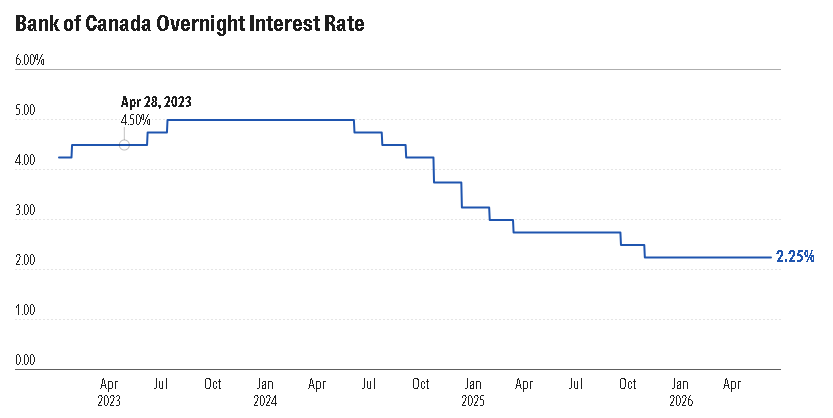
The Bank of Canada left its overnight interest rate unchanged, marking a fifth consecutive hold.
Policymakers highlighted the complexity of responding to opposing forces of slower growth and higher inflation from the Iran war.
Some analysts see a slight shift in the Bank’s tone away from rate hikes, but most believe policy will be on hold throughout 2026.
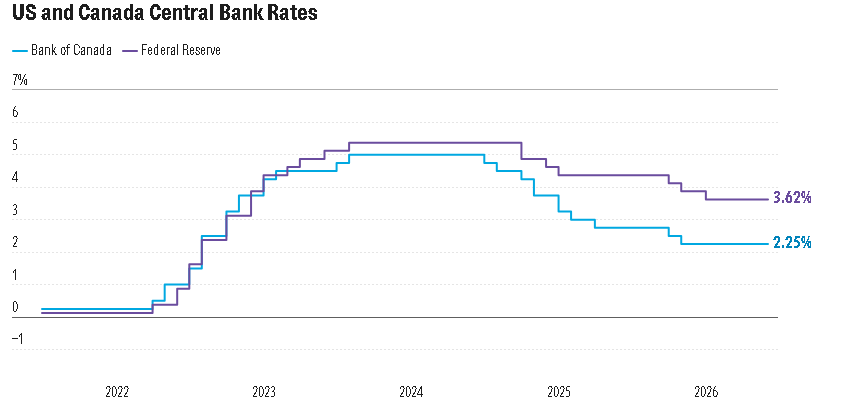
For the fifth time in a row, the Bank of Canada held its overnight interest steady at 2.25% on Wednesday, as it juggles the economic impact of Iran war-driven energy prices and trade uncertainty. Analysts say the central bank is in no hurry to change rates, and this hold could be extended throughout the year.
In its policy statement, the Bank underscored the challenge of balancing weaker-than-expected first-quarter economic activity with a reacceleration in inflation to 2.8% in April from 2.4% the month before, stemming from the war in the Middle East. “Economic weakness combined with rising inflation is a dilemma for monetary policy,” said Bank Governor Tiff Macklem at the press conference following the announcement. “Raising rates to dampen inflation could further slow the economy. Easing rates to support growth increases the risk that higher inflation becomes persistent.”
For that reason, the Governing Council decided to look past the Iran war’s near-term inflationary effects. But policymakers reiterated their readiness to enact multiple rate hikes conveyed in the April Monetary Policy Report: “if energy prices stay high, we will not let their effects become broad-based persistent inflation.” At the same time, the Bank acknowledged that it may need to cut rates to support the economy, should “the United States impose significant new trade restrictions on Canada.”
The Bank cut the overnight rate by 1 percentage point over the course of 2025 before moving to the sidelines in December.
Following the announcement, most analysts—including those at Vanguard, BMO, TD Economics, and CIBC—say that despite energy-driven inflation, economic weakness and trade uncertainty will prevent the Bank from hiking rates this year. In contrast, analysts at Mackenzie and IG Wealth forecast that a rate cut could come as early as later this year
Markets were little changed by the news. The Canadian dollar rose 0.31% against the US dollar to C$1.39, or 0.71 US cents. The S&P/TSX Composite Index edged 0.17% lower to 34,369.55, while the Morningstar Canada Index slid 0.26% to 6,089.99. The yield on Government of Canada 2-year bonds ticked 0.02 percentage points lower to 2.82%.
Here’s a closer look at commentary on the Bank of Canada’s decision and the outlook for interest rates.
Bank of Canada on Hold Through 2026
“Very little new information from the Bank of Canada, as the June policy statement and opening statement were similar to April’s. The extra line about the economy being ”weak” is a touch more dovish, but there’s still concern about the potential for rising inflation from higher energy prices. We continue to expect the Bank of Canada to stay on hold through the rest of 2026.”
—Benjamin Reitzes, managing director, Canadian rates and macro strategist at BMO Economics
No Rate Move Expected Until Next Year
“The slightly dovish shift [a tilt towards easing policy] in language from the Bank of Canada today provides support to our forecast that it will leave interest rates unchanged this year … Governor Tiff Macklem has tweaked some of the key phrases in his opening statement to the press conference. Back in April, Macklem said that ‘if the economy evolves broadly in line with the base case, changes in the policy rate can be expected to be small.’ Today, he notes that ‘economic weakness combined with rising inflation is a dilemma for monetary policy’ and that ‘holding the policy rate unchanged balances those risks.’
“That tweak makes us a bit less concerned about the possibility that the Bank might have wanted to raise interest rates modestly simply to position itself back in the middle of its 2.25% to 3.25% neutral range estimate, leaving us comfortable with our view that the Bank is unlikely to move in that direction until at least early 2027.”
—Stephen Brown, chief North America economist at Capital Economics
Bank of Canada Appears Set to Stay on Hold
“Overall, we view today’s communication as highlighting a very patient central bank that has plenty of time to wait and see how risks to the economy play out. We continue to see no change in interest rates this year, and that rates at their current level should support a recovery in the economy later this year and into 2027, assuming some of the uncertainties regarding oil prices and trade lessen during that time period.”
—Andrew Grantham, senior economist at CIBC Capital Markets
The BoC Is in No Hurry to Move Rates
“For the moment, the Governing Council seems very comfortable leaving rates unchanged. It’s a bit surprising that Macklem largely repeated the language used in April, given the persistent weakness in Canadian economic indicators and the tame nature of underlying inflation. That said, markets aren’t taking the bait this time. Despite his commentary on the possibility of consecutive rate hikes, Government of Canada bond yields are slightly lower on the day.”
—Royce Mendes, managing director and head of macro strategy at Desjardins Capital Markets
Rate Hike Expectations Could Give Way to a Cut
“Unfortunately for those looking for a strong signal in either direction, the Bank didn’t say much. Coming off two disappointing quarters of negative GDP growth on an annualized basis and three negative quarters out of the last four, the Bank couldn’t simply overlook the deceleration in economic activity. And while last month’s jobs data was an encouraging sign, excluding the COVID period, the 12-month average job gains are still near the lowest in 10 years. These are economic conditions that the Bank can’t ignore. And by its statement, it didn’t and at the same time, gave nothing away.
“Nonetheless, while the Bank’s mandate is price stability, with a target of 2% inflation +/- 1%, given the economic conditions, there is room for the Bank of Canada to cut the overnight rate and provide some stimulus. This runs counter to other central bank postures, in particular what is becoming the prevailing view that the US Federal Reserve may be forced into a hike before the end of the year. However, the Canadian economy is not the US economy, and the Bank recognizes that. Views for the Bank of Canada to raise its overnight rate once before the end of the year should quickly turn into expectations for a cut.”
“The statement was largely a copy of April’s, noting both risks of a hike and cut under various scenarios. The Bank of Canada continues to emphasize it will not let inflation move materially higher, but also continues to stress it views the hostilities in the Middle East as temporary and will look through. On the other hand, the Bank continues to be concerned over the outcome of USMCA [United Sates-Mexico-Canada Agreement], and disruptions in the agreement to long-established supply chains could necessitate some easing in policy rates.
“The Bank of Canada appears to be on hold for the foreseeable future. Mackenzie continues to see significant risks to USMCA implementation as well as other domestic macro headwinds, and expects the Bank to cut rates before year end.”
—Dustin Reid, chief strategist, fixed income at Mackenzie Investments
Rate Hold to Last Through the Year
“The outlook remains highly uncertain. Oil prices have come off their peaks but are still high as uncertainty about the course of the conflict in the Middle East persists. On the other hand, negotiations around the CUSMA review have yet to get started, casting a pall over trade prospects. Recent data suggest a second-quarter bounce-back in growth, but one that is insufficient to absorb all of the excess capacity in the economy. Given the competing forces on inflation, we expect the Bank of Canada to stay on hold through the balance of the year.”
—Andrew Hencic, director and senior economist at TD Economics
A Rate Hike Is Unlikely This Year
“Elevated uncertainty and the energy price shock associated with the US–Iran conflict are likely to weigh on global demand, shaping the backdrop against which the Bank of Canada is setting its policy rate. Canada stands out among advanced economies in that higher oil prices may provide a modest near‑term boost to GDP, on the order of 10 to 20 basis points, reflecting its position as a net energy exporter.
“However, this growth impulse arrives alongside an inflationary shock. Higher energy prices are pushing up headline inflation and raising the risk that the disinflation process stalls in the near term. For the Bank of Canada, this creates a more complicated policy environment. While growth may receive a temporary lift, inflation dynamics limit the central bank’s flexibility. In our view, this trade-off makes it more difficult for policymakers to pivot toward rate cuts, reinforcing our expectation that the Bank of Canada’s policy rate will remain unchanged at 2.25% through year‑end 2026.”
—Ashish Dewan, investment strategist at Vanguard Canada
Vice President JD Vance told Fox News on Saturday that “we’re not seeing any evidence that the Iranians are still closing down the Strait of Hormuz.”
“It is going to take some time to clear those mines, though,” Vance told “Fox & Friends Weekend.”
“We got 16 million barrels out of the Strait of Hormuz in just the last 24 hours. That is basically to where it was before the war even started. And so that suggests that the Straits really are open,” Vance also said.
Iran MOU: Yes, it appears valid/in effect, but it is fragile and provisional, not a final peace treaty. Reuters reports U.S. and Iranian officials said it was digitally signed and Iran said it was already in effect as of Wednesday, June 17, 2026.
Legal status: It is best treated as a 60-day ceasefire / negotiation framework, not a comprehensive settlement. A U.S. official said parties could still walk away and sequencing is key.
Strait of Hormuz:Not clearly “closed” in a fully enforced physical sense, but it is high-risk and severely disrupted. Iran/IRGC has declared closure again, while U.S. officials dispute that an actual shutdown is occurring.
Shipping evidence is mixed: UKMTO/JMIC said on June 18 the maritime threat level had been reduced to moderate after reopening intentions, but separate tracking showed very limited or no active commercial outbound transits early June 20.
Market reading: Treat the MOU as still alive but under stress; treat Hormuz as functionally constrained, not safely normalized.
Direct Answer
1. Is the Iran MOU valid?
Yes — currently valid, but weak.
The reported MOU was signed by U.S. President Donald Trump and Iranian President Masoud Pezeshkian, according to Reuters, and Iran said it was already in effect as of June 17. The agreement reportedly extends the ceasefire for 60 days and is meant to allow talks toward a final truce.
However, it is not a durable final agreement. Reuters also reported that a U.S. official said either side could still walk away, and implementation depends heavily on sequencing.
Conclusion: Valid on paper; fragile in practice.
2. Is the Strait of Hormuz closed?
Not conclusively closed in the sense of a complete, verified, enforced shutdown. But it is not normal either.
Iran’s military/IRGC has declared the Strait closed again, citing alleged ceasefire violations. Reuters reported Iran’s announcement via Mehr on June 20.
But Axios reported that a senior U.S. defense official said there were no signs of Iranian military activity indicating an actual closure.
There is also evidence of some vessel movement: three Indian-flagged oil tankers reportedly crossed the Strait and headed to India.
Conclusion: The correct wording is: Hormuz is threatened, restricted, and risky — not clearly confirmed as fully closed.
Practical Market Interpretation
Question
Best Current Assessment
Confidence
Is the MOU valid?
Yes, but provisional and fragile
Medium-high
Is the MOU a final peace deal?
No
High
Is Hormuz fully closed?
Not confirmed
Medium
Is Hormuz back to normal?
No
High
Is oil risk premium still justified?
Yes
High
TSX / Market Impact
Short term: Bullish for oil volatility, energy risk premium, gold risk hedge, and defence/security sentiment. Negative for airlines, transport, chemicals, and consumer discretionary if crude spikes.
Long term: If the MOU survives and Hormuz traffic normalizes, the oil risk premium should fade. If the MOU breaks, Brent could reprice sharply higher.
What Would Disprove This View
The “Hormuz not fully closed” view would be wrong if confirmed AIS, UKMTO, Lloyd’s List, or naval sources show sustained zero commercial transit plus active Iranian enforcement.
The “MOU still valid” view would be wrong if either Washington or Tehran formally withdraws, suspends implementation, or resumes direct military action.
Bottom line: The MOU is valid but fragile. The Strait of Hormuz is not reliably open in a normal commercial sense, but a full enforced closure is not yet independently confirmed.
The US/Iran MOU is a 14-point interim framework released by the United States on June 17, 2026, after an agreement reached over the prior weekend. [1]
Key points:
Iran commits not to build a nuclear weapon, though reports note this repeats a long-standing Iranian position rather than creating a new pledge. [2]
Both sides commit to negotiating a final deal within 60 days, meaning the MOU is not the final settlement. [3]
The framework reportedly codifies fragile ceasefires involving Iran and Lebanon and sets out areas for further negotiation. [5]
The agreement leaves major contentious issues unresolved, so execution risk remains high. [6]
Bottom line: this appears to be a de-escalation framework, not a comprehensive peace or nuclear deal. Its market significance depends on whether ceasefires hold, whether a final deal is reached within 60 days, and whether oil/geopolitical risk premiums fall.
The US/Iran MOU appears to affect Israel/Lebanon mainly through the Lebanon–Hezbollah front, but the details remain contested.
Lebanon ceasefire pressure: The agreement is expected to push toward ending the war in Lebanon, which could reduce immediate regional escalation risk. [1]
Hezbollah/Iran concern: Critics argue the MOU effectively recognizes Iran’s role in Lebanon and may strengthen Hezbollah’s political position by treating it as a successful Iranian proxy. [2]
Israeli security concern: Some Jewish/Israel-aligned groups argue the Lebanon provision does not clearly recognize Israel’s right to self-defense or Lebanon’s sovereignty. [3]
Implementation dispute: Iran reportedly says the agreement requires Israel to stop fighting Hezbollah and withdraw from south Lebanon, while Israeli leaders have not accepted that framing. [6]
Strategic risk: If Iran receives economic relief, some analysts warn it could rebuild missile, drone, or nuclear capabilities. [4]
Bottom line: de-escalation possible, but Israel may view the MOU as limiting its freedom of action while strengthening Iran/Hezbollah leverage.
Grocery retailer Empire Co. Ltd. EMP-A-T +3.04%increase wants to compete more for price-sensitive Canadian shoppers, with plans to open dozens of new discount stores in the coming years.
The Stellarton, N.S.-based retailer, which owns chains including Sobeys, Safeway, IGA, Farm Boy and FreshCo, announced on Thursday that it is accelerating investments in its store network. The company will open 20 new stores in the current fiscal year, and a total of 70 new locations over the next three years. More than three-quarters of those will be discount stores.
“We have a lot of room to grow in discount, without cannibalization of our network,” said president and chief executive officer Pierre St-Laurent on a conference call Thursday to discuss the company’s fourth-quarter earnings.
Canadians, who have been grappling with food affordability and stubborn inflation, have been increasingly turning to discount stores in an attempt to rein in household budgets. More recently, rising gas prices spurred by the conflict in the Middle East have also affected consumer confidence.
Mr. St-Laurent said he is hoping the initial deal to end the war, signed by the United States and Iran on Wednesday, will lead to lower fuel prices that will provide some relief to consumers.
Empire opened five new stores in its fourth quarter, four of which were discount FreshCo locations. Its plans include expanding the FreshCo banner in Atlantic Canada.
Including renovations and store conversions, Empire plans to complete 90 real estate projects annually, an increase of 25 per cent compared to fiscal 2025 and 2026, Mr. St-Laurent said.
In addition to the discount expansion, Empire has long-term plans to expand its pharmacy business, including by adding more pharmacy locations to grocery stores as they are renovated. Empire owns the Lawtons drugstore chain in Atlantic Canada, as well as operating pharmacies inside some of its existing grocery stores. That part of the business was not a focus for the company in the past, but represents a “meaningful opportunity” for future growth, Mr. St-Laurent said.
On Thursday, Empire reported higher sales and profits in the fourth quarter ended May 2 and increased its quarterly dividend paid to shareholders.
The company saw sales increase in both its discount and conventional grocery banners. Profits jumped by 22.5 per cent as the stores continued to make progress on “efficiencies,” including preventing food waste and offering a better mix of promotions.
The company reported net earnings of $212-million or 94 cents per share, compared with $173-million or 74 cents in the same period last year. That beat analysts’ expectations of $199-million or 87 cents, according to consensus estimates from S&P Capital IQ.
Sales grew to $7.8-billion in the quarter, up 2.2 per cent compared with the same period last year.
At the grocery stores, same-store sales – an important industry metric that tracks sales growth excluding the impact of newly opened locations – grew by 1.5 per cent year-over-year.
The company announced it will raise its quarterly dividend to 24.25 cents per share, up from 22 cents.
Empire is continuing to fight cost-increase requests from its suppliers, who have been asking retailers across the industry to help them offset the effect of higher fuel prices caused by the Middle East conflict.
“Consistent with our approach on tariffs, we are pushing back on fuel-related surcharges,” Mr. St-Laurent said during the call, referring to similar cost-increase requests that came last year after Canadian counter-tariffs on U.S. imports, applied in reaction to the Trump administration’s tariffs on Canadian goods, also put pressure on the cost of food.
The pushback has helped to keep Empire’s price increases lower than overall food inflation in Canada, according to the company.
“We know many consumers remain stretched,” Mr. St-Laurent said.
The Globe and Mail first reported in April that suppliers such as Maple Leaf Foods Inc., Tree of Life and Unilever PLC had told grocers they planned to apply either surcharges or overall cost increases amid the surge in fuel prices.
Competitors Loblaw Cos. Ltd.L-T +0.32%increase and Metro Inc.MRU-T +0.27%increase have also previously said they were declining these requests – a pattern that has raised concerns among small independent grocers about an imbalance in the industry, as they lack the size and market power to push back in the same way.
“We’re not accepting anything,” chief customer officer, Luc L’Archevêque, said during the call.
Earlier this year, the company shut down its Voilà e-commerce facilities in Alberta and took a $746-million writedown on the business after the financial results from its e-commerce strategy fell short of expectations.
Since ending its exclusive relationship with e-commerce technology partner Ocado, Empire has struck new partnerships with third-party delivery services Instacart, Uber Eats and Door Dash, which contributed to 6-per-cent e-commerce sales growth in the fourth quarter.
Online sales growth lagged competitors during the quarter, and slowed because of the Alberta closings, Mr. St-Laurent said. He added that Empire is expecting the economics of its e-commerce business to improve in the year ahead.
This comes directly from ISC’s official 2026-2027 Departmental Plan. It breaks down as roughly $23.79 billion for the core responsibility (Indigenous Well-Being and Self-Determination) plus internal services.
Recent Context and Trends
2025-26 forecast: Around $27.1 billion (or ~$25 billion in some earlier plans).
ISC (and the related Crown-Indigenous Relations and Northern Affairs Canada, or CIRNAC) saw significant growth in prior years, with combined spending reaching ~$63 billion in FY 2024 (about 12% of the federal budget in some reports). Much of this consists of transfer payments, grants/contributions for services like health, education, housing, social programs, and infrastructure on reserves.
Budget 2025 adjustments: ISC faces ~2% reductions (around $494 million annually starting 2026-27, alongside CIRNAC), which is lighter than broader government cuts. This contributes to multi-year savings targets, though the departmental plan figures above do not yet fully reflect finalized implementation of those cuts.
These funds primarily support services for First Nations, Inuit, and Métis peoples, including health care, education, child/family services, housing, water infrastructure, governance, and economic development. A large portion flows as transfers to communities or organizations rather than direct federal administration.
Notes on “Cost to Taxpayers”
This is direct federal departmental spending funded by Canadian taxpayers via the federal budget.
Total broader federal Indigenous-related spending (including CIRNAC, other departments, settlements, etc.) is higher and has grown substantially in recent years (e.g., nearly tripling from ~$11B in 2015 to over $32B by some 2025 estimates).
Figures can vary between Main Estimates, actual expenditures, forecasts, and supplementary estimates due to one-time items, statutory spending, or adjustments (e.g., Jordan’s Principle, settlements).
For the most precise/current details, check the full ISC 2026-27 Departmental Plan on the linked Canada.ca site or the latest Public Accounts of Canada. Spending is transparent but complex due to distinctions-based (First Nations/Inuit/Métis) and transfer-heavy nature.
SpaceX’s record-setting IPO is creating a financial windfall for thousands of the company’s current and former employees who received stock as part of their compensation.
Workers who hold stock in non-public companies are subject to restrictions that can keep them from selling those shares under most circumstances before an IPO occurs. Once the stock goes public, it starts a timeline under which they can begin to sell some of those shares as so-called “lock-up periods” gradually allow employees to sell shares in tranches that expand over time.
The ranks of SpaceX workers who will see an influx of wealth as a result of the IPO include not only those who design the rockets and satellites that have made the company famous, but also baristas, janitors and other workers who helped keep the company running.
FOX Business spoke with workers outside of SpaceX’s facility in Hawthorne, California, about their plans for the monumental IPO turning into a reality.
One SpaceX employee, who said that he’s a process planner, said that he wants to “try to stay healthy” and that the IPO is “a beautiful thing… I mean, Elon is the best. Go Elon!”
Another SpaceX employee said that, “I’ve been a millionaire for a while, but it’s always nice to have money. It’ll be great when the lock-up period is out, of course, and we can actually sell some of it and that’ll feel a little more into the wealth, but it’s a great day.”
Juan Hernandez, who previously worked as a welder at SpaceX, told CBS News that when he was first hired by the company in 2015 he was offered $10,000 in stock. He explained that it “wasn’t a big deal” to him at the time and, “I didn’t know it was gonna be this big, at this point.”
Hernandez, who now works at Blue Origin after a 10-year stint at SpaceX, told CBS that he has around 6,500 SpaceX shares that would represent a nearly $880,000 windfall based on the IPO listing price of $135 a share. He added that giving employees stock options encourages them to “perform a lot better because, I mean… it’s their company as well.”
He went on to tell the outlet that he wants to maintain a strong work ethic after the IPO and plans to keep working, and expressed gratitude to Musk for “making all these lives much better and meaningful for their families as well.”
The Wall Street Journal reported that J. André Lavoie, a 63-year-old former SpaceX engineer who moved to Italy five years ago, has shares valued at over $28 million based on the IPO price. Lavoie plans to use the funds to renovate a hotel he purchased and is considering helping others in the community transition from heating their homes with burning wood to cleaner heating sources.
“I don’t want to just die with a pile of money in the bank,” Lavoie told the Journal. He added that the rise in the value of the shares has caused him to reconsider his plans. “Every year the shares have been going up so radically it keeps messing up my life plans.”
The Journal also spoke with 27-year-old Maryellen Musselman, who joined SpaceX in 2022 and worked on a ship used in retrieving rocket parts from the company’s launches that splashed down off the coast of Florida.
Musselman used 10% of her pay to purchase additional shares during the two years she worked at SpaceX and said that while she’s unsure of how quickly she’ll look to sell, saying it’ll likely be “an 11th-hour decision.”
She wants to use the money to help her start a ship repair business in Chesapeake, Virginia, saying that, “Mariners are not usually stock owners in their companies, they’re not always under benefits.”
Tom Mueller, who was hired as SpaceX’s first employee in 2002 and led projects including the Merlin Engine that powers the Falcon 9 rocket, the Raptor Engine that powers Starship and other key propulsion systems, told FOX Business’ “The Claman Countdown” on Thursday that the IPO would be life-changing for employees.
“Elon always said that ‘Your salary is one thing, but it’s the equity that’s gonna be worth something.’ And we are all like, ‘Yeah, okay someday,’” Mueller said. “That day is here. It’s great.”