Statistics Canada said gross domestic product growth was essentially unchanged in July, coming down from a strong second quarter for the economy.
The agency said the result came despite a 1.3-per-cent gain for the construction sector in July, which marked its fourth consecutive month of growth after declines in late 2025 and early 2026.
Non-residential building construction saw its best month since the start of 2022, Statscan said, owing primarily to activity around a new hospital building in Toronto.
Statscan also said a 1.7-per-cent surge in electricity generation, transmission and distribution powered the utilities sector to its strongest month of growth all year. A July heat wave across many parts of the country drove up power demands for cooling, the agency said.
On the other side, declines in July were spread across manufacturing, mining, quarrying and oil and gas extraction, as well as retail and wholesale trade.
Manufacturing’s 0.9-per-cent decrease was the sector’s first drop in four months, Statscan said.
Mining and quarrying took a sharp hit in July, thanks in part to a 6.4-per-cent drop in potash mining – the largest monthly decline since September, 2025. July’s increase in oil sands extraction tempered wider declines in oil and gas.
Retailing activity meanwhile fell off at gas stations in July, which Statscan said coincided with rapidly rising gasoline prices in the peak summer travel season.
Estimates for flat growth to start the third quarter come after Statscan projected an annualized growth rate of 3.3 per cent in the second quarter.
Newly revised data showed GDP was actually up 0.4 per cent in June, compared with earlier estimates of 0.3 per cent.
Statcan’s initial estimates call for the economy to pick back up with a gain of 0.2 per cent in August, but those early figures will be revised next month.
The agency said mining, quarrying and retail trade rebounded in the month, offset by further declines in oil and gas extraction.
The August GDP figures will partially capture the impact of new 50-per-cent U.S. tariffs applied on a range of Canadian goods starting Aug. 22.
“The August pickup reinforces our view that the Canadian economy was enjoying a decent mid-year recovery before the latest U.S. tariffs took effect,” said Peter Shannon, senior economist at KPMG, in a note.
Shannon said he expects the bite from the new U.S. duties to meaningfully hit in September and take full effect in the fourth quarter. KPMG projects GDP will be about half a percentage point lower over the course of a year should the tariffs remain in effect.
Benjamin Reitzes, BMO’s managing director of Canadian rates and macro strategist, said in a note to clients Tuesday that the August advance has him tracking GDP growth of 1.5 to 2 per cent in the third quarter of the year. That’s roughly in line with the Bank of Canada’s forecast for 1.5 per cent in the quarter, he noted.
New tariffs create some roadblocks for the economy, but Reitzes said fiscal policy changes like Ottawa’s move to expand investment incentives will help support growth.
“The Canadian economy continues to hang in there despite the ongoing trade headwinds,” Reitzes said.
The Bank of Canada will get a look at new jobs and inflation data for September, as well as a read of its own quarterly surveys of businesses and consumers, before making its next interest rate announcement on Oct. 28.
Reitzes suggested these data prints will be more impactful for the central bank’s decision than the July GDP release.
The United States and China released Monday reciprocal lists of products worth about US$30-billion each that will see tariff cuts, in a deal expected to boost bilateral trade.
The details came days after Chinese President Xi Jinping met with President Donald Trump in Washington in his first state visit to the U.S. since 2015. The U.S. had already reduced tariffs against China after Trump’s tariffs reached as high as 145 per cent at one point last year, as tensions between the two countries eased.
China’s commerce ministry said in a statement the agreement will help strengthen trade co-operation.
Most country-specific tariffs practically eradicated
The lists included 1,619 items of U.S. goods entering China, ranging from agricultural commodities, personal care products to timber and medical equipment. Coal from the U.S. will also be included.
For Chinese goods exported to the U.S., 77 categories were covered, including fireworks, tableware, glass and wooden Christmas ornaments and soccer balls.
Tariff rates on over 90 per cent of the products would be subject to “most-favoured-nation” levels, the Chinese commerce ministry said, meaning that country-specific tariffs will effectively be eliminated.
U.S. Trade Representative Jamieson Greer said in a separate statement the product lists focused on “nonsensitive goods on each side that could benefit from more favorable tariff treatment.” The deal could help secure market access for U.S. farmers, manufacturers, businesses and workers, while benefiting American consumers with imports from China including household goods and toys, Greer said.
Both countries said they agreed the list may be adjusted later as needed, but amendments were likely to be no more than on an annual basis.
The Chinese commerce ministry said the two countries agreed to further co-operate in the agricultural sector, forming a group under the Board of Trade established in May to optimize bilateral trade.
Sectors of strategic importance for both countries, such as chips, electric vehicles and batteries, were not covered under the agreement.
“This is a positive outcome for these affected products compared to a smaller tariff cut, and could lead to a more significant boost to bilateral trade,” said Lynn Song, chief economist for Greater China at ING Bank.
The lowered tariffs could be a win for U.S. consumer brands, added Jacob Cooke, CEO of WPIC Marketing + Technologies based in Beijing, as some of the products covered by China’s list of U.S. imports included fast-growing categories like hair care, personal care products and infant formula.
The U.S. list for Chinese imports focused more on consumer goods, which could help lower U.S. inflation while also allowing Chinese firms to export more of their overcapacity, said Gary Ng, a senior economist at French bank Natixis.
Some experts said, however, the economic impact at US$30-billion each way may be limited overall.
U.S. exports to China were roughly US$68-billion through the first seven months of this year, while Chinese exports to the U.S. were at around US$270-billion for the first eight months, said Prashant Bhayani, chief investment officer for Asia at BNP Paribas Wealth Management.
A US$30-billion deal each way will be “more meaningful” for U.S. exports to China in terms of percentage share, he said.
China’s trade surplus expected to remain elevated
While the deal did not cover sensitive strategic goods, analysts believe U.S.-China trade will likely continue to recover for the rest of the year after steep U.S. tariffs on Chinese products last year hit bilateral trade.
The U.S. and China last week also reached a two-month extension of the broader trade truce that was set to expire Nov. 10 to January.
China’s trade surplus, which reached a record US$1.2-trillion last year, will likely remain elevated. By August, it stood at about US$800-billion, putting this year’s surplus “on pace to exceed the 2025 record,” according to Ecaterina Bigos, a senior market strategist with BNP Paribas Asset Management.
The U.S. is also investigating China among 16 trading partners in its Section 301 probe on excess industrial capacity and could impose additional tariffs on China when the investigation concludes.
However, with more meetings set between Trump and Xi, including at the Asia-Pacific Economic Cooperation summit in Shenzhen in November and at the Group of 20 summit in Florida in December, Song at ING said he would not expect a major flare-up of trade tensions before year-end.
Exporters welcome the tariff deal
Some Chinese exporters welcomed the tariff deal announcements.
“This is positive news,” said Richard Chan of Golden Arts Gifts & Decor, which manufactures Christmas decorations in southern China and supplies to countries including the U.S. “The economy in both the U.S. and China is not really good, and the two sides should help each other more.”
However, because most of this year’s Christmas goods are already being shipped ahead of the peak holiday season, the tariff reductions may have limited effect for them at least for now.
Canada–U.S. trade tensions are likely to be the most important Canada-specific risk next week, particularly with new U.S. restrictions on some Canadian imports taking effect Sept. 29. Reuters
Canada GDP for July is due Sept. 29 and will provide an important read on whether the domestic economy is slowing under tariff and rate pressure. Statistics Canada
U.S. inflation and growth data on Sept. 30, followed by ISM Manufacturing Oct. 1 and the U.S. employment report Oct. 2, could materially change interest-rate expectations. Bureau of Economic Analysis
Iran/Strait of Hormuz developments remain a major TSX swing factor because WTI is near US$90+ and negotiations over reopening the strait remain unresolved. Reuters
Expect the largest sensitivity in energy, materials/gold, banks, industrials, autos and technology.
Energy: CNQ, SU, IMO, CVE most sensitive. Escalation → oil higher; credible reopening agreement → oil lower
Tues. Sept. 29
Canada GDP – July
Growth versus June and advance August estimate
Weak GDP → banks/consumer/industrials pressured; may strengthen expectations for easier BoC policy
Tues. Sept. 29
New U.S. restrictions on Canadian products
Implementation and any Canadian response
Negative for exposed manufacturers/exporters; trade uncertainty also affects CAD and banks
Tues. Sept. 29
U.S. JOLTS
Labour demand and job openings
Weak labour data → lower yields potentially positive for tech/gold; strong data can support higher rates
Wed. Sept. 30
U.S. PCE inflation
Core inflation in particular
Higher inflation → yields/rate expectations up; pressure on tech and rate-sensitive sectors
Wed. Sept. 30
U.S. Q2 GDP final estimate
Growth revisions and corporate profits
Strong growth supports cyclicals but could reinforce higher-for-longer rates
Thurs. Oct. 1
U.S. ISM Manufacturing PMI
New orders, prices paid, employment
Important for industrials, materials and broader growth expectations
Fri. Oct. 2
U.S. jobs report
Payrolls, unemployment, wages
Probably the week’s biggest scheduled market catalyst; can move rates, CAD/USD, gold and equities
Canada’s September Labour Force Survey is not due next week; Statistics Canada has scheduled it for Oct. 9. Statistics Canada
1. Canada–U.S. Tariff War — High Priority
The U.S. administration said on Sept. 25 that it was comfortable allowing the current dispute with Canada to continue. New restrictions on certain Canadian products are scheduled to take effect Sept. 29, while threats of significantly higher tariffs on Canadian autos, parts and steel remain in the background. Reuters
TSX sensitivity:
Negative: autos/parts, industrials, transportation and some consumer manufacturers.
Banks: slower Canadian growth could raise credit concerns.
CAD: further trade deterioration could weaken the Canadian dollar.
Energy/mining: potentially relatively insulated depending on exemptions and commodity prices.
The Bank of Canada has already warned that the latest tariffs could reduce Canadian Q4 growth below its earlier projection. Reuters
Watch: any new negotiations, retaliatory Canadian measures, or expansion of U.S. restrictions.
2. Canada GDP — Sept. 29
Statistics Canada is scheduled to report July real GDP by industry, together with an advance indication for August. Statistics Canada
This becomes more important because the market is trying to determine whether Canada can maintain growth while absorbing:
tariffs;
higher borrowing costs;
softer business investment;
weaker trade with the U.S.
TSX implications
Weaker GDP
Banks: modest negative
Consumer discretionary: negative
Industrials: negative
Utilities/REITs: potentially positive if bond yields fall
Stronger GDP
Banks/industrials: supportive
CAD: potentially stronger
But could reduce expectations for BoC easing.
3. U.S. Inflation — Sept. 30
The U.S. BEA will release August Personal Income and Outlays, which contains the Fed’s preferred PCE inflation measures, on Sept. 30. Bureau of Economic Analysis
This matters to the TSX because U.S. rate expectations affect global bond yields.
Higher-than-expected inflation
Likely direction:
U.S. yields ↑ → USD ↑ → growth/technology valuations pressured
Potential TSX effects:
SHOP / technology: negative
Gold: potentially negative from higher real yields
Banks: mixed
CAD: potentially weaker
Softer inflation
Could produce the opposite reaction:
yields ↓ → technology/gold potentially stronger.
4. U.S. Employment Report — Oct. 2
The September U.S. employment report is scheduled for 8:30 a.m. ET Friday Oct. 2. Bureau of Labor Statistics
Watch three numbers:
Payroll growth + unemployment rate + wage growth.
August wage growth was 3.1% YoY, so the September report will be important for judging whether labour-related inflation pressures continue. Bureau of Labor Statistics
A strong jobs/wages report could push yields higher and pressure technology and gold.
A weaker jobs report could increase expectations for easier Fed policy, generally supportive of gold and rate-sensitive equities—but a very weak report could instead raise recession concerns.
5. Oil, Iran and the Strait of Hormuz — Very High TSX Importance
This remains one of the largest short-term variables for the TSX.
WTI settled around US$92.41/bbl on Sept. 25, after falling roughly 2.3% that day as markets reacted to possible U.S.–Iran diplomacy. Reuters
However, negotiations remain unresolved. Iran has said reopening Hormuz depends on its conditions being met, while the U.S. rejected Iran’s latest proposal. Reuters
TSX transmission
Escalation / Hormuz disruption
WTI ↑ → CNQ, SU, IMO, CVE potentially stronger → TSX Energy ↑ → Canadian inflation risk ↑ → transportation/consumer margins pressured
Conversely, stronger U.S. economic data combined with higher yields could create short-term pressure on gold and gold equities.
Sector Watch for Sept. 28–Oct. 2
TSX Sector
Main Driver
Next-Week Bias Driver
Energy
WTI / Iran / Hormuz
Highest geopolitical sensitivity
Materials/Gold
Gold, USD, yields
Fed/data + safe-haven demand
Technology
U.S. yields
PCE + payrolls
Financials
Canada growth/rates
GDP + tariff effects
Industrials
Trade + economic growth
Canada–U.S. tariffs + ISM
Consumer Discretionary
Rates/trade
Weak GDP or tariffs negative
Utilities/REITs
Bond yields
Lower yields generally supportive
Three Scenarios
Bull case for TSX: Iran tensions ease without collapsing oil, U.S. inflation moderates, employment remains stable, Canadian GDP holds up and tariff escalation pauses.
Base case: continued tariff uncertainty, WTI remains volatile around current elevated levels, U.S. economic data remains firm and the TSX trades with substantial sector rotation rather than a broad directional move.
Bear case: Canada–U.S. trade tensions escalate while U.S. inflation/jobs remain strong enough to push yields higher, or Middle East conflict intensifies sharply enough to produce another oil/inflation shock.
What Would Disprove These Views
A credible U.S.–Iran agreement reopening Hormuz would sharply reduce the current energy-risk thesis. A Canada–U.S. trade settlement would materially improve the outlook for Canadian industrials and exporters. Conversely, unexpectedly weak U.S. employment combined with rapidly falling economic indicators would shift the dominant concern from inflation toward recession.
Most important items to monitor next week:1) Canada–U.S. tariffs, 2) Hormuz/WTI, 3) U.S. PCE inflation, 4) U.S. jobs report, 5) Canada GDP.
China industrial profits and current account surplus
(10:30 a.m. ET) U.S. Dallas Fed Manufacturing Activity Index for September.
Tuesday September 29
Euro zone economic and consumer confidence
(8:30 a.m. ET) Canada’s monthly real GDP for July. The Street expects a flat reading month-over-month.
(9 a.m. ET) U.S. S&P Cotality Case-Shiller Home Price Index (20 city) for July. Consensus is a rise of 0.2 per cent from June and up 2.2 per cent year-over-year.
(9 a.m. ET) U.S. FHFA House Price Index for July. Estimate is a month-over-month rise of 0.1 per cent and year-over-year gain of 2.5 per cent.
(10 a.m. ET) U.S. Conference Board Consumer Confidence Index for September.
(10 a.m. ET) U.S. Job Openings and Labor Turnover Survey for August.
(1:20 p.m. ET) Bank of Canada Deputy Governor Toni Gravelle speaks at a fireside chat at the Bloomberg Canadian
Finance Conference in New York.
Earnings include: Carnival Corp.
Wednesday September 30
Canada’s National Day for Truth and Reconciliation (stock markets open, bond markets closed)
China PMI
Japan retail sales and industrial production
Germany unemployment, retail sales and CPI
(8:15 a.m. ET) U.S. ADP national employment for September.
(8:30 a.m. ET) U.S. personal spending and income for August. The Street is projecting month-over-month gains of 0.9 per cent and 0.5 per cent, respectively.
(8:30 a.m. ET) U.S. core PCE price index (and revisions) for August. Consensus is a rise of 0.3 per cent from July and up 3.2 per cent year-over-year.
(8:30 a.m. ET) U.S. goods trade deficit for August.
(8:30 a.m. ET) U.S. wholesale and retail inventories for August.
(8:30 a.m. ET) U.S. real GDP and price index for Q2. The Street expects annualized rate rises of 1.5 per cent and 6.4 per cent, respectively.
(8:30 a.m. ET) U.S. pre-tax corporate profits for Q2.
(9:45 a.m. EYT) U.S. Chicago PMI for September.
Earnings include: Jabil Circuit Inc.; Micron Technology Inc.
Thursday October 1
Japan machine tool orders and manufacturing PMI
Euro zone jobless rate and manufacturing PMI
(8:30 a.m. ET) U.S. initial jobless claims for week of Sept. 26. Estimate is 200,000, an increase of 3,000 from the previous week.
(8:30 a.m. ET) U.S. Revelio Public Labour Statistics for September.
(9:30 a.m. ET) Canada’s S&P global manufacturing PMI for September.
(9:45 a.m. ET) U.S. S&P global manufacturing PMI for September.
(10 a.m. ET) U.S. ISM manufacturing PMI for September.
(10 a.m. ET) U.S. construction spending for August. Consensus is a month-over-month rise of 0.1 per cent.
(3:05 p.m. ET) Bank of Canada Senior Deputy Governor Carolyn Rogers speaks in Victoria.
Earnings include: Accenture PLC; McCormick & Co. Inc.; Nike Inc.
Friday October 2
Japan CPI and jobless rate
Euro zone CPI
(8:30 a.m. ET) U.S. nonfarm payrolls for September. The Street expects a gain of 100,000 jobs with the unemployment rate remaining 4.1 per cent and average hourly wages up 0.3 per cent.
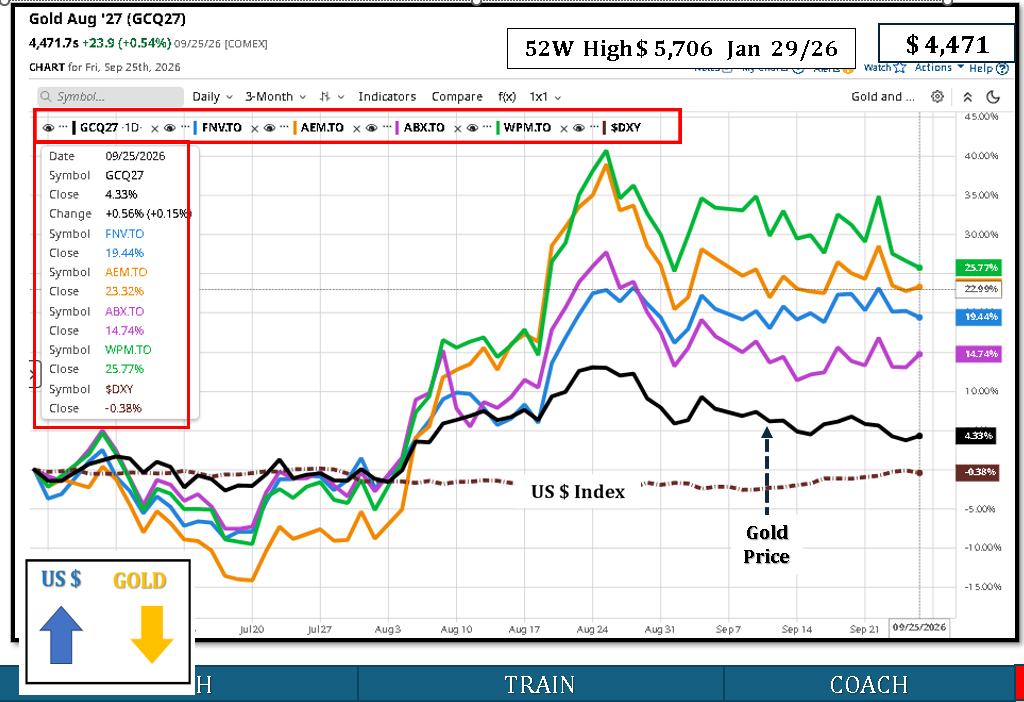
The chart shows gold futures up about 4.3% over three months, despite a recent pullback.
Gold’s main supports have been geopolitical risk, safe-haven demand and longer-term institutional/central-bank demand.
More recently, higher U.S. interest rates, rising Treasury yields and a stronger U.S. dollar have restrained gold. Reuters
All four Canadian-listed precious-metals names shown significantly outperformed gold over the period.
Performance shown on the chart: WPM +25.77%, AEM +23.32%, FNV +19.44%, ABX +14.74%.
3-Month Performance
Asset
Approx. 3-Month Change
Relative to Gold
WPM.TO
+25.77%
Strong outperformer
AEM.TO
+23.32%
Strong outperformer
FNV.TO
+19.44%
Outperformer
ABX.TO
+14.74%
Outperformer
Gold futures
+4.33%
Benchmark
U.S. Dollar Index
−0.38%
Slightly lower over period
Why Gold Rose
The biggest upward move occurred during August, when gold accelerated sharply.
1. Geopolitical uncertainty
Middle East tensions, including conflict involving Iran and risks around the Strait of Hormuz, supported demand for gold as a defensive asset. Gold reached a three-month high in late August amid continued Middle East conflict and political uncertainty.
2. Safe-haven demand
Gold typically benefits when investors become more concerned about geopolitical, financial or economic risk. That was an important driver of the August advance.
3. Longer-term investment demand
Institutional flows, central-bank buying and demand for alternatives to traditional financial assets have provided structural support to gold during 2026. Reuters
Why Gold Has Recently Pulled Back
The picture changed in September.
The Federal Reserve raised rates and markets began pricing further tightening. Higher interest rates increase the opportunity cost of owning gold because gold produces no interest income.
U.S. Treasury yields also rose sharply, while the dollar strengthened. Both tend to pressure gold. On September 25, gold rebounded modestly as the dollar eased, but still finished the week roughly 2% lower because of higher yields and additional Fed rate-hike expectations.
Gold stocks often move more than gold itself because changes in the gold price can have a leveraged effect on miners’ cash flows.
WPM.TO — Wheaton Precious Metals
3-month gain: +25.77%
WPM is the strongest performer shown.
Wheaton is primarily a precious-metals streaming company, rather than a conventional miner. It finances mines in exchange for the right to buy a portion of future metal production at predetermined prices.
That structure gives it substantial exposure to rising gold prices while generally reducing direct exposure to mine-level operating costs.
Chart interpretation: WPM surged more than 40% at its August peak, before consolidating to approximately +25.8%.
AEM.TO — Agnico Eagle
3-month gain: +23.32%
Agnico Eagle closely tracked the gold rally but amplified it substantially.
A miner’s revenue rises when gold prices increase while many operating costs do not rise equally fast. This creates operating leverage.
Simple example:
If mining cost = US$2,000/oz:
Gold at US$4,000 → margin = US$2,000
Gold at US$4,400 → gold rises 10%
Margin increases from US$2,000 to US$2,400 = 20%
That helps explain why miners can rise much faster than the underlying metal.
AEM reached nearly +40% at its August peak before pulling back.
FNV.TO — Franco-Nevada
3-month gain: +19.44%
Franco-Nevada is also primarily a royalty and streaming company.
Its model provides exposure to commodity prices without directly operating most mines.
The chart shows relatively strong but more controlled performance compared with WPM and AEM.
FNV climbed to approximately +23–24% during August and finished near +19.4%.
ABX.TO — Barrick
3-month gain: +14.74%
Barrick also benefited from higher gold prices, but its share-price appreciation was smaller than the other three companies shown.
The chart indicates ABX peaked around +27% in August before giving back a meaningful portion of the gain.
That illustrates an important point: gold-price exposure alone does not determine miner performance. Production, costs, capital spending, reserve quality, country exposure and company-specific execution also matter.
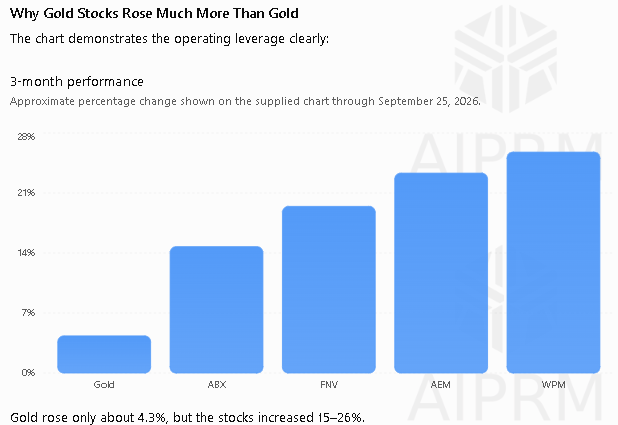
Why Gold Stocks Rose Much More Than Gold
The chart demonstrates the operating leverage clearly:
Approximate percentage change shown on the supplied chart through September 25, 2026.
0%7%14%21%28%GoldABXFNVAEMWPM
Gold rose only about 4.3%, but the stocks increased 15–26%.
The main reasons are:
operating leverage to the gold price;
expanding expected mining margins;
stronger expected cash flows;
investor rotation into gold equities;
royalty/streaming companies benefiting from higher metal prices without equivalent increases in operating costs.
Key Takeaway
The three-month trend remains positive for precious metals, but momentum has moderated since the August highs.
The main factor to watch now is U.S. monetary policy. Continued rate increases and rising Treasury yields would work against gold, while renewed geopolitical deterioration or falling real yields would provide renewed support.
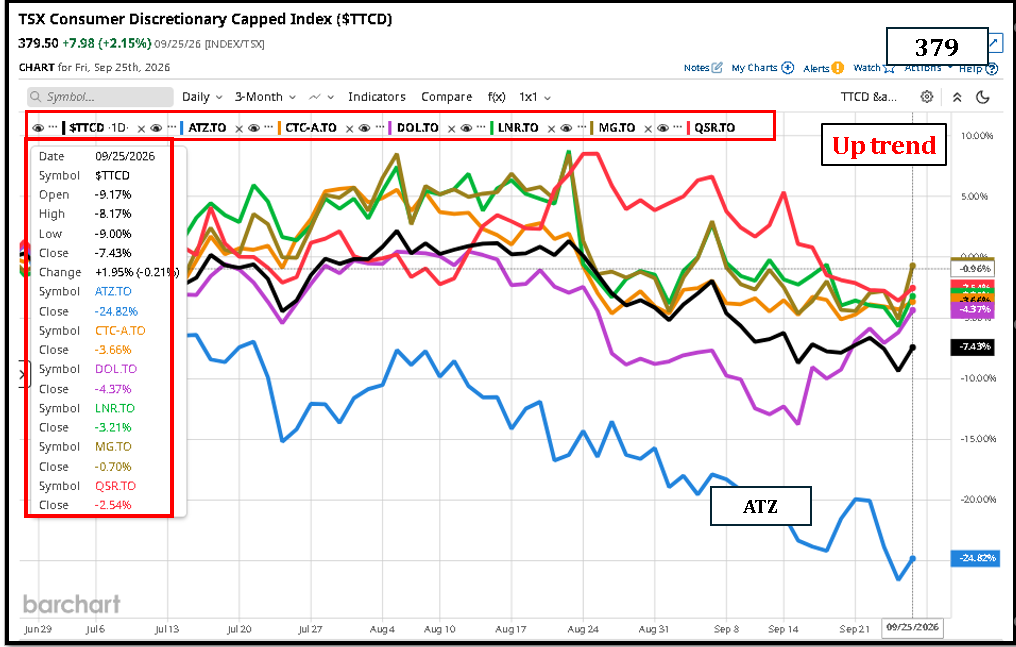
The TSX Consumer Discretionary Index ($TTCD) is showing a short-term rebound, but the 3-month picture is still mixed.
$TTCD: about -7.4% over 3 months, despite a strong +2.1% daily gain on Sept. 25.
ATZ.TO: weakest performer at roughly -24.8%. The large decline has been the main drag among the names shown.
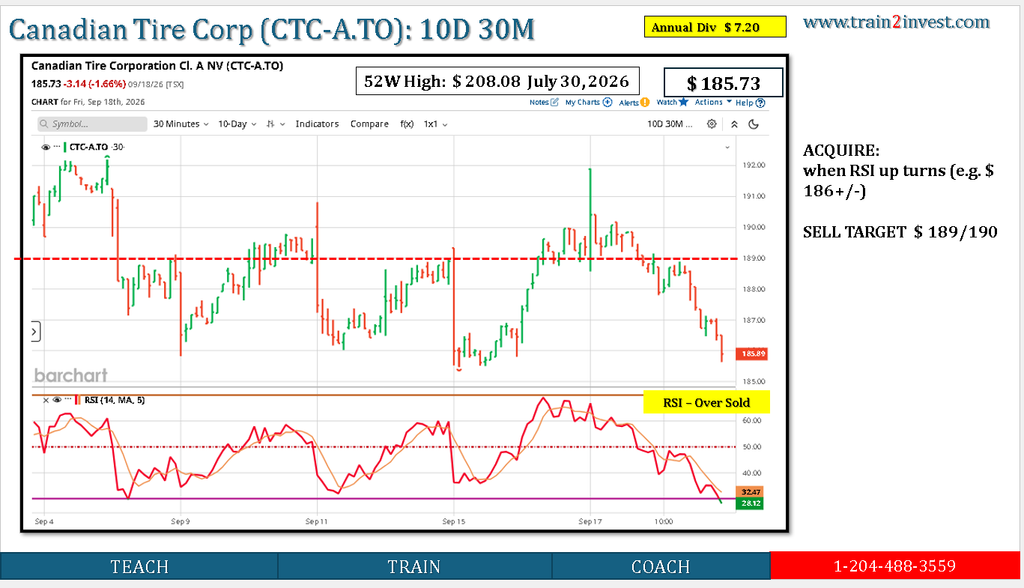
CTC.A.TO: about -3.7%, relatively resilient versus the sector.
DOL.TO: about -4.4%, modest decline after earlier strength.
LNR.TO: about -3.2%, holding up comparatively well.
MG.TO: roughly -0.7%, strongest relative performer in the group shown.
QSR.TO: about -2.5%, also relatively defensive.
Main Reasons
The sector weakness likely reflects:
Consumer spending concerns — discretionary businesses are more sensitive to slowing household demand.
Higher borrowing costs / rate uncertainty — pressures auto, retail and other rate-sensitive spending.
Tariff and trade uncertainty — particularly relevant for auto-related names such as Magna and Linamar.
Company-specific weakness — especially Aritzia, which has significantly underperformed the rest of the group.
Recent rebound — the upward move at the far right suggests some buying after the sector became heavily sold down.
Bottom line: the chart shows an early rebound, not yet a confirmed 3-month uptrend. Most names remain below their late-June levels, with ATZ the clear laggard.
Bond yields are interest rates — the market rate for that maturity. Policy rates (Fed/BoC overnight) are the short end; bond yields are the rest of the curve. (*) See below
How they connect
Policy rate ↑ → short yields rise first; longer yields follow if markets expect the hike to stick or inflation to stay hot.
Bond yields ↑ first (oil shock, strong data, deficit fears) → markets price more future hikes. That forces the Fed/BoC to stay tight or hike, even if they wanted a pause.
Last week: US 10y >5% (highest since 2007) + Canada 10y ~4.0% = market saying “another hike is coming.” That is what hit the TSX.
What rising yields actually do
Channel
Effect
Mortgages / loans
New fixed rates reprice off the 5y/10y. Existing floating rates lag until reset.
Banks
Funding cost ↑; loan demand ↓; bond books marked down. High valuations make this worse (why CM/RY/TD sold off Sep 23).
Corporates
Debt rollover more expensive → capex and buybacks slow.
Equities
Higher discount rate on future cash flows. Long-duration names (tech, growth, utilities) get hit first.
CAD / inflation
Higher CA yields support CAD if purely domestic; last week CAD slipped because US yields rose more and oil/geopolitics dominated.
Last week’s loop (the one on your chart) Oil ↑ → inflation scare → US 10y to 5%+ → Canada 10y to ~4% → banks + miners sold → TSX −584 pts. Fri bounce = oil eased on Hormuz-deal talk → yields pulled back a bit → banks bounced.
Rule of thumb: a 25–50 bp jump in the 10y, if it holds, is roughly one extra hike priced in. That is a tightening of financial conditions even before the central bank moves.
(*) Two different rates, one curve.
1. Policy rate (short end) Overnight rate set by the Fed or BoC.
Fed funds / BoC target: the rate banks charge each other overnight.
Directly controlled. Changed at meetings (hike, hold, cut).
Anchors the left side of the curve: overnight → 1-month → 3-month bills.
2. Bond yields (the rest of the curve) The interest rate the market demands to lend to the government for 2, 5, 10, 30 years.
Not set by the central bank. Set by buyers and sellers of bonds.
If you buy a 10-year Canada bond at a price that implies 4%, that 4% is the 10-year interest rate.
Right = market’s forecast of future policy + inflation + term premium (extra pay for locking money up longer).
Why they move together — but not 1-for-1
Hike expected → 2y yield jumps first (it is almost a bet on the next few meetings).
Inflation/oil/deficit scare → 10y and 30y jump even if the overnight rate has not moved yet. That is higher long-term interest rates.
Last week: Fed/BoC had not hiked that day. The 10y did. So market rates rose before the official rate did.
Simple version Policy rate = what the central bank charges tonight. Bond yield = what the market charges to lend for years. Both are interest rates. The curve is just those rates lined up by maturity.
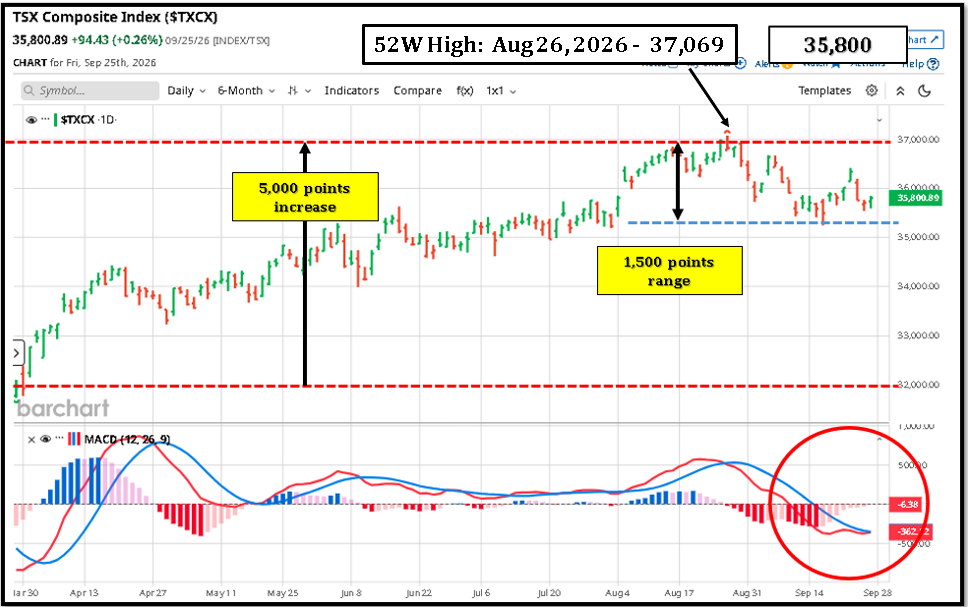
Big picture: The TSX rose roughly 5,000 points from the ~32,000 area to approach 37,000 over the period shown.
Current level: At 35,800.89, the index is about 1,200 points below the 37,000 resistance area.
Recent range: Since the August peak, the TSX has largely traded in a ~35,500–37,000 range, roughly 1,500 points.
37,000 = resistance: The repeated failure around 37,000 suggests sellers have emerged near that level.
35,500 = support: The recent lows around 35,500 are an important near-term level. A sustained break below it would indicate the range is weakening.
MACD: The MACD has turned negative, with the MACD line below the signal line and a negative histogram. This indicates weakening momentum in the near term.
However: The index remains well above its earlier March/April levels, so the chart shows short-term consolidation/weakening momentum within a larger six-month uptrend, rather than a confirmed major reversal.
In one sentence:The TSX has had a strong longer-term run, but it is currently consolidating between roughly 35,500 support and 37,000 resistance, with the negative MACD suggesting near-term momentum has weakened.