Category: Uncategorized

  • U.S., China each cut tariffs on $30-billion of products after Trump-Xi meeting

    The United States and China released Monday reciprocal lists of products worth about US$30-billion each that will see tariff cuts, in a deal expected to boost bilateral trade.

    The details came days after Chinese President Xi Jinping met with President Donald Trump in Washington in his first state visit to the U.S. since 2015. The U.S. had already reduced tariffs against China after Trump’s tariffs reached as high as 145 per cent at one point last year, as tensions between the two countries eased.

    China’s commerce ministry said in a statement the agreement will help strengthen trade co-operation.

    Most country-specific tariffs practically eradicated

    The lists included 1,619 items of U.S. goods entering China, ranging from agricultural commodities, personal care products to timber and medical equipment. Coal from the U.S. will also be included.

    For Chinese goods exported to the U.S., 77 categories were covered, including fireworks, tableware, glass and wooden Christmas ornaments and soccer balls.

    Tariff rates on over 90 per cent of the products would be subject to “most-favoured-nation” levels, the Chinese commerce ministry said, meaning that country-specific tariffs will effectively be eliminated.

    U.S. Trade Representative Jamieson Greer said in a separate statement the product lists focused on “nonsensitive goods on each side that could benefit from more favorable tariff treatment.” The deal could help secure market access for U.S. farmers, manufacturers, businesses and workers, while benefiting American consumers with imports from China including household goods and toys, Greer said.

    Both countries said they agreed the list may be adjusted later as needed, but amendments were likely to be no more than on an annual basis.

    Analysis: Trump’s heavy-handed approach to China leaves trade partners with stark choice

    The Chinese commerce ministry said the two countries agreed to further co-operate in the agricultural sector, forming a group under the Board of Trade established in May to optimize bilateral trade.

    Sectors of strategic importance for both countries, such as chips, electric vehicles and batteries, were not covered under the agreement.

    More stories below advertisement

    https://imasdk.googleapis.com/js/core/bridge3.791.0_en.html#deid=%22%22&eventfe_experiment_ids=%5B%5D&fid=%22goog_1229864252%22&genotype_experiment_data=%7B%22experimentStateProto%22%3A%22%5B%5B%5B45713128%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45796605%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B45816264%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45761044%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45803173%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45722344%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45801847%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45784857%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45668885%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45685340%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45734716%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45735891%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45663239%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B839547366%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B45676441%2Cnull%2Cnull%2C%5B%5D%5D%2C%5Bnull%2C45645574%2Cnull%2C%5B%5D%5D%2C%5B45688859%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45685601%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5Bnull%2C45685602%2Cnull%2C%5Bnull%2C100%5D%5D%2C%5B45830425%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45820997%2Cnull%2Cnull%2C%5B%5D%5D%2C%5Bnull%2C45812678%2Cnull%2C%5B%5D%5D%2C%5B45756824%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B45794243%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45747172%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B775241416%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B781107959%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B781107958%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B792614055%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B781107957%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45729602%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45753603%2Cnull%2Cnull%2C%5B%5D%5D%2C%5B45753604%2Cnull%2Cnull%2C%5B%5D%5D%5D%2C%5B%5B16%2C%5B%5B10%2C%5B%5B83323635%5D%2C%5B83323636%2C%5B%5Bnull%2C45812678%2Cnull%2C%5Bnull%2C100%5D%5D%5D%5D%5D%5D%2C%5B50%2C%5B%5B83323870%5D%2C%5B83323871%2C%5B%5B45830425%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%2C%5B1000%2C%5B%5B95332046%5D%5D%5D%2C%5Bnull%2C%5B%5B95332047%5D%5D%5D%2C%5B10%2C%5B%5B95338769%2C%5B%5Bnull%2C45645574%2Cnull%2C%5Bnull%2C1%5D%5D%5D%5D%2C%5B95338770%2C%5B%5Bnull%2C45645574%2Cnull%2C%5Bnull%2C2%5D%5D%5D%5D%5D%5D%2C%5B1%2C%5B%5B95373378%2C%5B%5B792614055%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%2C%5B95373379%2C%5B%5B45747172%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B781107959%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B792614055%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B781107957%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%2C%5B10%2C%5B%5B95378629%5D%2C%5B95378630%2C%5B%5B45729602%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%2C%5B95381582%2C%5B%5B45729602%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B45753603%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%2C%5B95381583%2C%5B%5B45729602%2Cnull%2Cnull%2C%5B1%5D%5D%2C%5B45753604%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%2C%5B10%2C%5B%5B95389581%5D%2C%5B95389582%2C%5B%5B635466687%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%2C%5Bnull%2C%5B%5B95391735%5D%5D%5D%2C%5B50%2C%5B%5B95394237%5D%2C%5B95394238%2C%5B%5B45801847%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%2C%5Bnull%2C%5B%5B95394594%5D%2C%5B95394595%2C%5B%5B45803173%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%2C%5B10%2C%5B%5B95398837%5D%2C%5B95398838%2C%5B%5Bnull%2C960449109%2Cnull%2C%5Bnull%2C1%5D%5D%5D%5D%5D%5D%2C%5B1%2C%5B%5B95401453%5D%2C%5B95401454%2C%5B%5B45668885%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%2C%5B50%2C%5B%5B95402052%5D%2C%5B95402053%2C%5B%5B957164676%2Cnull%2Cnull%2C%5B1%5D%5D%5D%5D%5D%5D%5D%5D%5D%2Cnull%2Cnull%2C%5Bnull%2C1000%2C1%2C1000%5D%5D%22%7D&imalib_experiments=%5B95322027%2C95331589%2C95332046%2C95402052%5D&is_eap_loader=false&managed_js_experiment_id=0&page_correlator=4371512442661727&pvsid=5463268276968256&top_accessible_page_url=%22https%3A%2F%2Fwww.theglobeandmail.com%2Fbusiness%2Farticle-us-china-tariff-reduction-product-lists-trump-xi-meeting%2F%22

    A potential boost to U.S.-China bilateral trade

    “This is a positive outcome for these affected products compared to a smaller tariff cut, and could lead to a more significant boost to bilateral trade,” said Lynn Song, chief economist for Greater China at ING Bank.

    The lowered tariffs could be a win for U.S. consumer brands, added Jacob Cooke, CEO of WPIC Marketing + Technologies based in Beijing, as some of the products covered by China’s list of U.S. imports included fast-growing categories like hair care, personal care products and infant formula.

    The U.S. list for Chinese imports focused more on consumer goods, which could help lower U.S. inflation while also allowing Chinese firms to export more of their overcapacity, said Gary Ng, a senior economist at French bank Natixis.

    Some experts said, however, the economic impact at US$30-billion each way may be limited overall.

    U.S. exports to China were roughly US$68-billion through the first seven months of this year, while Chinese exports to the U.S. were at around US$270-billion for the first eight months, said Prashant Bhayani, chief investment officer for Asia at BNP Paribas Wealth Management.

    A US$30-billion deal each way will be “more meaningful” for U.S. exports to China in terms of percentage share, he said.

    China’s trade surplus expected to remain elevated

    While the deal did not cover sensitive strategic goods, analysts believe U.S.-China trade will likely continue to recover for the rest of the year after steep U.S. tariffs on Chinese products last year hit bilateral trade.

    The U.S. and China last week also reached a two-month extension of the broader trade truce that was set to expire Nov. 10 to January.

    China’s trade surplus, which reached a record US$1.2-trillion last year, will likely remain elevated. By August, it stood at about US$800-billion, putting this year’s surplus “on pace to exceed the 2025 record,” according to Ecaterina Bigos, a senior market strategist with BNP Paribas Asset Management.

    The U.S. is also investigating China among 16 trading partners in its Section 301 probe on excess industrial capacity and could impose additional tariffs on China when the investigation concludes.

    However, with more meetings set between Trump and Xi, including at the Asia-Pacific Economic Cooperation summit in Shenzhen in November and at the Group of 20 summit in Florida in December, Song at ING said he would not expect a major flare-up of trade tensions before year-end.

    Exporters welcome the tariff deal

    Some Chinese exporters welcomed the tariff deal announcements.

    “This is positive news,” said Richard Chan of Golden Arts Gifts & Decor, which manufactures Christmas decorations in southern China and supplies to countries including the U.S. “The economy in both the U.S. and China is not really good, and the two sides should help each other more.”

    However, because most of this year’s Christmas goods are already being shipped ahead of the peak holiday season, the tariff reductions may have limited effect for them at least for now.
  • Key focus next week (Sept 28 – Oct 2, 2026)

    • Canada–U.S. trade tensions are likely to be the most important Canada-specific risk next week, particularly with new U.S. restrictions on some Canadian imports taking effect Sept. 29. Reuters
    • Canada GDP for July is due Sept. 29 and will provide an important read on whether the domestic economy is slowing under tariff and rate pressure. Statistics Canada
    • U.S. inflation and growth data on Sept. 30, followed by ISM Manufacturing Oct. 1 and the U.S. employment report Oct. 2, could materially change interest-rate expectations. Bureau of Economic Analysis
    • Iran/Strait of Hormuz developments remain a major TSX swing factor because WTI is near US$90+ and negotiations over reopening the strait remain unresolved. Reuters
    • Expect the largest sensitivity in energy, materials/gold, banks, industrials, autos and technology.

    Key Events and Likely TSX Impact

    DateFactorWhat to WatchPotential TSX Impact
    Mon. Sept. 28Iran/Hormuz & oilDiplomatic developments, shipping flows, Saudi/Houthi attacksEnergy: CNQ, SU, IMO, CVE most sensitive. Escalation → oil higher; credible reopening agreement → oil lower
    Tues. Sept. 29Canada GDP – JulyGrowth versus June and advance August estimateWeak GDP → banks/consumer/industrials pressured; may strengthen expectations for easier BoC policy
    Tues. Sept. 29New U.S. restrictions on Canadian productsImplementation and any Canadian responseNegative for exposed manufacturers/exporters; trade uncertainty also affects CAD and banks
    Tues. Sept. 29U.S. JOLTSLabour demand and job openingsWeak labour data → lower yields potentially positive for tech/gold; strong data can support higher rates
    Wed. Sept. 30U.S. PCE inflationCore inflation in particularHigher inflation → yields/rate expectations up; pressure on tech and rate-sensitive sectors
    Wed. Sept. 30U.S. Q2 GDP final estimateGrowth revisions and corporate profitsStrong growth supports cyclicals but could reinforce higher-for-longer rates
    Thurs. Oct. 1U.S. ISM Manufacturing PMINew orders, prices paid, employmentImportant for industrials, materials and broader growth expectations
    Fri. Oct. 2U.S. jobs reportPayrolls, unemployment, wagesProbably the week’s biggest scheduled market catalyst; can move rates, CAD/USD, gold and equities

    Canada’s September Labour Force Survey is not due next week; Statistics Canada has scheduled it for Oct. 9. Statistics Canada

    1. Canada–U.S. Tariff War — High Priority

    The U.S. administration said on Sept. 25 that it was comfortable allowing the current dispute with Canada to continue. New restrictions on certain Canadian products are scheduled to take effect Sept. 29, while threats of significantly higher tariffs on Canadian autos, parts and steel remain in the background. Reuters

    TSX sensitivity:

    • Negative: autos/parts, industrials, transportation and some consumer manufacturers.
    • Banks: slower Canadian growth could raise credit concerns.
    • CAD: further trade deterioration could weaken the Canadian dollar.
    • Energy/mining: potentially relatively insulated depending on exemptions and commodity prices.

    The Bank of Canada has already warned that the latest tariffs could reduce Canadian Q4 growth below its earlier projection. Reuters

    Watch: any new negotiations, retaliatory Canadian measures, or expansion of U.S. restrictions.


    2. Canada GDP — Sept. 29

    Statistics Canada is scheduled to report July real GDP by industry, together with an advance indication for August. Statistics Canada

    This becomes more important because the market is trying to determine whether Canada can maintain growth while absorbing:

    • tariffs;
    • higher borrowing costs;
    • softer business investment;
    • weaker trade with the U.S.

    TSX implications

    Weaker GDP

    • Banks: modest negative
    • Consumer discretionary: negative
    • Industrials: negative
    • Utilities/REITs: potentially positive if bond yields fall

    Stronger GDP

    • Banks/industrials: supportive
    • CAD: potentially stronger
    • But could reduce expectations for BoC easing.

    3. U.S. Inflation — Sept. 30

    The U.S. BEA will release August Personal Income and Outlays, which contains the Fed’s preferred PCE inflation measures, on Sept. 30. Bureau of Economic Analysis

    This matters to the TSX because U.S. rate expectations affect global bond yields.

    Higher-than-expected inflation

    Likely direction:

    U.S. yields ↑ → USD ↑ → growth/technology valuations pressured

    Potential TSX effects:

    • SHOP / technology: negative
    • Gold: potentially negative from higher real yields
    • Banks: mixed
    • CAD: potentially weaker

    Softer inflation

    Could produce the opposite reaction:

    yields ↓ → technology/gold potentially stronger.


    4. U.S. Employment Report — Oct. 2

    The September U.S. employment report is scheduled for 8:30 a.m. ET Friday Oct. 2. Bureau of Labor Statistics

    Watch three numbers:

    Payroll growth + unemployment rate + wage growth.

    August wage growth was 3.1% YoY, so the September report will be important for judging whether labour-related inflation pressures continue. Bureau of Labor Statistics

    A strong jobs/wages report could push yields higher and pressure technology and gold.

    A weaker jobs report could increase expectations for easier Fed policy, generally supportive of gold and rate-sensitive equities—but a very weak report could instead raise recession concerns.


    5. Oil, Iran and the Strait of Hormuz — Very High TSX Importance

    This remains one of the largest short-term variables for the TSX.

    WTI settled around US$92.41/bbl on Sept. 25, after falling roughly 2.3% that day as markets reacted to possible U.S.–Iran diplomacy. Reuters

    However, negotiations remain unresolved. Iran has said reopening Hormuz depends on its conditions being met, while the U.S. rejected Iran’s latest proposal. Reuters

    TSX transmission

    Escalation / Hormuz disruption

    WTI ↑
    → CNQ, SU, IMO, CVE potentially stronger
    → TSX Energy ↑
    → Canadian inflation risk ↑
    → transportation/consumer margins pressured

    Diplomatic breakthrough / increased oil flows

    WTI ↓
    → Energy stocks pressured
    → inflation expectations ↓
    → consumer/industrials potentially benefit.

    Oil has been extremely sensitive to headlines: it moved almost +4% on Sept. 23, then about −2% Sept. 25 as diplomatic expectations changed. Reuters


    6. Gold

    Gold will primarily respond next week to:

    Fed expectations + U.S. yields + USD + Iran/Hormuz geopolitical risk.

    The strongest combination for gold would generally be:

    falling yields + weaker USD + increased geopolitical stress.

    Potential TSX names:

    AEM, WPM, FNV, ABX

    Conversely, stronger U.S. economic data combined with higher yields could create short-term pressure on gold and gold equities.


    Sector Watch for Sept. 28–Oct. 2

    TSX SectorMain DriverNext-Week Bias Driver
    EnergyWTI / Iran / HormuzHighest geopolitical sensitivity
    Materials/GoldGold, USD, yieldsFed/data + safe-haven demand
    TechnologyU.S. yieldsPCE + payrolls
    FinancialsCanada growth/ratesGDP + tariff effects
    IndustrialsTrade + economic growthCanada–U.S. tariffs + ISM
    Consumer DiscretionaryRates/tradeWeak GDP or tariffs negative
    Utilities/REITsBond yieldsLower yields generally supportive

    Three Scenarios

    Bull case for TSX: Iran tensions ease without collapsing oil, U.S. inflation moderates, employment remains stable, Canadian GDP holds up and tariff escalation pauses.

    Base case: continued tariff uncertainty, WTI remains volatile around current elevated levels, U.S. economic data remains firm and the TSX trades with substantial sector rotation rather than a broad directional move.

    Bear case: Canada–U.S. trade tensions escalate while U.S. inflation/jobs remain strong enough to push yields higher, or Middle East conflict intensifies sharply enough to produce another oil/inflation shock.

    What Would Disprove These Views

    A credible U.S.–Iran agreement reopening Hormuz would sharply reduce the current energy-risk thesis. A Canada–U.S. trade settlement would materially improve the outlook for Canadian industrials and exporters. Conversely, unexpectedly weak U.S. employment combined with rapidly falling economic indicators would shift the dominant concern from inflation toward recession.

    Most important items to monitor next week: 1) Canada–U.S. tariffs, 2) Hormuz/WTI, 3) U.S. PCE inflation, 4) U.S. jobs report, 5) Canada GDP.

  • Calendar: Sept 28 – Oct 2nd

    Monday September 28

    China industrial profits and current account surplus

    (10:30 a.m. ET) U.S. Dallas Fed Manufacturing Activity Index for September.


    Tuesday September 29

    Euro zone economic and consumer confidence

    (8:30 a.m. ET) Canada’s monthly real GDP for July. The Street expects a flat reading month-over-month.

    (9 a.m. ET) U.S. S&P Cotality Case-Shiller Home Price Index (20 city) for July. Consensus is a rise of 0.2 per cent from June and up 2.2 per cent year-over-year.

    (9 a.m. ET) U.S. FHFA House Price Index for July. Estimate is a month-over-month rise of 0.1 per cent and year-over-year gain of 2.5 per cent.

    (10 a.m. ET) U.S. Conference Board Consumer Confidence Index for September.

    (10 a.m. ET) U.S. Job Openings and Labor Turnover Survey for August.

    (1:20 p.m. ET) Bank of Canada Deputy Governor Toni Gravelle speaks at a fireside chat at the Bloomberg Canadian

    Finance Conference in New York.

    Earnings include: Carnival Corp.


    Wednesday September 30

    Canada’s National Day for Truth and Reconciliation (stock markets open, bond markets closed)

    China PMI

    Japan retail sales and industrial production

    Germany unemployment, retail sales and CPI

    (8:15 a.m. ET) U.S. ADP national employment for September.

    (8:30 a.m. ET) U.S. personal spending and income for August. The Street is projecting month-over-month gains of 0.9 per cent and 0.5 per cent, respectively.

    (8:30 a.m. ET) U.S. core PCE price index (and revisions) for August. Consensus is a rise of 0.3 per cent from July and up 3.2 per cent year-over-year.

    (8:30 a.m. ET) U.S. goods trade deficit for August.

    (8:30 a.m. ET) U.S. wholesale and retail inventories for August.

    (8:30 a.m. ET) U.S. real GDP and price index for Q2. The Street expects annualized rate rises of 1.5 per cent and 6.4 per cent, respectively.

    (8:30 a.m. ET) U.S. pre-tax corporate profits for Q2.

    (9:45 a.m. EYT) U.S. Chicago PMI for September.

    Earnings include: Jabil Circuit Inc.; Micron Technology Inc.


    Thursday October 1

    Japan machine tool orders and manufacturing PMI

    Euro zone jobless rate and manufacturing PMI

    (8:30 a.m. ET) U.S. initial jobless claims for week of Sept. 26. Estimate is 200,000, an increase of 3,000 from the previous week.

    (8:30 a.m. ET) U.S. Revelio Public Labour Statistics for September.

    (9:30 a.m. ET) Canada’s S&P global manufacturing PMI for September.

    (9:45 a.m. ET) U.S. S&P global manufacturing PMI for September.

    (10 a.m. ET) U.S. ISM manufacturing PMI for September.

    (10 a.m. ET) U.S. construction spending for August. Consensus is a month-over-month rise of 0.1 per cent.

    (3:05 p.m. ET) Bank of Canada Senior Deputy Governor Carolyn Rogers speaks in Victoria.

    Earnings include: Accenture PLC; McCormick & Co. Inc.; Nike Inc.


    Friday October 2

    Japan CPI and jobless rate

    Euro zone CPI

    (8:30 a.m. ET) U.S. nonfarm payrolls for September. The Street expects a gain of 100,000 jobs with the unemployment rate remaining 4.1 per cent and average hourly wages up 0.3 per cent.

    (10 a.m. ET) U.S. factory orders for August.

    Also: Canadian auto sales for September.

  • Gold & Gold Stocks: 3M Daily

    Summary

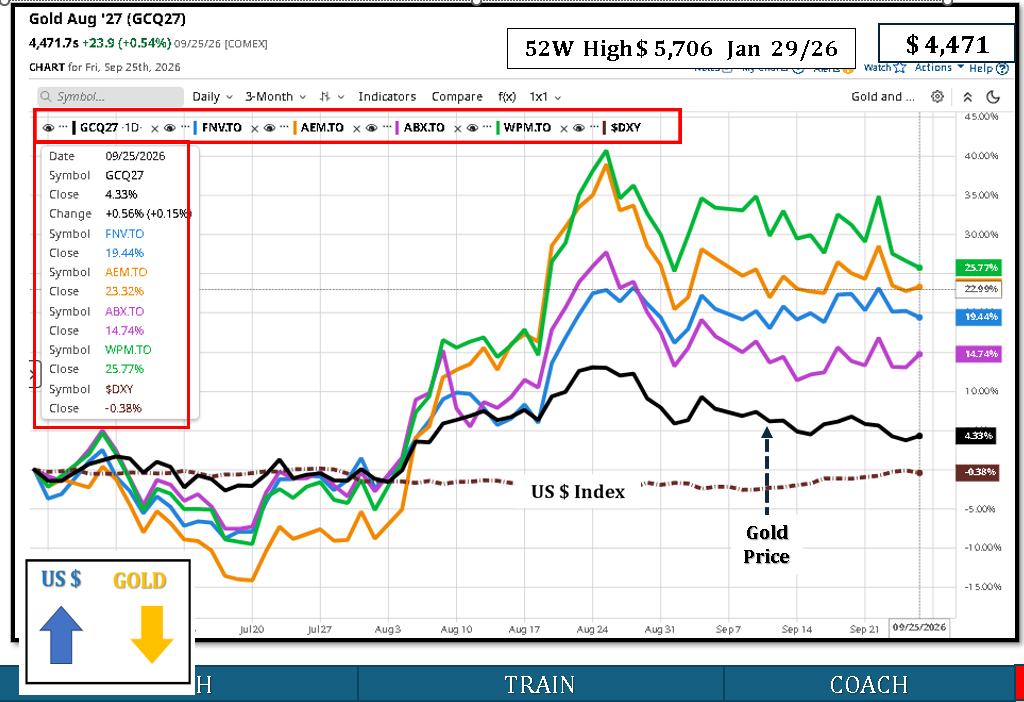
    • The chart shows gold futures up about 4.3% over three months, despite a recent pullback.
    • Gold’s main supports have been geopolitical risk, safe-haven demand and longer-term institutional/central-bank demand.
    • More recently, higher U.S. interest rates, rising Treasury yields and a stronger U.S. dollar have restrained gold. Reuters
    • All four Canadian-listed precious-metals names shown significantly outperformed gold over the period.
    • Performance shown on the chart: WPM +25.77%, AEM +23.32%, FNV +19.44%, ABX +14.74%.

    3-Month Performance

    AssetApprox. 3-Month ChangeRelative to Gold
    WPM.TO+25.77%Strong outperformer
    AEM.TO+23.32%Strong outperformer
    FNV.TO+19.44%Outperformer
    ABX.TO+14.74%Outperformer
    Gold futures+4.33%Benchmark
    U.S. Dollar Index−0.38%Slightly lower over period

    Why Gold Rose

    The biggest upward move occurred during August, when gold accelerated sharply.

    1. Geopolitical uncertainty

    Middle East tensions, including conflict involving Iran and risks around the Strait of Hormuz, supported demand for gold as a defensive asset. Gold reached a three-month high in late August amid continued Middle East conflict and political uncertainty.

    2. Safe-haven demand

    Gold typically benefits when investors become more concerned about geopolitical, financial or economic risk. That was an important driver of the August advance.

    3. Longer-term investment demand

    Institutional flows, central-bank buying and demand for alternatives to traditional financial assets have provided structural support to gold during 2026. Reuters

    Why Gold Has Recently Pulled Back

    The picture changed in September.

    The Federal Reserve raised rates and markets began pricing further tightening. Higher interest rates increase the opportunity cost of owning gold because gold produces no interest income.

    U.S. Treasury yields also rose sharply, while the dollar strengthened. Both tend to pressure gold. On September 25, gold rebounded modestly as the dollar eased, but still finished the week roughly 2% lower because of higher yields and additional Fed rate-hike expectations.

    So the current gold environment is a tug-of-war:

    Geopolitical risk / safe-haven demand ↑ gold

    versus

    Higher rates / higher bond yields / stronger USD ↓ gold


    Gold Stocks

    Gold stocks often move more than gold itself because changes in the gold price can have a leveraged effect on miners’ cash flows.

    WPM.TO — Wheaton Precious Metals

    3-month gain: +25.77%

    WPM is the strongest performer shown.

    Wheaton is primarily a precious-metals streaming company, rather than a conventional miner. It finances mines in exchange for the right to buy a portion of future metal production at predetermined prices.

    That structure gives it substantial exposure to rising gold prices while generally reducing direct exposure to mine-level operating costs.

    Chart interpretation: WPM surged more than 40% at its August peak, before consolidating to approximately +25.8%.


    AEM.TO — Agnico Eagle

    3-month gain: +23.32%

    Agnico Eagle closely tracked the gold rally but amplified it substantially.

    A miner’s revenue rises when gold prices increase while many operating costs do not rise equally fast. This creates operating leverage.

    Simple example:

    If mining cost = US$2,000/oz:

    • Gold at US$4,000 → margin = US$2,000
    • Gold at US$4,400 → gold rises 10%
    • Margin increases from US$2,000 to US$2,400 = 20%

    That helps explain why miners can rise much faster than the underlying metal.

    AEM reached nearly +40% at its August peak before pulling back.


    FNV.TO — Franco-Nevada

    3-month gain: +19.44%

    Franco-Nevada is also primarily a royalty and streaming company.

    Its model provides exposure to commodity prices without directly operating most mines.

    The chart shows relatively strong but more controlled performance compared with WPM and AEM.

    FNV climbed to approximately +23–24% during August and finished near +19.4%.


    ABX.TO — Barrick

    3-month gain: +14.74%

    Barrick also benefited from higher gold prices, but its share-price appreciation was smaller than the other three companies shown.

    The chart indicates ABX peaked around +27% in August before giving back a meaningful portion of the gain.

    That illustrates an important point: gold-price exposure alone does not determine miner performance. Production, costs, capital spending, reserve quality, country exposure and company-specific execution also matter.


    Why Gold Stocks Rose Much More Than Gold

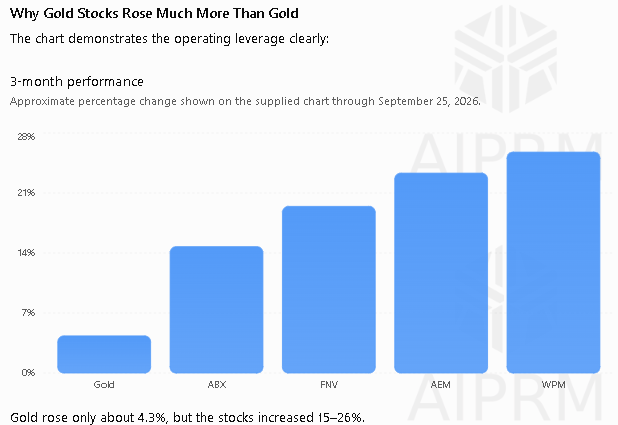
    The chart demonstrates the operating leverage clearly:

    Approximate percentage change shown on the supplied chart through September 25, 2026.

    0%7%14%21%28%GoldABXFNVAEMWPM

    Gold rose only about 4.3%, but the stocks increased 15–26%.

    The main reasons are:

    • operating leverage to the gold price;
    • expanding expected mining margins;
    • stronger expected cash flows;
    • investor rotation into gold equities;
    • royalty/streaming companies benefiting from higher metal prices without equivalent increases in operating costs.

    Key Takeaway

    The three-month trend remains positive for precious metals, but momentum has moderated since the August highs.

    Gold: +4.3%
    WPM: +25.8%
    AEM: +23.3%
    FNV: +19.4%
    ABX: +14.7%

    The main factor to watch now is U.S. monetary policy. Continued rate increases and rising Treasury yields would work against gold, while renewed geopolitical deterioration or falling real yields would provide renewed support.

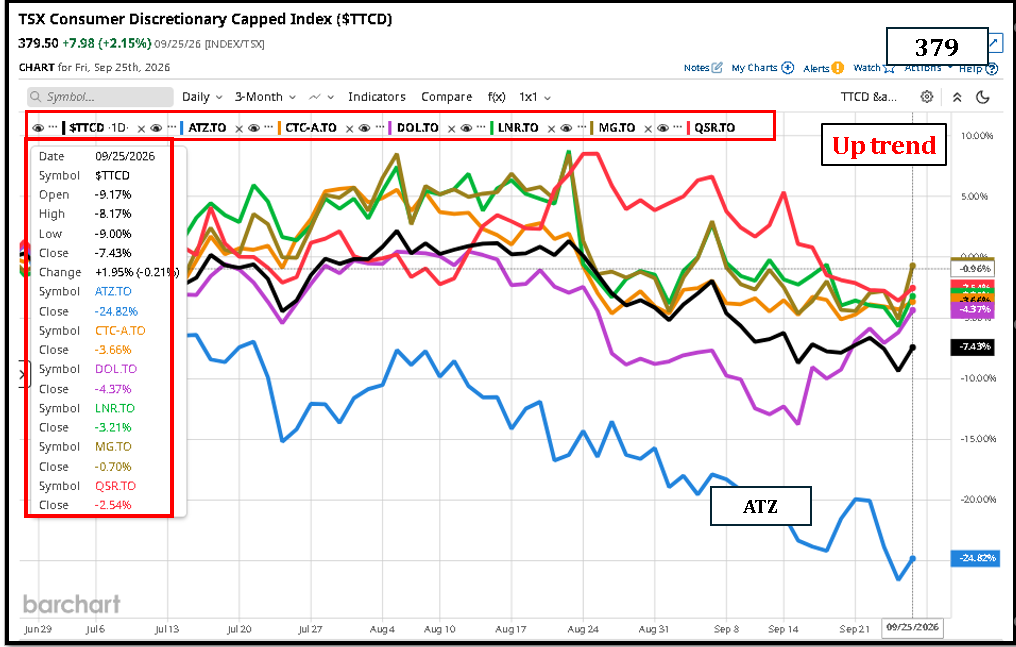
  • Consumer Discretionary Index ($TTCD) 3M Daily

    The TSX Consumer Discretionary Index ($TTCD) is showing a short-term rebound, but the 3-month picture is still mixed.

    • $TTCD: about -7.4% over 3 months, despite a strong +2.1% daily gain on Sept. 25.
    • ATZ.TO: weakest performer at roughly -24.8%. The large decline has been the main drag among the names shown.
    • CTC.A.TO: about -3.7%, relatively resilient versus the sector.
    • DOL.TO: about -4.4%, modest decline after earlier strength.
    • LNR.TO: about -3.2%, holding up comparatively well.
    • MG.TO: roughly -0.7%, strongest relative performer in the group shown.
    • QSR.TO: about -2.5%, also relatively defensive.

    Main Reasons

    The sector weakness likely reflects:

    1. Consumer spending concerns — discretionary businesses are more sensitive to slowing household demand.
    2. Higher borrowing costs / rate uncertainty — pressures auto, retail and other rate-sensitive spending.
    3. Tariff and trade uncertainty — particularly relevant for auto-related names such as Magna and Linamar.
    4. Company-specific weakness — especially Aritzia, which has significantly underperformed the rest of the group.
    5. Recent rebound — the upward move at the far right suggests some buying after the sector became heavily sold down.

    Bottom line: the chart shows an early rebound, not yet a confirmed 3-month uptrend. Most names remain below their late-June levels, with ATZ the clear laggard.

  • Education: Bond Yields?

    Bond yields are interest rates — the market rate for that maturity. Policy rates (Fed/BoC overnight) are the short end; bond yields are the rest of the curve. (*) See below

    How they connect

    • Policy rate ↑ → short yields rise first; longer yields follow if markets expect the hike to stick or inflation to stay hot.
    • Bond yields ↑ first (oil shock, strong data, deficit fears) → markets price more future hikes. That forces the Fed/BoC to stay tight or hike, even if they wanted a pause.
    • Last week: US 10y >5% (highest since 2007) + Canada 10y ~4.0% = market saying “another hike is coming.” That is what hit the TSX.

    What rising yields actually do

    ChannelEffect
    Mortgages / loansNew fixed rates reprice off the 5y/10y. Existing floating rates lag until reset.
    BanksFunding cost ↑; loan demand ↓; bond books marked down. High valuations make this worse (why CM/RY/TD sold off Sep 23).
    CorporatesDebt rollover more expensive → capex and buybacks slow.
    EquitiesHigher discount rate on future cash flows. Long-duration names (tech, growth, utilities) get hit first.
    CAD / inflationHigher CA yields support CAD if purely domestic; last week CAD slipped because US yields rose more and oil/geopolitics dominated.

    Last week’s loop (the one on your chart)
    Oil ↑ → inflation scare → US 10y to 5%+ → Canada 10y to ~4% → banks + miners sold → TSX −584 pts.
    Fri bounce = oil eased on Hormuz-deal talk → yields pulled back a bit → banks bounced.

    Rule of thumb: a 25–50 bp jump in the 10y, if it holds, is roughly one extra hike priced in. That is a tightening of financial conditions even before the central bank moves.

    (*) Two different rates, one curve.

    1. Policy rate (short end)
    Overnight rate set by the Fed or BoC.

    • Fed funds / BoC target: the rate banks charge each other overnight.
    • Directly controlled. Changed at meetings (hike, hold, cut).
    • Anchors the left side of the curve: overnight → 1-month → 3-month bills.

    2. Bond yields (the rest of the curve)
    The interest rate the market demands to lend to the government for 2, 5, 10, 30 years.

    • Not set by the central bank. Set by buyers and sellers of bonds.
    • If you buy a 10-year Canada bond at a price that implies 4%, that 4% is the 10-year interest rate.
    • Same for US Treasuries.

    How they fit together (the yield curve)

    Overnight   3m    2y     5y     10y    30y
      │         │     │      │      │      │
      BoC/Fed   bills  notes  notes  bonds  bonds
      (policy)  ←———— market-determined —————→
    • Left = policy.
    • Right = market’s forecast of future policy + inflation + term premium (extra pay for locking money up longer).

    Why they move together — but not 1-for-1

    • Hike expected → 2y yield jumps first (it is almost a bet on the next few meetings).
    • Inflation/oil/deficit scare → 10y and 30y jump even if the overnight rate has not moved yet. That is higher long-term interest rates.
    • Last week: Fed/BoC had not hiked that day. The 10y did. So market rates rose before the official rate did.

    Simple version
    Policy rate = what the central bank charges tonight.
    Bond yield = what the market charges to lend for years.
    Both are interest rates. The curve is just those rates lined up by maturity.

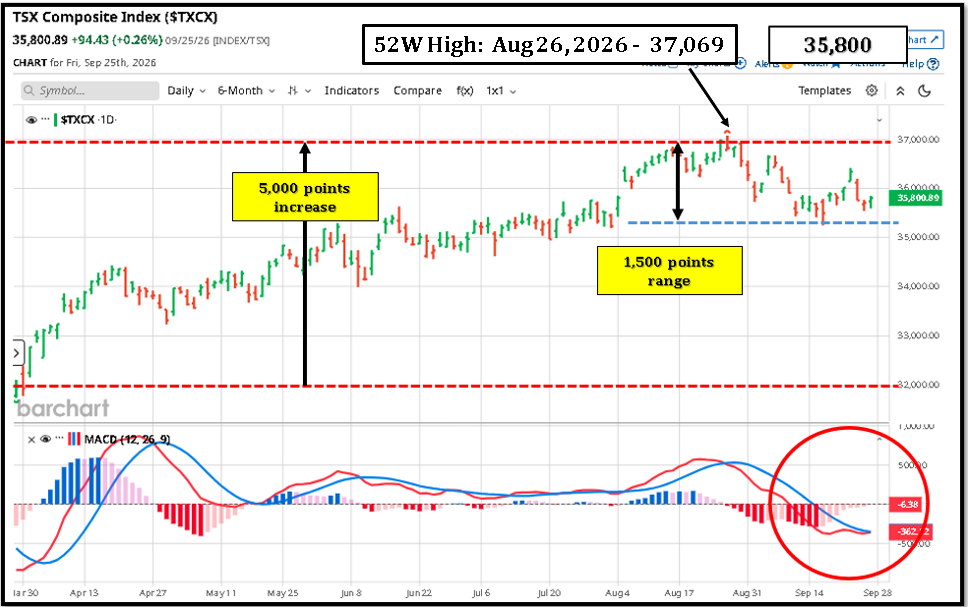
  • TSX 6M daily – Sept 25, 2026

      • Big picture: The TSX rose roughly 5,000 points from the ~32,000 area to approach 37,000 over the period shown.
      • Current level: At 35,800.89, the index is about 1,200 points below the 37,000 resistance area.
      • Recent range: Since the August peak, the TSX has largely traded in a ~35,500–37,000 range, roughly 1,500 points.
      • 37,000 = resistance: The repeated failure around 37,000 suggests sellers have emerged near that level.
      • 35,500 = support: The recent lows around 35,500 are an important near-term level. A sustained break below it would indicate the range is weakening.
      • MACD: The MACD has turned negative, with the MACD line below the signal line and a negative histogram. This indicates weakening momentum in the near term.
      • However: The index remains well above its earlier March/April levels, so the chart shows short-term consolidation/weakening momentum within a larger six-month uptrend, rather than a confirmed major reversal.
      In one sentence: The TSX has had a strong longer-term run, but it is currently consolidating between roughly 35,500 support and 37,000 resistance, with the negative MACD suggesting near-term momentum has weakened.
  • European markets — week ending September 25, 2026

    The key message from Europe this week was “relief from falling oil, but pressure from rising bond yields.” European equities snapped a three-week losing streak: the STOXX Europe 600 gained about 0.5%, its best weekly performance since early August. MMarketScreener+1

    Friday’s rebound was driven largely by a pullback in crude oil, which eased fears that the Middle East conflict would produce another inflation shock. But the rise in European and global bond yields limited the upside. MMarketScreener+1

    IndexSept. 25 closeWeekly moveMain driver
    STOXX 600~638.65+0.5%Oil relief, but yields remain a problem
    DAX25,408.64+0.4%Oil relief + industrial/tech resilience
    FTSE 10010,695.25roughly flat/slightly positiveEnergy & defensive exposure
    CAC 408,077.80roughly flatLuxury/consumer weakness offset broader relief

    The daily Friday closes were DAX +0.56%, FTSE 100 +0.14% and CAC 40 −0.04%. MMarketScreener Canada+1

    🇪🇺 STOXX 600 — modest recovery

    The STOXX 600 rose 0.5% for the week, ending a three-week losing streak. Friday’s 0.4% gain was particularly important because the index had fallen sharply on Thursday as oil and bond yields rose. MMarketScreener

    The week’s pattern was essentially:

    Oil ↑ + yields ↑ → European stocks ↓

    then

    Oil ↓ → European stocks ↑

    That tells you what investors were most concerned about.

    The fall in crude relieved pressure on energy-intensive companies and rate-sensitive growth stocks. But investors remained cautious because long-term bond yields were still elevated. IInvesting.com

    So the STOXX 600’s +0.5% doesn’t really represent a return to carefree risk-taking. It was more of a relief rally within a difficult macro environment.


    🇩🇪 DAX — Germany stabilizes

    The DAX finished at 25,408.64, gaining 0.56% Friday and approximately 0.4% for the week. Importantly, that broke a three-week losing streak. MMarketScreener Canada

    Germany’s market was particularly sensitive to the oil story because its large industrial sector is exposed to:

    • energy costs;
    • global manufacturing;
    • European demand;
    • interest rates;
    • global trade.

    The decline in crude therefore helped German equities late in the week.

    There was also considerable stock-specific movement. Evonik rose 7.19%, while BASF fell 3.59% and Airbus declined 1.02% on Friday. MMarketScreener Canada

    The important distinction is that the DAX wasn’t being driven by one single theme such as Japan’s AI rally. It was primarily responding to the macro combination of energy prices, rates and industrial earnings expectations.

    What to watch in Germany

    The major issue going forward is whether high energy prices become persistent enough to create a stagflationary environment—weakening industrial demand while keeping inflation elevated.

    That would be particularly relevant for Germany because of its industrial/export-heavy economy.


    🇬🇧 FTSE 100 — comparatively defensive

    The FTSE 100 closed Friday at 10,695.25, up 0.14% on the day. TTheCloseReport

    London had a somewhat different composition from Frankfurt and Paris.

    The FTSE 100 has substantial exposure to:

    • energy;
    • mining;
    • banks;
    • pharmaceuticals;
    • consumer staples;
    • other mature, international companies.

    That gives it somewhat different sensitivity to the oil/yield shock.

    Higher oil isn’t necessarily uniformly negative for the FTSE, because large energy companies can benefit from higher crude prices. At the same time, higher inflation and bond yields can pressure domestic consumers and interest-sensitive sectors.

    This helped make the FTSE relatively resilient compared with some continental European markets during parts of the week.


    🇫🇷 CAC 40 — essentially flat

    The CAC 40 ended Friday at 8,077.80, almost unchanged at −0.04%. TTheCloseReport

    France’s index has a particularly important exposure to luxury goods and globally oriented consumer companies.

    That makes the CAC sensitive not only to European economic conditions but also to:

    • Chinese consumer demand;
    • global travel;
    • currency movements;
    • global wealth effects;
    • interest rates.

    The CAC had already fallen 0.52% Thursday to 8,081.43, when higher oil prices and rising bond yields hit European equities

    Friday’s near-flat result therefore represented stabilization rather than a major new buying wave.


    What really drove European markets this week?

    1. 🛢️ Oil was the biggest swing factor

    This was probably the clearest theme.

    Europe entered the week worried that the Middle East conflict would keep crude elevated and feed directly into inflation.

    When oil rose, investors immediately worried about:

    higher inflation → higher interest rates → lower equity valuations.

    2. 📈 Bond yields remained a major headwind

    The second major issue was the global bond selloff.

    Higher government yields make equities less attractive on a relative basis and particularly affect companies whose valuations depend heavily on future earnings growth.

    Europe was already dealing with elevated inflation expectations. Earlier in September, euro-area inflation had moved above 3%, while rising energy prices pushed government bond yields to multi-year highs and increased expectations of tighter ECB policy.

    So Friday’s stock-market rebound shouldn’t be interpreted as the bond problem disappearing.


    3. 🏦 Europe is caught between growth and inflation

    This is the difficult setup:

    Oil ↑
    → inflation risk ↑
    → central banks less able to ease
    → bond yields ↑
    → equity valuations pressured

    But:

    Oil ↓
    → inflation pressure ↓
    → growth/consumer outlook improves
    → equities recover

    That explains much of the volatility this week.


    Europe versus Asia

    Putting this alongside your previous Asian-market summary gives a useful picture:

    RegionWeek’s dominant issueMarket response
    🇪🇺 EuropeOil + bond yieldsModerate recovery
    🇩🇪 GermanyOil + industrial exposure~+0.4%
    🇬🇧 UKEnergy/defensive compositionRelatively resilient
    🇫🇷 FranceLuxury + global demand + yields~flat
    🇯🇵 JapanAI/chips + dividendsStrongly positive
    🇮🇳 IndiaOil + foreign outflowsNegative
    🇨🇳🇭🇰 China/Hong KongChina/U.S. uncertaintyNegative

    The contrast is quite striking: Japan had an equity-specific AI/dividend catalyst, whereas European markets were largely trading the oil-versus-yields equation.

    Bottom line

    European equities had a relief week, not a decisive change in trend.

    The STOXX 600’s +0.5% and DAX’s ~+0.4% were helped by falling oil prices and a rebound on Friday. The FTSE 100 and CAC 40 were much more subdued. But elevated bond yields and the possibility of renewed energy-driven inflation remain the key risks.

    In other words:

    Europe got a reprieve from oil this week, but the bond market is still telling investors to remain cautious.